
Market Overview
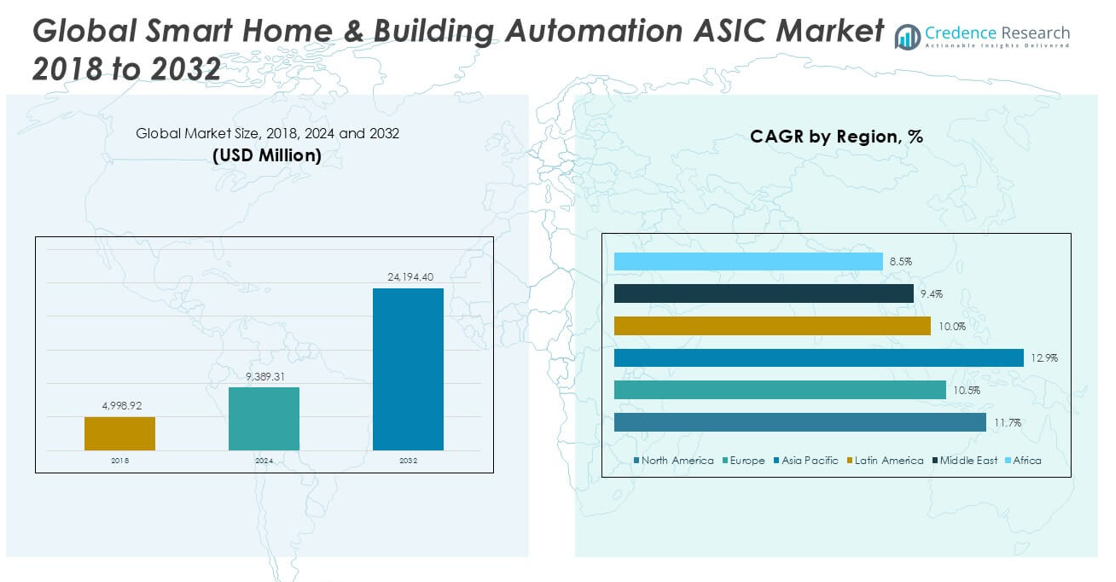
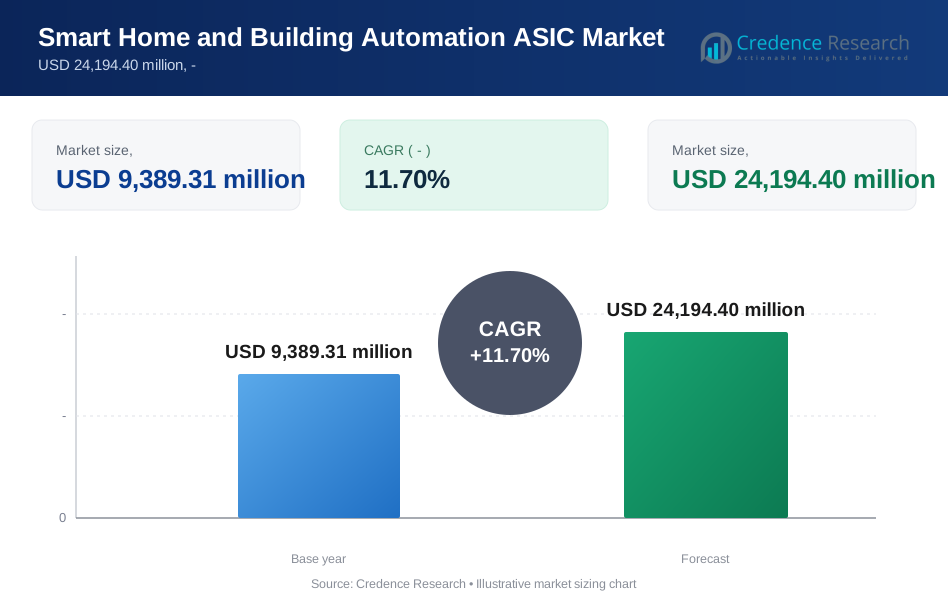
The Smart Home & Building Automation ASIC market size was valued at USD 4,998.92 million in 2018 and USD 9,389.31 million in 2024. It is anticipated to reach USD 24,194.40 million by 2032, growing at a CAGR of 11.70% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Smart Home & Building Automation ASIC Market Size 2024 | USD 9,389.31 million |
| Smart Home & Building Automation ASIC Market, CAGR | 11.70% |
| Smart Home & Building Automation ASIC Market, Size 2032 | USD 24,194.40 million |
The Smart Home & Building Automation ASIC market is led by prominent players such as Schneider Electric, Siemens AG, Cisco Systems, Robert Bosch, Honeywell International, ABB, Legrand, Crestron Electronics, and United Technologies Corporation. These companies hold a competitive edge through robust product portfolios, advanced R&D capabilities, and strategic partnerships. North America emerged as the leading regional market in 2024, accounting for 41.5% of the global market share, driven by early technology adoption, well-established infrastructure, and strong consumer demand for smart living solutions. Asia Pacific follows closely, supported by rapid urbanization and increasing smart device penetration across residential and commercial sectors.
Market Insights
- The Smart Home & Building Automation ASIC market was valued at USD 9,389.31 million in 2024 and is projected to reach USD 24,194.40 million by 2032, growing at a CAGR of 11.70% during the forecast period.
- Increasing demand for energy efficiency, automation, and safety in residential and commercial buildings is a key growth driver, supported by government initiatives promoting smart infrastructure.
- The market is witnessing a strong trend toward AI-integrated, IoT-enabled devices, with rising adoption of smart lighting systems—currently the dominant product segment.
- North America leads the regional market with a 41.5% share in 2024, followed by Asia Pacific at 30.7%, while the residential buildings segment holds the highest share by property type.
- High initial installation costs, data privacy concerns, and interoperability issues among devices continue to restrain market expansion, particularly in developing regions.
Market Segmentation Analysis:
By Product Type
The Smart Lighting Systems segment holds the largest market share in the Smart Home & Building Automation ASIC market by product type. This dominance is primarily attributed to the increasing adoption of energy-efficient lighting solutions and government incentives promoting smart lighting infrastructure. The integration of IoT and sensor-based systems in lighting enhances control, reduces operational costs, and improves energy management, driving significant demand. While smart thermostats and security cameras are also gaining traction, particularly in residential applications, lighting systems remain the top contributor due to their widespread use in both commercial and residential buildings.
- For instance, Signify (Philips Lighting) reported that its Interact IoT platform managed more than 64 million connected light points globally as of 2024, driven by ASIC-enhanced control systems for dynamic lighting optimization in buildings.
By Property Type
Residential Buildings dominate the Smart Home & Building Automation ASIC market by property type, holding the highest market share. This trend is driven by the rising consumer preference for home automation, improving living standards, and increasing awareness of energy efficiency. The surge in smart home adoption, especially in urban areas and among tech-savvy consumers, further boosts this segment. Additionally, the availability of affordable smart devices and government initiatives promoting smart residential infrastructure contribute to its growth. Commercial and industrial buildings also show steady expansion, mainly due to the need for centralized control systems and enhanced operational efficiency.
- For instance, Google Nest had installed over 11 million smart thermostats globally by 2023, integrating custom ASICs that support adaptive temperature control in residential buildings using AI-driven scheduling.
By Application
Lighting Control is the dominant application segment in the Smart Home & Building Automation ASIC market, capturing the largest share. Its prominence is driven by high energy savings, ease of integration, and widespread implementation across various property types. Automation of lighting systems allows users to reduce electricity consumption significantly, aligning with growing sustainability goals. Moreover, demand from smart offices and modern residential setups continues to support market growth. While HVAC control and security & access control are also expanding rapidly, lighting control maintains a leading position due to its cost-effectiveness, operational benefits, and energy conservation advantages.
Market Overview
Rising Demand for Energy Efficiency and Smart Living
The growing emphasis on energy efficiency and sustainability is a primary driver of the Smart Home & Building Automation ASIC market. Consumers and businesses are increasingly investing in automation systems to reduce energy consumption and lower utility costs. Smart ASIC components enable real-time monitoring and control of lighting, HVAC, and energy management systems, offering precise energy optimization. In addition, rising awareness of climate change and government regulations promoting green building technologies are accelerating the integration of smart automation solutions in both residential and commercial infrastructures.
- For instance, Honeywell Building Technologies implemented its ASIC-driven Building Management Solutions in over 23,000 commercial facilities, enabling reductions of up to 20,000 MWh annually in energy consumption across its installations.
Technological Advancements in IoT and AI Integration
Advances in IoT and AI technologies are significantly enhancing the capabilities of smart home and building automation systems. The integration of ASICs tailored for automation enables faster processing, lower power consumption, and increased device intelligence. AI-powered analytics further improve decision-making by learning user behavior and optimizing system performance. As a result, smart devices equipped with advanced ASICs are becoming more responsive, efficient, and autonomous, thereby driving their adoption across diverse end-use sectors such as manufacturing, healthcare, and smart cities.
Growing Adoption of Smart Security and Surveillance Systems
Security concerns across residential, commercial, and industrial properties have led to increased demand for intelligent surveillance systems. ASICs play a crucial role in enabling real-time image processing and remote access in smart security cameras, digital door locks, and access control devices. The ability to integrate these systems with mobile apps and cloud-based platforms enhances usability and monitoring efficiency. As crime prevention and property protection remain top priorities, the deployment of smart security systems continues to fuel the growth of automation ASICs in the market.
- For instance, Qualcomm’s QCS610/410 SoCs, integrated with edge AI capabilities, power over 1.5 billion IoT devices globally, including smart cameras and voice-controlled systems with embedded neural processing engines optimized for home automation.
Key Trends & Opportunities
Expansion of Smart City Initiatives
Governments and municipalities worldwide are investing heavily in smart city infrastructure, offering a major growth opportunity for the Smart Home & Building Automation ASIC market. These initiatives aim to enhance energy efficiency, safety, and public services through interconnected systems. ASIC-based automation solutions contribute significantly by providing reliable and customized processing capabilities for lighting, surveillance, and traffic management systems. As urbanization accelerates, the need for scalable and efficient smart city solutions will create sustained demand for advanced automation components.
- For instance, Siemens AG, through its smart infrastructure division, deployed over 3,000 ASIC-enabled traffic and lighting control systems in urban projects such as Vienna, Singapore, and London, enabling real-time data analytics for adaptive urban management.
Increased Demand for Wireless and Remote Access Solutions
The growing preference for wireless technologies and mobile-based controls presents a key trend in the smart automation sector. Consumers increasingly seek convenience and real-time access to control systems through smartphones and cloud platforms. ASICs designed for low-power, high-efficiency wireless connectivity enable seamless integration with Wi-Fi, Bluetooth, and Zigbee networks. This trend supports the development of compact, interoperable devices that enhance user experience while reducing infrastructure complexity, opening new avenues for product innovation and market expansion.
- For instance, Texas Instruments has shipped over 1.2 billion wireless connectivity ASICs for Zigbee and Bluetooth Low Energy applications, powering smart door locks, lighting, and climate control devices used in both residential and commercial automation ecosystems.
Key Challenges
High Initial Investment and Installation Costs
Despite the long-term cost-saving potential of smart automation, the high upfront cost of installation remains a significant barrier to adoption. ASIC development, smart device deployment, and system integration involve substantial capital expenditure, which may deter budget-conscious consumers and small enterprises. Moreover, retrofitting existing infrastructure with smart components adds to the cost burden. This financial challenge limits market penetration, particularly in developing regions where affordability is a critical factor.
Data Privacy and Cybersecurity Risks
With increasing connectivity comes heightened concern over data privacy and cybersecurity. Smart home and building automation systems collect and transmit vast amounts of sensitive user and operational data. Inadequate protection or system vulnerabilities can lead to unauthorized access, data breaches, or operational disruptions. ASICs designed for automation must incorporate robust encryption and secure communication protocols. However, the complexity of ensuring comprehensive security across all devices remains a persistent challenge, potentially hampering consumer trust and adoption.
Interoperability and Integration Issues
A lack of standardization across platforms and device ecosystems creates interoperability challenges in smart automation. Users often face difficulties in integrating devices from different manufacturers or upgrading legacy systems to support new technologies. These compatibility issues lead to fragmented user experiences and hinder seamless automation. Manufacturers must prioritize developing ASICs that support open protocols and modular architectures to address this barrier. Until industry-wide standards are established, achieving smooth integration will remain a critical hurdle in market growth.
Regional Analysis
North America
North America dominated the Smart Home & Building Automation ASIC market in 2024, accounting for approximately 41.5% of the global market with a valuation of USD 3,892.67 million, up from USD 2,095.15 million in 2018. The region is projected to reach USD 10,059.67 million by 2032, growing at a CAGR of 11.7%. The market growth is primarily driven by early technology adoption, high consumer awareness, and strong infrastructure for smart devices. The United States leads in demand due to widespread smart home penetration and supportive government policies promoting energy-efficient technologies.
Europe
Europe held a market share of approximately 18.8% in 2024, with a market value of USD 1,764.18 million, increasing from USD 990.39 million in 2018. The market is expected to reach USD 4,158.84 million by 2032, expanding at a CAGR of 10.5%. The region benefits from stringent energy regulations, a growing focus on sustainability, and rising investments in smart city projects. Countries like Germany, the UK, and France are at the forefront of adopting smart building technologies, particularly in commercial and residential sectors, contributing to the region’s steady growth in the ASIC market.
Asia Pacific
Asia Pacific is the fastest-growing regional market, with a CAGR of 12.9%, and held a market share of 30.7% in 2024, valued at USD 2,886.60 million, rising from USD 1,456.18 million in 2018. The market is forecast to reach USD 8,106.94 million by 2032. Rapid urbanization, rising middle-class income, and significant government initiatives in countries like China, Japan, and India are fueling demand for smart home and building automation solutions. The increasing proliferation of IoT devices and growing awareness of energy-efficient systems further drive ASIC deployment across various applications in the region.
Latin America
Latin America represented 4.7% of the global Smart Home & Building Automation ASIC market in 2024, with a market value of USD 436.91 million, up from USD 235.55 million in 2018. The region is projected to reach USD 996.15 million by 2032, growing at a CAGR of 10.0%. Market expansion is supported by gradual improvements in smart infrastructure and increased interest in home automation for enhanced security and energy management. Brazil and Mexico are emerging as key markets, with growing investments in smart cities and residential automation systems contributing to regional demand.
Middle East
The Middle East accounted for 2.7% of the market in 2024, valued at USD 250.85 million, up from USD 145.58 million in 2018. It is expected to grow at a CAGR of 9.4%, reaching USD 549.61 million by 2032. The market is driven by rising adoption of smart building technologies in high-end residential and commercial developments, particularly in countries like the UAE and Saudi Arabia. Strong investments in infrastructure modernization and luxury real estate, coupled with government support for smart cities, are key factors fueling demand for ASIC-based automation systems in the region.
Africa
Africa held a market share of 1.7% in 2024, with a market size of USD 158.10 million, up from USD 76.07 million in 2018. The region is expected to grow to USD 323.19 million by 2032, at a CAGR of 8.5%. Market growth is modest but steadily improving, driven by urban development and increasing interest in energy-efficient housing. South Africa and Kenya are emerging as early adopters of smart technologies. Limited infrastructure and affordability remain challenges, but gradual digitization and international investments in real estate and utilities are expected to support the region’s future growth.
Market Segmentations:
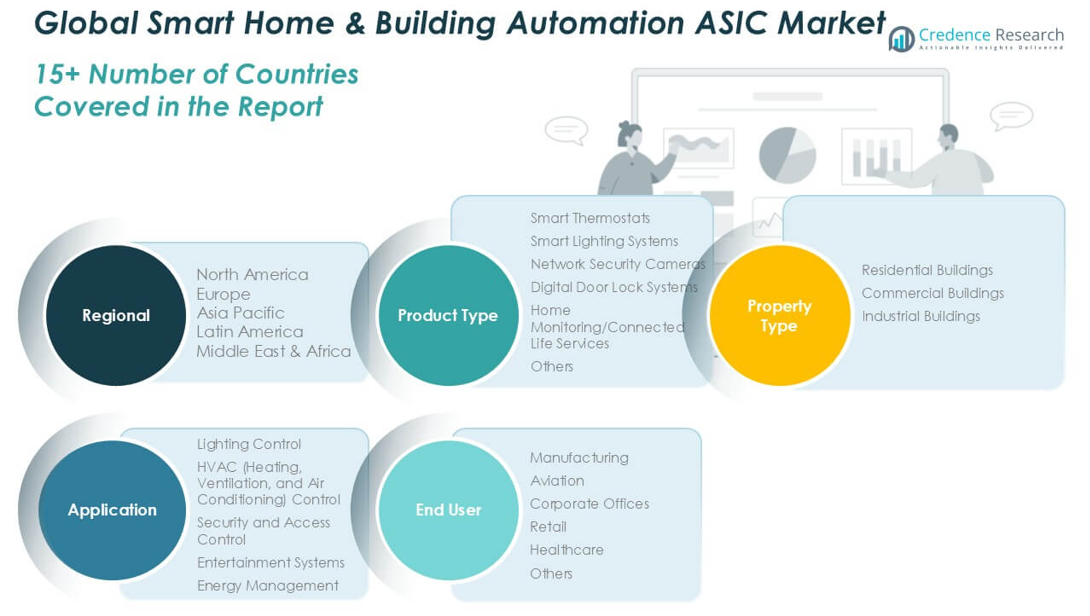
By Product Type
- Smart Thermostats
- Smart Lighting Systems
- Network Security Cameras
- Digital Door Lock Systems
- Home Monitoring/Connected Life Services
- Others
By Property Type
- Residential Buildings
- Commercial Buildings
- Industrial Buildings
By Application
- Lighting Control
- HVAC (Heating, Ventilation, and Air Conditioning) Control
- Security and Access Control
- Entertainment Systems
- Energy Management
By End User
- Manufacturing
- Aviation
- Corporate Offices
- Retail
- Healthcare
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Smart Home & Building Automation ASIC market is characterized by the presence of several global players actively investing in technological innovation and strategic partnerships. Leading companies such as Schneider Electric, Siemens AG, Cisco Systems, Robert Bosch, Honeywell International, ABB, Legrand, Crestron Electronics, and United Technologies Corporation dominate the market with comprehensive product portfolios and strong distribution networks. These firms focus on developing high-performance ASICs tailored for energy management, lighting control, security, and HVAC applications. Companies are increasingly integrating AI, IoT, and cloud connectivity into their offerings to enhance automation capabilities and user experience. Additionally, mergers, acquisitions, and collaborations with software developers and real estate firms have become key growth strategies to expand geographic reach and strengthen technological expertise. With the rising demand for smart infrastructure, market players continue to prioritize innovation, operational efficiency, and customer-centric solutions to maintain a competitive edge and capture emerging opportunities across global markets.
Key Player Analysis
- Schneider Electric
- Siemens AG
- Cisco Systems
- Robert Bosch
- Honeywell International
- ABB
- Legrand
- Crestron Electronics
- United Technologies Corporation
Recent Developments
- In June 2025, Siemens AG released an enhanced motion control portfolio featuring the SINAMICS S210/S200 servo drive systems and the SIMATIC S7-1200 G2 controllers. This new portfolio combines advanced processing, safety features, and is designed for basic automation tasks like handling, moving, positioning, and processing, as well as smart building applications.
- In February 2025, Schneider Electric introduced a new Smart Power Manager feature within the Square D QO Smart Panel Solution at the 2025 NAHB International Builders Show. This innovation enables software-based smart energy management, helping builders avoid costly electrical service upgrades (e.g. 200A to 400A), supporting the electrification of homes while maintaining cost efficiency.
- In February 2025, Cisco Systems Announced a family of data center Smart Switches, powered by programmable AMD Pensando DPUs, delivering embedded networking and security services, particularly optimized for AI workloads and smart building automation.
- In January 2025, Siemens AG showcased their vision for AI- and software-defined building automation at CES 2025, highlighting the Siemens Industrial Copilot, which brings real-time AI analytics directly to building and industrial operations.
- In January 2025, Robert Bosch announced the world's first Matter-enabled home appliance, the Bosch 100 Series refrigerator. This launch marked a significant step towards greater interoperability in smart homes, showcasing broad Matter protocol support and deepened collaboration for open, connected automation ecosystems. The refrigerator, part of the Bosch 100 Series French Door Bottom Mount, was highlighted at CES 2025.
Market Concentration & Characteristics
The Smart Home & Building Automation ASIC market exhibits a moderately concentrated structure with several dominant players, including Schneider Electric, Siemens AG, Cisco Systems, and Honeywell International, holding substantial market shares. These companies maintain their positions through continuous innovation, strategic acquisitions, and expansive global distribution networks. The market is characterized by rapid technological advancements, high integration of IoT and AI, and increasing demand for customized automation solutions across residential, commercial, and industrial applications. It features a strong inclination toward energy efficiency, wireless communication, and system interoperability. Entry barriers remain moderate due to the need for specialized design capabilities and significant capital investment in R&D. Price competitiveness, product differentiation, and compliance with regional regulatory standards influence vendor performance. The presence of both global and regional players creates a balanced competitive environment. It continues to evolve with shifting consumer preferences, rising smart city projects, and broader adoption of cloud-based automation platforms. The market favors firms capable of delivering scalable, secure, and user-friendly ASIC solutions.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Property Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness strong growth driven by increasing demand for energy-efficient and automated solutions in residential and commercial properties.
- Integration of AI and IoT technologies will continue to enhance the functionality and responsiveness of smart home and building systems.
- Asia Pacific is projected to become a key growth region due to rapid urbanization, rising disposable incomes, and government-led smart city initiatives.
- Demand for smart security and surveillance systems will rise, supporting the expansion of ASIC applications in access control and monitoring devices.
- Wireless communication technologies will play a larger role, enabling more flexible and scalable automation solutions.
- Development of cost-effective ASICs will make smart automation accessible to mid- and low-income markets, expanding consumer adoption.
- Partnerships between semiconductor firms and smart device manufacturers will increase, fostering innovation in customized chip designs.
- Sustainability regulations will push building developers to incorporate automation solutions for energy management and emission control.
- Data security and device interoperability will remain critical areas of focus as connectivity among systems grows.
- The market will continue evolving with increasing emphasis on user-friendly interfaces and mobile-integrated control platforms.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Smart Home & Building Automation ASIC Market?
What factors are driving the growth of the Smart Home & Building Automation ASIC Market?
What are some challenges faced by the Smart Home & Building Automation ASIC Market?
Who are the major players in the Smart Home & Building Automation ASIC Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Smart Home and Building Automation ASIC Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Smart Home and Building Automation ASIC Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 9,389.31 million → forecast year: USD 24,194.40 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Smart Home and Building Automation ASIC Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Smart Home and Building Automation ASIC Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Smart Home and Building Automation ASIC Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Smart Home and Building Automation ASIC Market Drivers
- 3.3 Smart Home and Building Automation ASIC Market Restraints & Challenges
- 3.4 Smart Home and Building Automation ASIC Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Smart Home and Building Automation ASIC Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Smart Home and Building Automation ASIC Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Smart Home and Building Automation ASIC category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Smart Home and Building Automation ASIC Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Smart Home and Building Automation ASIC Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Smart Home and Building Automation ASIC market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Smart Home and Building Automation ASIC Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Smart Home and Building Automation ASIC Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Smart Home and Building Automation ASIC Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Smart Home and Building Automation ASIC (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Smart Home and Building Automation ASIC Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Smart Home and Building Automation ASIC Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Smart Home and Building Automation ASIC Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Smart Home and Building Automation ASIC Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Smart Home and Building Automation ASIC Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Smart Home and Building Automation ASIC Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Smart Home and Building Automation ASIC Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Smart Home and Building Automation ASIC Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Smart Home and Building Automation ASIC Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
