
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Boat Building Market Size 2024 | USD 37,815.00 million |
| Boat Building Market, CAGR | 5.9% |
| Boat Building Market Size 2032 | USD 59818 million |
Market Overview:
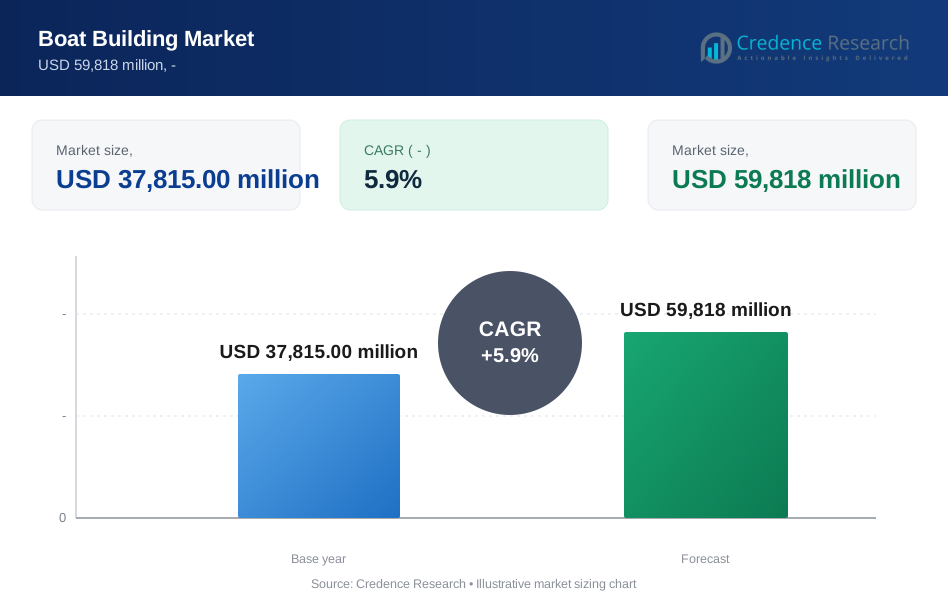
The Boat Building Market is projected to grow from USD 37,815.00 million in 2024 to an estimated USD 59818 million by 2032, with a compound annual growth rate (CAGR) of 5.9% from 2024 to 2032.
Key drivers propelling the Boat Building Market include rising interest in recreational boating, the expansion of marine tourism, and ongoing innovation in design and propulsion technology. Recreational boating has gained strong traction in North America, Europe, and parts of Asia-Pacific, supported by favorable economic conditions and the growing popularity of outdoor leisure activities. Commercial applications such as ferry services, sightseeing, water taxis, and fishing vessels are also contributing significantly to the market’s expansion, particularly in developing regions investing in marine transport infrastructure. Military and defense demand remains stable due to investments in coastal security, naval modernization, and maritime surveillance operations. Technological progress has allowed for lighter, more durable materials such as fiberglass and composites, along with efficient electric and hybrid propulsion systems that meet emerging environmental standards. Smart features-such as GPS-based navigation, onboard diagnostics, and digital control systems-are further enhancing the value proposition of modern vessels. Environmental sustainability and regulatory compliance have become central to boat design and manufacturing strategies, promoting investments in clean propulsion and recyclable materials.
Regionally, North America leads the Boat Building Market, accounting for roughly 36% of global revenue. The United States serves as the primary contributor, with a well-established recreational boating culture, widespread marina infrastructure, and robust production capabilities. Brands like Brunswick Boat Group and Malibu Boats dominate the market through a diversified portfolio and strong distribution channels. Europe holds a share of around 28%, with Italy, Germany, and the Netherlands excelling in luxury yacht production, naval vessels, and innovation in sustainable propulsion systems. The region benefits from strong exports, especially in high-end and custom-built boats, and supports its domestic markets through developed inland and coastal waterways. Asia-Pacific contributes approximately 22%, with rapid growth in China, South Korea, and Australia driven by increasing regional demand and the expansion of domestic shipbuilding capacity. Government investment in marine tourism and transport in countries like India and Indonesia is also fueling demand for commercial vessels and ferries. South America, the Middle East, and Africa together account for the remaining market share, showing moderate but growing demand in defense, tourism, and infrastructure-related boat orders. These regions are becoming increasingly attractive for global manufacturers seeking new growth opportunities through strategic partnerships and localized production. The Boat Building Market continues to evolve with regional strengths, balancing traditional craftsmanship with emerging technologies and diversified use cases.
Market Insights:
- The Boat Building Market is projected to grow from USD 37.8 billion in 2024 to USD 59.8 billion by 2032, reflecting a strong CAGR of 5.9%.
- Rising recreational boating activity, particularly in North America and Europe, continues to drive demand for new personal and family watercraft.
- Technological innovation in materials, propulsion, and smart systems is increasing performance, efficiency, and user appeal across vessel categories.
- Defense spending on coastal security and naval modernization is supporting long-term contracts for patrol boats, USVs, and multi-role vessels.
- Marine tourism recovery and charter growth in tropical and Mediterranean regions are expanding commercial demand for sightseeing and hospitality boats.
- Persistent cost pressures from raw materials and supply chain disruptions are challenging profitability, especially for small and mid-sized manufacturers.
- North America holds the largest market share at 36%, followed by Europe at 28% and Asia-Pacific at 22%, each leveraging regional strengths in leisure, defense, or commercial production.
Market Drivers:
Growing Recreational Boating Culture Drives Demand for New Builds:
Recreational boating has become a key lifestyle choice across coastal and lakefront regions, especially in North America and Europe. Rising disposable income and interest in outdoor leisure are encouraging consumers to invest in yachts, sailboats, fishing boats, and personal watercraft. Countries such as the United States, Australia, and Germany are witnessing a surge in recreational boat ownership, supported by expanding marina infrastructure and marine tourism. The Boat Building Market is responding with tailored product offerings across size, design, and performance categories. Manufacturers are also offering customizable solutions to meet varying consumer preferences. This trend is creating consistent demand for both mass-market and high-end vessels.
- According to the National Marine Manufacturers Association, about 87 million Americans engage in recreational boating, reinforcing the segment’s dominance.
Technological Advancements Enhance Performance and Efficiency:
Innovation in materials and propulsion systems is transforming traditional boat construction. Advanced composites, 3D printing, and automation are reducing weight and increasing fuel efficiency. Hybrid and electric propulsion systems are gaining popularity among environmentally conscious buyers and regulatory bodies pushing for low-emission vessels. The Boat Building Market benefits from these developments by delivering quieter, more efficient, and longer-range models. Manufacturers are integrating digital navigation, remote diagnostics, and smart control systems to appeal to tech-savvy consumers. These advancements also reduce maintenance needs and improve long-term value for owners.
- For example, Hybrid and electric propulsion systems are gaining traction, as Mercury Marine’s partnership with JJE in May 2023 aims to expand high-voltage electric propulsion systems, and the outboard electric segment led the market in 2024.
Defense and Security Needs Expand Government Contracts:
Global demand for naval and patrol vessels is rising amid growing maritime security concerns. Governments are investing in coastal defense, anti-piracy operations, and search-and-rescue capabilities, requiring a steady supply of advanced, mission-specific boats. The Boat Building Market is capturing this opportunity through contracts with naval forces, border agencies, and coast guards. It is driving the development of high-speed interceptor boats, unmanned surface vehicles (USVs), and multi-role combat craft. Domestic shipbuilding programs are also promoting self-reliance and stimulating regional industry. These projects provide long-term revenue stability and support ongoing R&D investments.
Charter and Tourism Sectors Accelerate Commercial Vessel Demand:
Marine tourism is recovering strongly, with charter services gaining traction in tropical and Mediterranean destinations. High tourist traffic is prompting charter operators to expand fleets and upgrade existing vessels. The Boat Building Market supports this growth by supplying commercial boats designed for sightseeing, fishing, diving, and hospitality. Builders are focusing on safety features, passenger comfort, and regulatory compliance to meet operator needs. This segment also benefits from regional government support in coastal development and tourism promotion. It creates recurring demand for mid-sized boats with multi-purpose configurations.
Market Trends:
Shift Toward Sustainable and Electric Propulsion Solutions:
Environmental awareness and regulatory pressure are driving a shift toward eco-friendly propulsion systems in the marine sector. Consumers and governments are increasingly favoring electric, hybrid, and low-emission alternatives over conventional fuel-powered engines. Manufacturers are investing in battery technology, solar integration, and lightweight materials to improve range and performance. The Boat Building Market is adapting to this trend by incorporating sustainable design principles into new builds. Builders are launching electric-powered leisure boats, ferries, and utility vessels, especially for use in inland waterways and environmentally sensitive zones. This trend aligns with global decarbonization goals and supports compliance with future emission standards.
- For example, electric propulsion systems produced zero emissions and offered instant torque and low maintenance, with lithium-ion battery advancements enabling longer ranges and faster charging.
Increased Adoption of Smart and Connected Boat Technologies:
Digital transformation is reshaping customer expectations in the marine industry. Modern boats now feature integrated systems that enable navigation, diagnostics, entertainment, and remote monitoring. The Boat Building Market is embracing this shift by embedding IoT sensors, GPS-based tracking, and cloud-based control platforms into vessel designs. Smart dashboards and mobile applications allow users to manage boat functions and receive performance updates in real time. Builders are also offering predictive maintenance features and cybersecurity protocols to enhance safety and user experience. This trend is gaining momentum among both recreational and commercial boat operators seeking convenience and operational efficiency.
- For example, Builders are embedding cybersecurity protocols and cloud-based control platforms, as highlighted by the U.S. Coast Guard’s 2024 CTIME report on cyber risks in maritime operations.
Growth of Customization and Modular Design Preferences:
Boat buyers are seeking more personalized solutions, prompting manufacturers to offer greater flexibility in design and configuration. Custom interiors, deck layouts, propulsion options, and onboard amenities are becoming standard in mid- to high-end segments. The Boat Building Market is responding by adopting modular construction techniques that allow quick adaptation to customer preferences. This approach shortens production cycles and reduces inventory risks. Builders are also using virtual design tools to let buyers preview and adjust specifications before manufacturing. Customization enhances customer satisfaction and differentiates brands in a competitive market landscape.
Rising Popularity of Multi-Purpose and Multi-Hull Vessels:
Consumers and commercial operators are showing increasing interest in boats that serve multiple functions. Catamarans and trimarans are gaining traction for their stability, space efficiency, and fuel economy. These vessels are ideal for tourism, transport, research, and offshore support operations. The Boat Building Market is evolving with demand for modular, multi-hull platforms that accommodate different applications with minimal modification. Their broader deck areas and shallower drafts make them suitable for diverse environments, including coastal, inland, and shallow water zones. This trend supports versatility and long-term asset value for owners and operators.
Market Challenges Analysis:
High Production Costs and Supply Chain Constraints Limit Profit Margins:
Boat manufacturing involves high material, labor, and compliance costs that often reduce profit margins for builders. Advanced composites, marine-grade metals, and electronic systems significantly increase production expenses. Global supply chain disruptions, especially delays in sourcing engines, navigation systems, and specialty components, have further raised input costs. The Boat Building Market faces delays in order fulfillment and difficulties in maintaining competitive pricing. Smaller manufacturers struggle to absorb these shocks without passing costs to customers. Uncertainty in raw material prices and shipping rates continues to pressure overall production efficiency.
Regulatory Compliance and Skilled Labor Shortages Hamper Scalability:
Strict safety, emission, and environmental regulations vary across regions, adding complexity to design, testing, and certification processes. Builders must navigate evolving rules related to emissions, noise levels, and safety features, which require technical adaptation and increase compliance costs. The Boat Building Market also contends with a limited pool of skilled labor, particularly in specialized areas such as composite fabrication, marine electronics, and naval engineering. Recruiting and retaining qualified personnel is a growing challenge for many regional shipyards. Labor shortages constrain production capacity and hinder the ability to scale operations to meet rising demand. This bottleneck limits the market’s responsiveness to global opportunities.
Market Opportunities:
Expansion in Electric and Hybrid Boat Segments Creates New Revenue Streams:
The global shift toward sustainability is creating strong demand for electric and hybrid propulsion vessels. Governments are offering incentives and regulatory support for clean energy adoption in marine transportation. The Boat Building Market can capitalize on this trend by investing in zero-emission technologies and lightweight materials. Opportunities exist in leisure boats, urban ferries, and inland waterway vessels that require low-noise, low-emission performance. Builders that integrate energy-efficient systems and battery technologies into their designs can gain a competitive edge. This segment presents long-term growth potential aligned with environmental and regulatory priorities.
Emerging Tourism Markets and Marina Infrastructure Stimulate Growth:
Rising interest in marine tourism across Southeast Asia, the Middle East, and Latin America is increasing demand for charter boats and tour vessels. Governments and private developers are investing in marinas, cruise terminals, and coastal infrastructure to attract high-spending visitors. The Boat Building Market stands to benefit from custom orders for sightseeing boats, dive support vessels, and floating hospitality platforms. Builders can offer region-specific designs that suit shallow waters, tropical climates, and short-haul routes. Partnerships with tour operators and coastal developers can open new sales channels. Growth in this segment supports diversification beyond traditional recreational markets.
Market Segmentation Analysis:
By Type
Recreational boats dominate the Boat Building Market, driven by rising leisure boating activities in North America and Europe. Commercial boats, including ferries, tour vessels, and workboats, support transportation, tourism, and offshore services. Military boats maintain steady demand through government procurement for patrol, surveillance, and combat roles. Other types include rescue boats and research vessels tailored to specialized functions.
- For example, Commercial boats, including ferries, tour vessels, and workboats, support transportation, tourism, and offshore services, while military boats maintain steady demand through government procurement, such as India’s acquisition of 11 rigid hull boats for naval operations.
By Propulsion
Motor boats hold the largest share due to their wide use across private, commercial, and defense sectors. Sail boats attract a niche segment focused on traditional and eco-friendly navigation, particularly in recreational sailing.
- For example, Commercial boats, including ferries, tour vessels, and workboats, support transportation, tourism, and offshore services, while military boats maintain steady demand through government procurement, such as India’s acquisition of 11 rigid hull boats for naval operations.
By Application
Private use accounts for significant market volume, especially in recreational boating hubs. Commercial use is expanding in tourism and utility operations. Military use remains consistent through national defense programs.
By Material
Fiberglass is widely used for its durability, lightweight properties, and cost efficiency. Aluminum and steel are preferred for commercial and military vessels requiring structural strength. Composite materials are gaining attention in high-performance segments, while wood remains limited to custom and heritage builds.
By Size/Capacity
Small boats dominate in personal and light-commercial segments. Medium boats are in demand for tourism, fishing, and transport. Large boats are mostly used in luxury, naval, and offshore operations.
Segmentation:
By Type
- Recreational Boats
- Commercial Boats
- Military Boats
- Other Types
By Propulsion
- Motor Boats
- Sail Boats
By Application
- Private Use
- Commercial Use
- Military Use
By Material
- Wood
- Steel
- Aluminum
- Fiberglass
- Composite Materials
- Others
By Size/Capacity
- Small Boats
- Medium Boats
- Large Boats
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Leads with Strong Recreational Demand and Advanced Infrastructure
North America holds the largest share of the Boat Building Market, accounting for approximately 36% of global revenue. The United States drives demand with a well-established recreational boating culture, expansive marina networks, and a high concentration of boat owners. Leading manufacturers operate across coastal states, offering a wide range of fiberglass and aluminum vessels. Government support for domestic shipbuilding and naval contracts also boosts defense and commercial output. Canada contributes with robust demand for fishing and utility boats, particularly in coastal and inland water regions. The market benefits from a mature regulatory environment and consistent consumer spending on marine leisure.
Europe Maintains Steady Growth with Innovation and Export Orientation
Europe holds around 28% of the global Boat Building Market, supported by strong production in Italy, France, Germany, and the Netherlands. The region emphasizes design innovation, luxury yacht manufacturing, and sustainable propulsion technologies. Shipyards in Italy and France serve both domestic and international buyers, including high-net-worth individuals and commercial charter fleets. Inland waterways in Germany and Eastern Europe sustain demand for compact leisure and transport vessels. European builders are also at the forefront of electric and hybrid boat development, driven by strict emissions regulations. It remains a key exporter of both high-end and utility marine craft.
Asia Pacific Emerges as a High-Growth Region with Expanding Output
Asia Pacific accounts for approximately 22% of the Boat Building Market and is positioned for accelerated growth. China, South Korea, and Australia lead regional production, supported by increasing coastal development and marine tourism. China is investing in both recreational and commercial shipyards to reduce reliance on imports and build domestic capacity. India and Southeast Asian nations are seeing rising interest in passenger ferries, fishing boats, and coastal surveillance vessels. The region benefits from low-cost manufacturing and growing demand for mid-range and budget-friendly boats. Market expansion is supported by infrastructure development and a rising middle class entering recreational marine activities.
Key Player Analysis:
- Brunswick Boat Group
- Groupe Beneteau
- Azimut-Benetti Group
- Ferretti S.P.A.
- Correct Craft
- Malibu Boats Inc.
- Mastercraft Boat Holdings
- Marine Products Corporation
- Smoker Craft Boats
- Hyundai Heavy Industries
- Mitsubishi Heavy Industries
- DSME (Daewoo Shipbuilding & Marine Engineering)
- Samsung Heavy Industries
- Tsuneishi Holdings
- Cochin Shipyard Limited
- Hindustan Shipyard Limited
- General Dynamics
- Meyer Werft
- Fincantieri
- Damen Shipyards Group
Competitive Analysis:
The Boat Building Market features a mix of global, regional, and niche manufacturers competing across leisure, commercial, and defense segments. Key players include Brunswick Corporation, Groupe Beneteau, Azimut-Benetti Group, Sunseeker International, and Damen Shipyards, each offering diverse product portfolios and strong brand recognition. North American and European firms dominate the luxury and recreational segments, while Asian shipbuilders are expanding in small commercial vessels and price-sensitive markets. Competitive differentiation is driven by design innovation, propulsion technology, customization capabilities, and after-sales support. Strategic partnerships, dealership networks, and digital marketing play critical roles in expanding global reach. The Boat Building Market also sees rising competition from new entrants adopting modular designs and electric propulsion platforms. Consolidation through mergers and acquisitions remains active, with larger firms acquiring specialized builders to enhance product depth and regional access. Competitive intensity is expected to increase as sustainability and digital integration reshape customer expectations.
Recent Developments:
- In May 2025, Brunswick won six Boating Industry Top Product Awards and, in January, launched AI-powered boating features and electric propulsion concepts at CES 2025.
- In February 2025, Groupe Beneteau announced nearly 20 new models for the 2025 Cannes Show and, in July 2024, partnered with Le Boat to build 400 new Delphia boats over 10 years.
Market Concentration & Characteristics:
The Boat Building Market is moderately fragmented, with a mix of large global players and numerous small to mid-sized regional manufacturers. It operates under a high degree of customization, with products tailored to leisure, commercial, and defense applications. Demand patterns vary by geography, influenced by income levels, coastal access, and government investment in marine infrastructure. The market relies on skilled labor, advanced materials, and compliance with strict safety and environmental standards. Product differentiation is driven by design, propulsion systems, and onboard technology. Innovation in electric propulsion and smart systems is reshaping buyer expectations. The market favors firms with strong distribution networks, after-sales service, and the ability to meet diverse regulatory requirements.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Application, By Size/Capacity and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for recreational boats will increase due to rising disposable incomes and lifestyle shifts.
- Electric and hybrid propulsion adoption will grow, driven by emission regulations and consumer preference.
- Marine tourism expansion in emerging economies will fuel demand for charter and commercial vessels.
- Technological integration will accelerate, with smart systems and automation becoming standard features.
- Customization and modular design options will drive differentiation in mid-to-high-end segments.
- Defense and security contracts will boost naval and patrol boat production globally.
- Asia Pacific will gain market share through cost-competitive manufacturing and rising regional demand.
- Infrastructure development, such as marinas and ports, will support broader vessel deployment.
- Environmental compliance and sustainable materials will shape production and procurement strategies.
- Strategic mergers and acquisitions will increase as firms seek scale, innovation, and market access.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Recreational Boating Culture
Increasing disposable incomes and a shift toward outdoor leisure activities are driving demand for new recreational boats, especially in North America and Europe. Expanding marina infrastructure and marine tourism further support this trend, leading to consistent sales of yachts, sailboats, and personal watercraft.
Technological Advancements in Materials and Propulsion
Innovations such as advanced composites, electric and hybrid propulsion systems, and smart onboard technologies are making boats lighter, more efficient, and environmentally friendly. These advancements attract both recreational and commercial buyers seeking performance, sustainability, and lower operating costs.
Expansion of Marine Tourism and Charter Services
The recovery and growth of marine tourism, particularly in tropical and Mediterranean regions, is boosting demand for sightseeing, hospitality, and charter vessels. Investments in coastal infrastructure and government support for tourism are creating new opportunities for boat builders.
Stable Defense and Security Spending
Ongoing investments in coastal security, naval modernization, and maritime surveillance are sustaining demand for military and patrol boats. Government contracts provide long-term revenue stability and drive innovation in mission-specific vessel design.
Shift Toward Sustainable and Electric Propulsion
Environmental regulations and consumer preference for low-emission vessels are accelerating the adoption of electric and hybrid boats. Manufacturers investing in clean propulsion technologies are well-positioned to capture emerging market segments and comply with evolving standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Boat Building Market?
What factors are driving the growth of the Boat Building Market?
What are some challenges faced by the Boat Building Market?
Who are the major players in the Boat Building Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Recreational Boats
- 1.2.2 Commercial Boats
- 1.2.3 Military Boats
- 1.2.4 Other Types
- 1.3 By Material
- 1.3.1 Wood
- 1.3.2 Steel
- 1.3.3 Aluminum
- 1.3.4 Fiberglass
- 1.3.5 Composite Materials
- 1.3.6 Others
- 1.4 By Propulsion
- 1.4.1 Motor Boats
- 1.4.2 Sail Boats
- 1.5 By Application
- 1.5.1 Private Use
- 1.5.2 Commercial Use
- 1.5.3 Military Use
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 37,815.00 million → 2032: USD 59,818 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Boat Building Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Boat Building Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Boat Building Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Boat Building Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Boat Building Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Boat Building Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Boat Building Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Boat Building Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 37,815.00 million → 2032: USD 59,818 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Boat Building Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Recreational Boats
- 12.3.7.2 Commercial Boats
- 12.3.7.3 Military Boats
- 12.3.7.4 Other Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Wood
- 12.4.7.2 Steel
- 12.4.7.3 Aluminum
- 12.4.7.4 Fiberglass
- 12.4.7.5 Composite Materials
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Propulsion - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Motor Boats
- 12.5.7.2 Sail Boats
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Private Use
- 12.6.7.2 Commercial Use
- 12.6.7.3 Military Use
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Boat Building End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Boat Building Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Boat Building Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Boat Building Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Brunswick Boat Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Groupe Beneteau
- 18.4 Azimut-Benetti Group
- 18.5 Ferretti S.P.A.
- 18.6 Malibu Boats Inc.
- 18.7 Mastercraft Boat Holdings
- 18.8 Damen Shipyards Group
- 18.9 Hyundai Heavy Industries
- 18.10 Fincantieri
- 18.11 Mitsubishi Heavy Industries
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

