
Building Integrated Photovoltaic (BIPV) Market Overview:
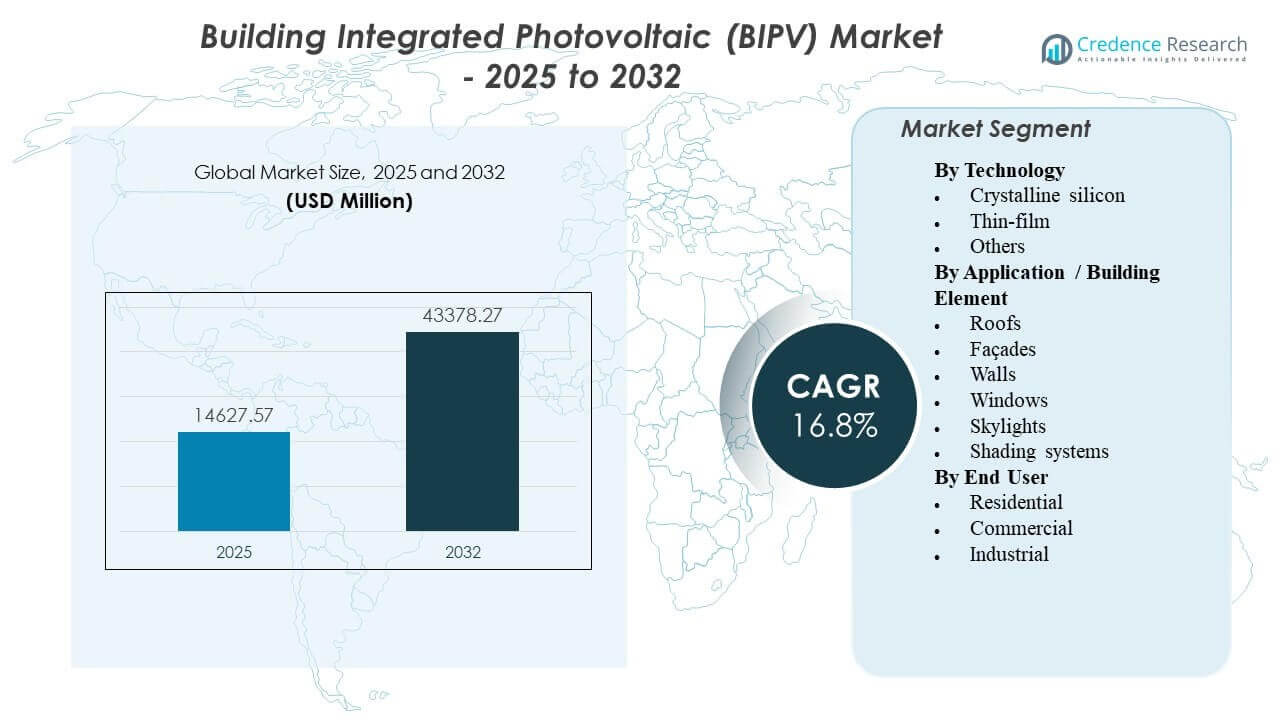
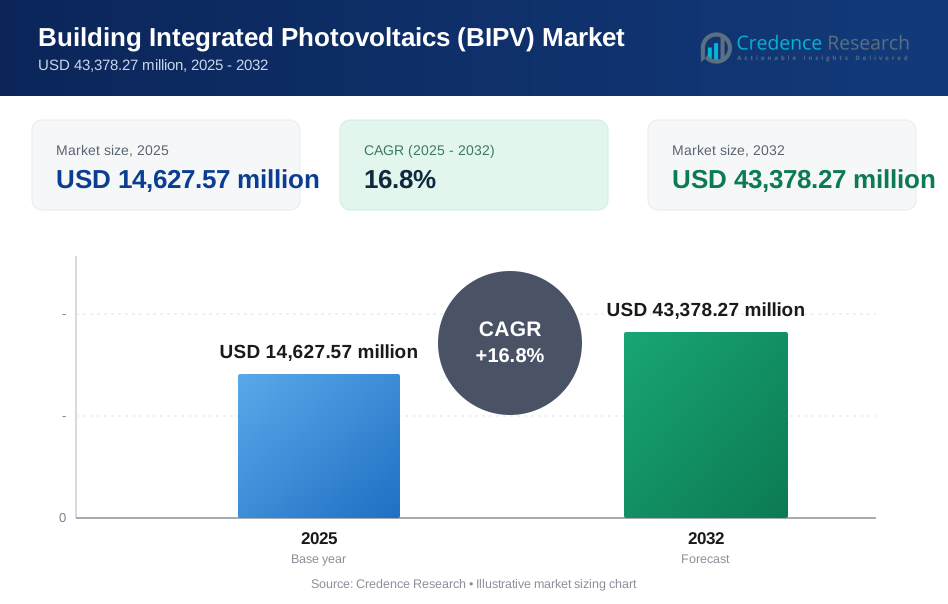
The global Building Integrated Photovoltaic (BIPV) Market size was estimated at USD 14,627.57 million in 2025 and is expected to reach USD 43,378.27 million by 2032, growing at a CAGR of 16.8% from 2025 to 2032. Growth is primarily driven by stricter building energy codes and net-zero building targets that push developers to integrate on-site generation into roofs, façades, and glazing. Demand is also supported by improving product aesthetics and wider availability of integrated solar building materials across premium residential and commercial projects.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Building Integrated Photovoltaic (BIPV) Market Size 2025 | USD 14,627.57 million |
| Building Integrated Photovoltaic (BIPV) Market, CAGR | 16.8% |
| Building Integrated Photovoltaic (BIPV) Market Size 2032 | USD 43,378.27 million |
Key Market Trends & Insights
- The Building Integrated Photovoltaic (BIPV) Market is expanding at a CAGR of 8% during 2025–2032.
- Europe accounted for the largest regional share of 9% in 2025, supported by stronger green-building adoption and regulatory pressure for building decarbonization.
- Crystalline silicon remained the leading technology with a share of 9% in 2025, reflecting efficiency-led project selection for building envelopes.
- Roofs represented the largest building-element application with 8% share in 2025, supported by usable surface area and straightforward integration in new builds and retrofits.
- Commercial end users held 1% share in 2025, driven by larger project sizes, ESG-linked procurement, and building performance benchmarking.
Segment Analysis
The Building Integrated Photovoltaic (BIPV) Market is shaped by a shift from add-on rooftop PV toward integrated building-envelope solutions that combine power generation with structural or architectural function. Developers and asset owners increasingly evaluate BIPV as a design-led energy asset that can support compliance with energy-performance standards, reduce operational emissions, and improve building value proposition. Procurement decisions frequently weigh aesthetics, durability, warranty strength, and integration complexity alongside energy yield.
Technology selection is guided by bankability and performance reliability, with most projects prioritizing proven module efficiency and predictable lifecycle output. Roof-led deployments dominate near-term volumes because roof surfaces offer scale and simplified integration, especially for commercial buildings targeting measurable reductions in grid electricity use. End-user adoption remains strongest in commercial buildings, where payback pathways are clearer through larger load profiles, centralized decision-making, and sustainability reporting requirements.
By Technology Insights
Crystalline silicon accounted for the largest share of 68.9% in 2025. Crystalline silicon leadership is supported by higher conversion efficiency and mature supply chains that reduce project performance risk. Many building-envelope projects prioritize dependable yield, long service life, and standardized installation ecosystems, which favors crystalline silicon formats. Thin-film solutions remain relevant for design flexibility and lightweight applications, but crystalline silicon remains preferred for yield-focused roof and façade integration.
By Application / Building Element Insights
Roofs accounted for the largest share of 65.8% in 2025. Roof surfaces typically provide the highest usable area and simpler construction pathways compared with façade or glazing elements, supporting broader adoption in both new builds and retrofits. Roof-integrated BIPV also aligns well with self-consumption strategies in commercial buildings that can absorb daytime generation. Façades, windows, skylights, and shading systems grow through architectural differentiation, but these elements commonly require higher engineering coordination and customized specifications.
By End User Insights
Commercial accounted for the largest share of 53.1% in 2025. Commercial adoption benefits from larger project scale, structured capital planning, and stronger pressure to document building-energy performance improvements. Many commercial deployments pair BIPV with energy-management upgrades to demonstrate measurable reductions in operational emissions. Residential demand is supported by premium housing projects and incentive-driven adoption, whereas industrial uptake is more selective and concentrated in sites with suitable envelopes and higher energy intensity.
Building Integrated Photovoltaic (BIPV) Market Drivers
Building decarbonization mandates and energy-performance regulations
Building energy codes and carbon-reduction requirements are pushing developers toward envelope-integrated renewables as part of compliance planning. BIPV supports on-site generation without requiring additional land area, making adoption relevant in dense urban environments. Net-zero and near-zero energy building targets increase the value of integrated solutions that contribute to annual energy balance. Public-sector procurement and green-building certification requirements further reinforce BIPV specification in new projects.
- For instance, the Perpignan Saint-Charles fruit logistics warehouse in France integrated about 97,000 solar shingles over a 7-hectare roof to create an approximately 11 MW BIPV system that generates around 10.7 GWh of electricity per year, directly supporting on-site decarbonization goals under French building energy regulations.
Rising commercial sustainability commitments and ESG-linked investment
Corporate sustainability targets increasingly translate into building-level actions, especially in offices, retail, and institutional buildings. BIPV offers a visible and measurable decarbonization pathway that can strengthen green-lease positioning and tenant preferences. Portfolio owners also use on-site generation to reduce exposure to electricity price volatility and strengthen energy resilience planning. Financing frameworks that favor low-carbon buildings can improve project economics for integrated PV installations.
Advances in PV building materials and improved architectural acceptance
Product innovation across PV glass, façade modules, and lightweight solutions improves design flexibility and reduces aesthetic barriers. Better integration approaches reduce balance-of-system complexity, helping architects specify PV within building envelope packages. Improvements in durability and system warranties support higher confidence among developers and owners. As installed references expand, the market benefits from faster specification cycles and broader familiarity among design and engineering stakeholders.
- For instance, a retrofit project with colored BIPV façade modules documented by IEA PVPS accepted an estimated performance loss of around 35% compared with standard modules in exchange for improved visual quality, demonstrating how new materials balance aesthetics with quantified energy outputs.
Urbanization and growth in new construction and premium retrofits
New construction and deep retrofit activity create natural decision points to adopt integrated envelope materials. BIPV is increasingly considered during roof replacement, façade refurbishment, and glazing upgrades where incremental integration costs can be optimized. Urban density favors solutions that generate electricity without additional footprint beyond the building envelope. Premium residential and commercial projects also use BIPV to differentiate architecture and support energy-performance outcomes.
Building Integrated Photovoltaic (BIPV) Market Challenges
BIPV projects often face higher upfront costs and more complex design coordination than conventional rooftop PV, especially for façade and glazing integration. Building-envelope integration requires alignment across architects, façade contractors, electrical teams, and permitting authorities, which can extend timelines and elevate execution risk. Product standardization remains uneven across geographies, and differences in local codes can add specification friction. These factors can slow adoption when project stakeholders prioritize short-cycle delivery.
- For instance, Onyx Solar's BIPV glass for the Atlassian headquarters in Sydney integrates 1,800 custom solar glass louvres, each with 28 monocrystalline cells producing 138 Wp per unit for a total of 247 kWp.
Supply-chain and installer readiness can also constrain deployment, particularly for specialized glazing and façade products that require trained partners and tailored installation methods. Performance expectations must be managed because orientation and shading vary widely across building designs, affecting yield predictability. Maintenance planning and warranty alignment across multiple contractors can become complicated without clear responsibility mapping. These issues can limit adoption outside premium projects and highly coordinated commercial builds.
Building Integrated Photovoltaic (BIPV) Market Trends and Opportunities
Integrated solar façades and PV glazing are gaining visibility as architects seek multifunctional building materials that combine aesthetics with energy generation. Transparent and semi-transparent solutions expand addressable surfaces beyond rooftops and support deployment in commercial buildings with large façade areas. Product modularity and customization options improve spec readiness for diverse building designs. These advances create opportunity for solution providers that can offer design support and predictable performance modeling.
- For instance, the Solaire residential tower in New York integrates a façade BIPV array using monocrystalline silicon wafers that achieved an energy payback time of 0.8 years when crediting the cladding it replaces, and 3.8 years under conventional wafer assumptions, demonstrating both architectural integration and quantified lifecycle efficiency.
Partnership-driven go-to-market models are also expanding, with collaboration between PV innovators, façade system providers, and large construction supply chains. Such partnerships improve access to project pipelines and reduce customer acquisition friction in construction-led procurement. Demand is also increasing for integrated solutions bundled with energy-management systems and building-performance analytics. This trend supports higher-value offerings that combine product, integration services, and long-term performance assurance.
Regional Insights
North America
North America accounted for 22.9% of the BIPV market in 2025, supported by stronger uptake in commercial buildings where sustainability targets and energy-resilience planning influence investment decisions. Developers increasingly evaluate envelope-integrated solar during roof replacements and high-performance retrofit cycles, particularly in premium office, retail, and institutional projects. Adoption is reinforced by the growing presence of green-building design firms, energy-service partners, and specialized installers. Overall traction remains strongest in commercial deployments, with selective penetration in higher-income residential segments.
Europe
Europe led the global BIPV market with a 40.9% share in 2025, driven by high green-building penetration and tighter policy pressure to improve building energy performance. Developers more frequently treat building envelopes as energy assets, supporting BIPV integration across roofs and façade systems in both new builds and deep retrofits. A mature ecosystem of architects, façade specialists, and product suppliers improves specification readiness and execution consistency. These conditions sustain broader adoption across commercial buildings and public-sector infrastructure.
Asia Pacific
Asia Pacific represented 26.1% of the market in 2025, supported by high construction activity in major cities and increasing adoption of energy-efficient building designs. Large commercial developments provide substantial roof and façade surface area, improving feasibility for integrated PV deployment. Regional manufacturing depth strengthens product availability across multiple PV formats and building-material configurations, supporting price-performance competitiveness. Growth is further reinforced by smart-city and green-infrastructure programs that prioritize integrated sustainability features.
Latin America
Latin America captured 5.4% of the BIPV market in 2025, reflecting selective adoption concentrated in premium commercial and institutional projects. In many markets, conventional rooftop PV remains the preferred option on cost and simplicity, limiting BIPV adoption outside design-led builds. However, flagship green-building developments and high-irradiance urban corridors support incremental demand for integrated roof and façade solutions. Penetration improves when BIPV is aligned with retrofit cycles and building-material replacement decisions.
Middle East & Africa
Middle East & Africa accounted for 4.7% of the market in 2025, with deployments concentrated in landmark commercial projects and high-visibility developments where aesthetics and sustainability positioning matter. High solar resource supports strong generation potential, but adoption remains constrained by higher solution costs, specialized installation needs, and limited standardization across projects. Market progress depends on deeper ecosystem development among façade contractors, designers, and qualified suppliers. Wider adoption is expected as integrated PV materials become more standardized and procurement becomes easier for mainstream projects.
Competitive Landscape
Competition in the Building Integrated Photovoltaic (BIPV) Market is driven by product differentiation across PV glass, façade-integrated systems, lightweight thin-film formats, and integrated roofing solutions. Market participants compete on efficiency, aesthetics, durability, and integration support for architects and façade contractors. Commercial success often depends on building-code compatibility, warranty strength, and the ability to deliver predictable performance through modeling and installation guidance. Partnerships with construction supply chains and design firms remain critical for scaling deployments.
AGC Inc. is positioned around building-glass capabilities that align with façade and glazing-led BIPV pathways. Product development and collaboration models that integrate PV functionality into architectural glass can reduce adoption barriers for designers seeking energy-generating envelopes. Building-material distribution strength and relationships with façade stakeholders can improve project specification and execution consistency. Such capabilities support participation in design-led commercial projects where performance, aesthetics, and compliance requirements converge.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- AGC Inc.
- SolarWindow Technologies, Inc.
- Hanergy Mobile Energy Holding Group Limited
- Heliatek GmbH
- Tesla Inc.
- Ascent Solar Technologies, Inc.
- Onyx Solar
- SoliTek UAB
- Mitrex Integrated Solar Technology Inc.
- ML System
- Dyesol
- SolTech Energy
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In October 2025, Mumbai-based Aelius Turbina announced its expansion into manufacturing BIPV products, including solar roof tiles, floor tiles, and facade panels, alongside plans to inaugurate a dedicated BIPV manufacturing facility in January 2026 to support growing demand for integrated solar building materials.
- In June 2025, Kameleon Solar partnered with India-based Nithin Sai Renewables Pvt. Ltd. to expand Kameleon’s BIPV solutions into the Indian market, with the collaboration focused on boosting deployment of integrated solar facades and other architecturally integrated PV products.
- In July 2024, LONGi Green Energy Technology Co. Ltd. formed a strategic partnership with Kingspan to collaborate on integrated BIPV and building-applied PV (BAPV) systems, combining LONGi’s high-efficiency solar technologies with Kingspan’s building envelope expertise to deliver tested solutions for net-zero energy buildings.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 14,627.57 million |
| Revenue forecast in 2032 | USD 43,378.27 million |
| Growth rate (CAGR) | 16.8% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Technology Outlook: Crystalline silicon, Thin-film, Others; By Application / Building Element Outlook: Roofs, Façades, Walls, Windows, Skylights, Shading systems; By End User Outlook: Residential, Commercial, Industrial |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | AGC Inc., SolarWindow Technologies, Inc., Hanergy Mobile Energy Holding Group Limited, Heliatek GmbH, Tesla Inc., Ascent Solar Technologies, Inc., Onyx Solar, SoliTek UAB, Mitrex Integrated Solar Technology Inc., ML System, Dyesol, SolTech Energy |
| No. of Pages | 328 |
Segmentation
By Technology
- Crystalline silicon
- Thin-film
- Others
By Application / Building Element
- Roofs
- Façades
- Walls
- Windows
- Skylights
- Shading systems
By End User
- Residential
- Commercial
- Industrial
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Building decarbonization mandates and energy-performance regulations
Stricter building codes and carbon-reduction requirements are compelling developers to integrate renewable energy solutions like BIPV into building envelopes, especially in urban areas where land is limited. These mandates support BIPV adoption as part of compliance with net-zero and near-zero energy building targets.
Rising commercial sustainability commitments and ESG-linked investment
Corporate sustainability goals and ESG frameworks are driving commercial property owners to adopt BIPV as a visible, measurable way to reduce operational emissions and enhance building value. This trend is particularly strong in offices, retail, and institutional buildings where energy performance is closely monitored.
Advances in PV building materials and improved architectural acceptance
Innovations in PV glass, façade modules, and lightweight solutions have improved the aesthetics, flexibility, and durability of BIPV products, making them more attractive to architects and developers. Enhanced integration methods and longer warranties are increasing confidence and accelerating market adoption.
Urbanization and growth in new construction and premium retrofits
The increase in new construction and deep retrofit projects, especially in urban and premium segments, creates natural opportunities for BIPV integration. BIPV is increasingly specified during roof replacements, façade refurbishments, and glazing upgrades, supporting market growth.
Partnership-driven go-to-market models and ecosystem development
Collaborations between PV innovators, façade system providers, and construction supply chains are improving access to project pipelines and reducing customer acquisition barriers. These partnerships enable bundled solutions that combine BIPV products with energy management and performance analytics, driving broader adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Building Integrated Photovoltaic (BIPV) Market in 2025 and its forecast for 2032?
What is the CAGR for the Building Integrated Photovoltaic (BIPV) Market during 2025–2032?
Which technology segment leads the Building Integrated Photovoltaic (BIPV) Market?
What are the key factors driving growth in the Building Integrated Photovoltaic (BIPV) Market?
Which companies are profiled in the Building Integrated Photovoltaic (BIPV) Market?
Which region leads the Building Integrated Photovoltaic (BIPV) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.3 By Technology
- 1.3.1 Crystalline silicon
- 1.3.2 Thin-film
- 1.3.3 Others
- 1.4 By Application / Building Element
- 1.4.1 Roofs
- 1.4.2 Façades
- 1.4.3 Walls
- 1.4.4 Windows
- 1.4.5 Skylights
- 1.4.6 Shading systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 14,627.57 million → 2032: USD 43,378.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Building Integrated Photovoltaics (BIPV) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Building Integrated Photovoltaics (BIPV) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Building Integrated Photovoltaics (BIPV) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Building Integrated Photovoltaics (BIPV) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Building Integrated Photovoltaics (BIPV) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Building Integrated Photovoltaics (BIPV) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Building Integrated Photovoltaics (BIPV) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Building Integrated Photovoltaics (BIPV) Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 14,627.57 million → 2032: USD 43,378.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Building Integrated Photovoltaics (BIPV) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Crystalline silicon
- 12.4.7.2 Thin-film
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application / Building Element - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Roofs
- 12.5.7.2 Façades
- 12.5.7.3 Walls
- 12.5.7.4 Windows
- 12.5.7.5 Skylights
- 12.5.7.6 Shading systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Building Integrated Photovoltaics (BIPV) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Building Integrated Photovoltaics (BIPV) Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Building Integrated Photovoltaics (BIPV) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Building Integrated Photovoltaics (BIPV) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AGC Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SolarWindow Technologies, Inc.
- 18.4 Hanergy Mobile Energy Holding Group Limited
- 18.5 Heliatek GmbH
- 18.6 Tesla Inc.
- 18.7 Ascent Solar Technologies, Inc.
- 18.8 Onyx Solar
- 18.9 SoliTek UAB
- 18.10 Mitrex Integrated Solar Technology Inc.
- 18.11 ML System
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

