
Ambulatory Cardiac Monitoring Market Overview:
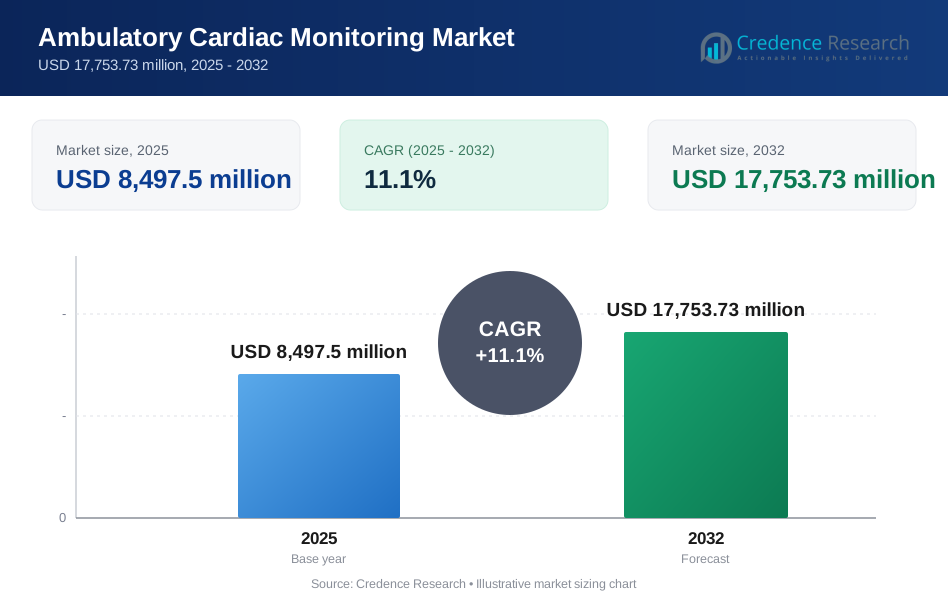
The Ambulatory Cardiac Monitoring Market is projected to grow from USD 8,497.5 million in 2025 to an estimated USD 17,753.73 million by 2032, with a compound annual growth rate (CAGR) of 11.1% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ambulatory Cardiac Monitoring Market Size 2024 | USD 8,497.5 million |
| Ambulatory Cardiac Monitoring Market, CAGR | 11.1% |
| Ambulatory Cardiac Monitoring Market Size 2032 | USD 17,753.73 million |
Ambulatory Cardiac Monitoring Market Insights:
- Rising arrhythmia prevalence, increasing use of wearable and patch-based devices, and wider deployment of remote cardiac monitoring platforms continue to strengthen market momentum.
- Market growth faces restraints linked to data-management complexity, integration issues across clinical systems, and variable reimbursement support in developing regions.
- North America leads the market due to strong digital health adoption and advanced cardiac care infrastructure, while Europe follows with structured cardiac monitoring programs and rapid acceptance of connected tools.
- Asia-Pacific emerges as the fastest-growing region, supported by expanding healthcare access, rising awareness of rhythm disorders, and strong interest in remote monitoring solutions.

Ambulatory Cardiac Monitoring Market Drivers
Rising Prevalence of Cardiac Disorders and Growing Demand for Continuous Monitoring
The Ambulatory Cardiac Monitoring Market expands due to rising cases of arrhythmias and cardiovascular risks across all age groups. Healthcare providers prefer real-time tracking because it improves early diagnosis for many patients. Wearable monitors support longer monitoring cycles to capture intermittent symptoms. Hospitals adopt these tools to reduce delayed detection of rhythm abnormalities. Patients seek convenient monitoring options that fit daily routines. Physicians rely on extended data logs to improve diagnostic accuracy. Digital systems help shorten decision timelines for treatment planning. Awareness of preventive cardiac care strengthens adoption across major care settings. Broader use of remote tools encourages steady demand across regions.
Technological Advancements in Wearable and Patch-Based Devices
Innovations in sensor accuracy, battery life, and data transmission strengthen device relevance across modern care pathways. Compact patch monitors help patients remain active while maintaining uninterrupted data capture. AI-enabled algorithms improve detection of subtle rhythm variations. Many care teams integrate cloud platforms for faster data review. It improves physician workflow by reducing manual review burdens. Device makers design flexible wearables to fit diverse patient needs. Higher comfort levels support stronger patient compliance during long-term monitoring cycles. Wireless connectivity ensures stable data flow across home and clinic environments. Growing trust in digital systems boosts adoption among clinicians.
- For instance, Medtronic’s SEEQ™ Mobile Cardiac Telemetry system enabled continuous single-lead ECG monitoring for up to 30 days, supported by its zLink™ cellular transmitter for near-real-time data delivery. The device used advanced arrhythmia-detection algorithms and relied on sequential 7.5-day wearable sensors to achieve a full monitoring cycle before being discontinued in 2018 as Medtronic shifted focus to its Reveal LINQ™ insertable monitors.
Shift Toward Outpatient Care and Remote Cardiac Management
Healthcare systems promote early detection and outpatient monitoring to reduce emergency visits. Remote platforms help clinics supervise at-risk patients without constant in-person appointments. Many hospitals expand remote cardiac programs to reduce infrastructure pressure. Device connectivity supports smooth data transfer to care teams. It improves patient follow-up processes by offering continuous visibility into cardiac patterns. Wearable tools reduce the need for frequent hospital stays. Greater focus on home-based care encourages broader market penetration. Remote workflows help clinicians manage larger patient volumes efficiently. Supportive reimbursement frameworks strengthen use of monitoring tools.
Growing Focus on Patient Comfort, Compliance, and Long-Term Monitoring Needs
Manufacturers design devices that improve comfort through lightweight formats and skin-friendly materials. Long-wear patches encourage consistent use among patients with recurring symptoms. Continuous monitoring supports better management of irregular heart rhythms. Clinicians prefer devices that minimize disruptions while capturing high-quality data. It helps teams analyze daily activity patterns linked to patient symptoms. Improved usability reduces patient dropout rates during extended monitoring cycles. Contactless and wireless features promote seamless adoption in outpatient settings. Healthcare facilities expand long-duration monitoring programs to improve diagnostic yield. Higher comfort standards strengthen device preference among elderly and chronic patients.
- For instance, Abbott’s Confirm Rx™ insertable cardiac monitor enhances patient compliance through Bluetooth-enabled smartphone connectivity, with real-world studies showing that 97% of patients register the myMerlin™ app and 92% successfully transmit data. The device supports frequent connectivity with an average of 4.7 transmissions per week, while symptomatic events reach clinicians within a median of 2.9 minutes, supported by SharpSense™ technology that reduces false detections by 97%.
Ambulatory Cardiac Monitoring Market Trends
Growing Integration of AI, Predictive Analytics, and Automated Rhythm Interpretation Tools
AI-driven tools reshape the Ambulatory Cardiac Monitoring Market by improving speed and precision in rhythm detection. Predictive models help identify early signs of potential cardiac events. Automated reporting reduces manual work for clinicians. Cloud-based dashboards organize large data streams for faster review. It enhances diagnostic confidence across diverse patient groups. Software tools simplify long-term trend analysis. Machine learning supports adaptive detection across changing heart rhythms. Healthcare providers invest in AI-enabled systems to refine workflow efficiency. Adoption rises as algorithms improve accuracy and reduce false alerts.
Expansion of Cloud Connectivity, Telecardiology Services, and Cross-Platform Data Exchange
Cloud integration supports secure transmission of continuous data to remote specialists. Telecardiology centers rely on connected devices to supervise patients outside clinical boundaries. Interoperable platforms link monitors with electronic health records for smoother coordination. It strengthens collaboration between cardiologists and primary-care providers. Faster data sharing supports timely intervention for high-risk patients. Cloud tools simplify device management workflows across different hospital units. Remote uploads reduce patient visits for data retrieval. Wider rollout of telehealth policies enhances adoption of digital monitoring. Digital ecosystems expand to support large case volumes.
- For instance, GE Healthcare enables cloud-based ECG workflow management through its MUSE™ system, allowing remote specialists to review diagnostic events within minutes of transmission.
Increased Adoption of Patch Monitors, Adhesive Sensors, and Cable-Free Diagnostic Tools
Demand shifts toward lightweight monitors that replace traditional Holter devices. Adhesive sensors help patients maintain normal routines while collecting high-resolution data. Cable-free formats improve comfort during long monitoring periods. It helps reduce device movement and signal disruptions during daily activities. Many hospitals use patch monitors for multi-day analysis. Device makers introduce flexible shapes to suit varied patient profiles. Rechargeable designs extend usability across longer cycles. Adoption rises in outpatient clinics due to ease of application. Wearable innovation fuels stronger consumer acceptance.
- For instance, Philips supports extended-wear patch monitoring through its BioTel Heart platform, which provides continuous multi-day ECG collection with streamlined cloud upload.
Growing Use of Mobile Health Platforms, App-Based Review Tools, and Patient Engagement Features
Smartphone apps help patients track symptoms alongside monitoring data. Integrated dashboards support patient involvement in individual care plans. Many platforms display simplified rhythm summaries for patient awareness. It improves communication between patients and clinicians during follow-ups. App alerts notify users about device status or irregular patterns. Remote messaging supports faster clinical response for urgent cases. Adoption of user-friendly interfaces strengthens patient compliance. Healthcare providers integrate apps into monitoring programs for better engagement. Digital tools encourage proactive cardiac management across age groups.
Ambulatory Cardiac Monitoring Market Challenges Analysis
Complex Data Management, Interoperability Issues, and Diagnostic Interpretation Burden
Large data volumes from long-term monitoring create challenges for care providers and diagnostic teams. Many clinics lack streamlined systems to process continuous rhythm data. It slows decision-making when specialists handle many cases at once. Variations in device formats complicate smooth integration with hospital systems. Interoperability gaps delay complete access to patient histories. Some clinics face limited staff capacity for manual report validation. False alerts disrupt workflow efficiency during peak patient loads. System incompatibility restricts efficient scaling of remote monitoring services. Data overload pressures institutions with limited digital infrastructure.
Cost Constraints, Reimbursement Variability, and Limited Awareness in Emerging Regions
High device prices reduce adoption among low-income groups and small clinics. Limited reimbursement support in some regions restricts access to advanced monitors. It creates slower uptake in markets with budget-sensitive healthcare systems. Many patients lack awareness about early detection benefits. Infrastructure gaps in developing nations limit telecardiology expansion. Supply constraints delay adoption in rural areas. Training gaps restrict efficient device use among clinicians. Variability in regulatory pathways slows market entry for new models. Slow digital adoption limits monitoring penetration in underserved regions.
Ambulatory Cardiac Monitoring Market Opportunities
Growing Demand for Home-Based Cardiac Care, Early Diagnosis Initiatives, and Wearable Expansion
Home-based cardiac programs gain traction due to demand for convenient monitoring. Population aging increases the need for continuous tracking tools. Early diagnosis programs encourage healthcare systems to adopt modern monitors. The Ambulatory Cardiac Monitoring Market benefits from growing acceptance of wearable formats. It strengthens outpatient workflows and reduces hospital congestion. Miniaturized sensors open new applications across primary care settings. Longer battery life supports extended monitoring plans. Awareness campaigns promote proactive heart health management. Rising preference for non-invasive tools widens commercial potential.
Integration of AI-Based Platforms, Remote Clinics, and Cross-Border Telecardiology Networks
AI-enhanced systems create new possibilities for automated diagnosis. Remote clinics expand their reach through telecardiology networks. It supports faster specialist access in underserved regions. Cloud infrastructure improves real-time collaboration across global care teams. Device makers invest in analytics tools that improve detection precision. Hospitals adopt scalable platforms to manage larger patient volumes. Digital ecosystems support faster care delivery for chronic patients. Many markets explore regional telehealth partnerships to strengthen cardiac services. Integration of virtual monitoring models unlocks new service-based revenue streams.
Ambulatory Cardiac Monitoring Market Segmentation Analysis:
By Device Type
The Ambulatory Cardiac Monitoring Market strengthens adoption across varied device types that address short-term and long-term rhythm assessment needs. Holter monitors remain widely used for continuous recordings over 24 to 48 hours. Event monitors support patients with infrequent symptoms and help clinicians capture intermittent episodes. Mobile Cardiac Telemetry devices gain momentum for real-time detection due to their automated alerts. Implantable Loop Recorders support long-duration tracking for unexplained symptoms. Patch-based monitors improve patient comfort during extended wear periods. ECG wearables support routine screening and remote supervision. Each device type advances clinical decision workflows.
- For instance, GE HealthCare’s MUSE™ cardiology information system supports extended Holter workflows and is deployed in 90% of top U.S. cardiology hospitals, enabling seamless integration with GE’s CardioDay™ Holter recorders and third-party wearables such as the Zio patch. The platform also improves operational efficiency by reducing ECG capture-to-billing time from 45 minutes to about 10 minutes in high-volume facilities.
By Technology
Technology advances help the market expand across monitoring models that enhance accuracy and connectivity. Lead-based systems remain critical for high-fidelity rhythm capture across diverse clinical settings. Wireless and connected devices support remote data transfer and improve diagnostic speed. AI-based diagnostic tools help reduce manual interpretation workloads and strengthen rhythm analysis. Cloud platforms streamline storage, access, and specialist collaboration. Traditional non-connected devices retain use in low-resource settings where digital systems remain limited. Each technology tier supports different workflow requirements across healthcare facilities.
By Application
The market supports a broad set of cardiac conditions that require continuous or event-based assessment. Atrial fibrillation remains a leading application due to its rising prevalence across aging populations. Ventricular arrhythmia monitoring improves risk evaluation for high-severity episodes. Bradycardia and tachycardia tracking help clinicians evaluate rate abnormalities. Conduction disorder monitoring improves understanding of electrical delays. Syncope assessment benefits from extended deployment tools. Post-operative monitoring supports rhythm evaluation after cardiac procedures. Other applications address general rhythm irregularities.
By End-User
The market serves multiple healthcare environments that rely on remote and in-clinic monitoring systems. Hospitals and cardiology clinics lead adoption due to strong diagnostic infrastructure. Ambulatory surgical centers use monitoring tools for short-term evaluations. Diagnostic imaging centers integrate these systems to support multidisciplinary workflows. Home healthcare settings gain relevance as remote monitoring expands. Individual users adopt wearable formats for personal tracking and preventive oversight. Each end-user category drives unique operational demands.
- For instance, Nihon Kohden Corporation supports hospital telemetry programs through its Life Scope monitoring suite, which provides continuous arrhythmia analysis across inpatient units.
Segmentation:
By Device Type
- Holter Monitors
- Event Monitors
- Mobile Cardiac Telemetry (MCT) Devices
- Implantable Loop Recorders (ILRs)
- Patch-Based Monitors
- ECG Devices / Wearable ECG Monitors
By Technology
- Lead-Based Monitoring Devices
- Wireless and Connected Devices
- AI-Based / Smart Diagnostic Devices
- Cloud-Based Monitoring Platforms
- Traditional (Non-Connected) Devices
By Application
- Atrial Fibrillation
- Ventricular Arrhythmia
- Bradycardia
- Tachycardia
- Conduction Disorders
- Syncope
- Post-Operative Monitoring
- Others
By End-User
- Hospitals & Cardiology Clinics
- Ambulatory Surgical Centers
- Diagnostic Imaging Centers
- Home Healthcare Settings
- Individual Users
By Region
- North America (U.S., Canada)
- Europe (UK, Germany, France, Italy, Spain, Rest of Europe)
- Asia-Pacific (China, Japan, India, South Korea, Australia, Rest of APAC)
- Latin America (Brazil, Mexico, Argentina, Rest of LATAM)
- Middle East & Africa (GCC Countries, South Africa, Rest of MEA)
Regional Analysis:
North America holds the largest share of the Ambulatory Cardiac Monitoring Market, contributing around 38% of global revenue due to strong adoption of digital cardiac tools and advanced reimbursement systems. Cardiologists in the region use connected monitoring platforms widely to support early rhythm detection. High prevalence of atrial fibrillation strengthens demand for continuous monitoring. The region benefits from an active ecosystem of device makers and AI developers. It also gains traction from home-based care programs. Strong clinical infrastructure supports expanded deployment of wearable and telemetry systems.
Europe accounts for roughly 28% of global share and continues to expand its monitoring base with structured cardiac management programs. The Ambulatory Cardiac Monitoring Market grows in this region due to strong clinical guidelines for rhythm evaluation. Healthcare providers adopt patch-based monitors to improve patient comfort and compliance. Many countries invest in digital health platforms to support remote cardiac supervision. Regulatory support encourages wider use of AI-enabled rhythm tools. Hospitals drive strong adoption of MCT devices for real-time assessment.
Asia-Pacific holds close to 23% of the market and grows at a faster pace due to rising cardiac risk, expanding healthcare access, and increasing investment in remote monitoring. Demand rises in China and India due to large patient populations and widening use of wearable ECG tools. It receives strong momentum from urban hospitals upgrading cardiac diagnostics. Japan and South Korea lead early adoption of AI-based monitoring. Southeast Asian markets expand use of cloud platforms due to telehealth surge. Growing awareness of preventive cardiac care strengthens long-term potential across developing regions.
Key Player Analysis:
- Abbott Laboratories
- Medtronic plc
- Boston Scientific Corporation
- GE Healthcare
- Koninklijke Philips N.V.
- iRhythm Technologies Inc.
- ZOLL Medical Corporation
- Biotronik SE & Co. KG
- Nihon Kohden Corporation
- Hill-Rom Services, Inc.
Competitive Analysis:
The Ambulatory Cardiac Monitoring Market features strong competition among global manufacturers, digital health firms, and AI-focused innovators. Companies invest in advanced algorithms, multi-lead tools, and predictive analytic systems to raise diagnostic precision. Major players expand product lines to cover Holter, event, patch, and telemetry formats. It encourages firms to focus on comfort, data quality, and long-duration performance. Partnerships with hospitals strengthen deployment of cloud and AI-based platforms. Firms also compete on device size, battery life, and reporting speed. New entrants target wearable ECG tools to meet the growing demand for home-based cardiac tracking. Established leaders defend market share through regulatory approvals, regional expansion, and integration of remote monitoring services.
Recent Developments:
- In January 2026, CardioOne launched CardioOne Connect, an integrated care management and monitoring platform incorporating the CardioDiagnostics acquisition from April 2025. The platform enables chronic care management, remote patient monitoring, and cardiac event monitoring for arrhythmia detection in value-based cardiology programs.
- In November 2025, Boston Scientific Corporation announced a partnership with Epic to integrate its ambulatory cardiac monitoring and diagnostics services with Epic's Aura electronic health record platform.
- In February 2025, in CB Scientific Inc. (CBSC), the company formally launched its next-generation MyCardia AT cardiac event monitor in partnership with contract manufacturer Datrix, LLC, targeting international distribution in SE Asia, Hong Kong, and Macau. The device integrates with their AWS Cloud-based MyCardia portal and iOS/Android apps to streamline remote cardiac monitoring and optimize global user experience.
Report Coverage:
The research report offers an in-depth analysis based on Device Type, Technology, Application, and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising use of remote monitoring platforms will strengthen long-term adoption across clinical and home settings.
- Wearable ECG tools will gain wider preference due to improved comfort, accuracy, and patient compliance.
- AI-driven rhythm interpretation will enhance diagnostic precision and reduce review time for clinicians.
- Cloud-based systems will support unified data access and expand telecardiology programs.
- Hospitals will upgrade monitoring workflows to support real-time evaluation for high-risk patients.
- Patch-based devices will experience stronger uptake as long-duration monitoring becomes standard.
- Integration of mobile health applications will support broader patient engagement and follow-up.
- Emerging markets will expand adoption due to rising awareness of rhythm disorders.
- Collaborations between device makers and digital health firms will accelerate platform innovation.
- Regulatory support for digital diagnostics will encourage faster deployment of advanced monitoring technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiac Disorders and Demand for Continuous Monitoring
Increasing cases of arrhythmias and cardiovascular risks across all age groups are driving healthcare providers to adopt real-time and continuous cardiac monitoring solutions, enabling earlier diagnosis and improved patient outcomes.
Technological Advancements in Wearable and Patch-Based Devices
Innovations in sensor accuracy, battery life, and wireless connectivity have made wearable and patch-based monitors more comfortable and reliable, supporting longer monitoring cycles and higher patient compliance.
Shift Toward Outpatient Care and Remote Cardiac Management
Healthcare systems are prioritizing early detection and outpatient monitoring to reduce hospital admissions and infrastructure burden, fueling the adoption of remote cardiac monitoring platforms and telecardiology services.
Integration of AI and Predictive Analytics
AI-driven rhythm interpretation and predictive analytics are enhancing diagnostic precision, reducing manual review time for clinicians, and enabling faster intervention for high-risk patients.
Expansion of Home-Based Cardiac Care and Patient Engagement
Growing acceptance of home-based monitoring, supported by mobile health apps and cloud connectivity, is empowering patients to participate in their own care and broadening the market's reach into non-traditional healthcare settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ambulatory Cardiac Monitoring Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ambulatory Cardiac Monitoring Market projected to grow between 2025 and 2032?
Which Ambulatory Cardiac Monitoring Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Ambulatory Cardiac Monitoring Market?
Who are the leading companies in the Ambulatory Cardiac Monitoring Market?
Which region commanded the largest share of the Ambulatory Cardiac Monitoring Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals & Cardiology Clinics
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Diagnostic Imaging Centers
- 1.2.4 Home Healthcare Settings
- 1.2.5 Individual Users
- 1.3 By Technology
- 1.3.1 Lead-Based Monitoring Devices
- 1.3.2 Wireless and Connected Devices
- 1.3.3 AI-Based / Smart Diagnostic Devices
- 1.3.4 Cloud-Based Monitoring Platforms
- 1.3.5 Traditional (Non-Connected) Devices
- 1.4 By Application
- 1.4.1 Atrial Fibrillation
- 1.4.2 Ventricular Arrhythmia
- 1.4.3 Bradycardia
- 1.4.4 Tachycardia
- 1.4.5 Conduction Disorders
- 1.4.6 Syncope
- 1.4.7 Post-Operative Monitoring
- 1.4.8 Others
- 1.5 By Device Type
- 1.5.1 Holter Monitors
- 1.5.2 Event Monitors
- 1.5.3 Mobile Cardiac Telemetry (MCT) Devices
- 1.5.4 Implantable Loop Recorders (ILRs)
- 1.5.5 Patch-Based Monitors
- 1.5.6 ECG Devices / Wearable ECG Monitors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 8,497.5 million → 2032: USD 17,753.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ambulatory Cardiac Monitoring Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ambulatory Cardiac Monitoring Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ambulatory Cardiac Monitoring Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ambulatory Cardiac Monitoring Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ambulatory Cardiac Monitoring Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ambulatory Cardiac Monitoring Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ambulatory Cardiac Monitoring Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ambulatory Cardiac Monitoring Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 8,497.5 million → 2032: USD 17,753.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ambulatory Cardiac Monitoring Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals & Cardiology Clinics
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Diagnostic Imaging Centers
- 12.3.7.4 Home Healthcare Settings
- 12.3.7.5 Individual Users
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lead-Based Monitoring Devices
- 12.4.7.2 Wireless and Connected Devices
- 12.4.7.3 AI-Based / Smart Diagnostic Devices
- 12.4.7.4 Cloud-Based Monitoring Platforms
- 12.4.7.5 Traditional (Non-Connected) Devices
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Atrial Fibrillation
- 12.5.7.2 Ventricular Arrhythmia
- 12.5.7.3 Bradycardia
- 12.5.7.4 Tachycardia
- 12.5.7.5 Conduction Disorders
- 12.5.7.6 Syncope
- 12.5.7.7 Post-Operative Monitoring
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Device Type - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Holter Monitors
- 12.6.7.2 Event Monitors
- 12.6.7.3 Mobile Cardiac Telemetry (MCT) Devices
- 12.6.7.4 Implantable Loop Recorders (ILRs)
- 12.6.7.5 Patch-Based Monitors
- 12.6.7.6 ECG Devices / Wearable ECG Monitors
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ambulatory Cardiac Monitoring End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ambulatory Cardiac Monitoring Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ambulatory Cardiac Monitoring Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ambulatory Cardiac Monitoring Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott Laboratories
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic plc
- 18.4 Boston Scientific Corporation
- 18.5 GE Healthcare
- 18.6 Koninklijke Philips N.V.
- 18.7 iRhythm Technologies Inc.
- 18.8 ZOLL Medical Corporation
- 18.9 Biotronik SE & Co. KG
- 18.10 Nihon Kohden Corporation
- 18.11 Hill-Rom Services, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

