
Market Overview:
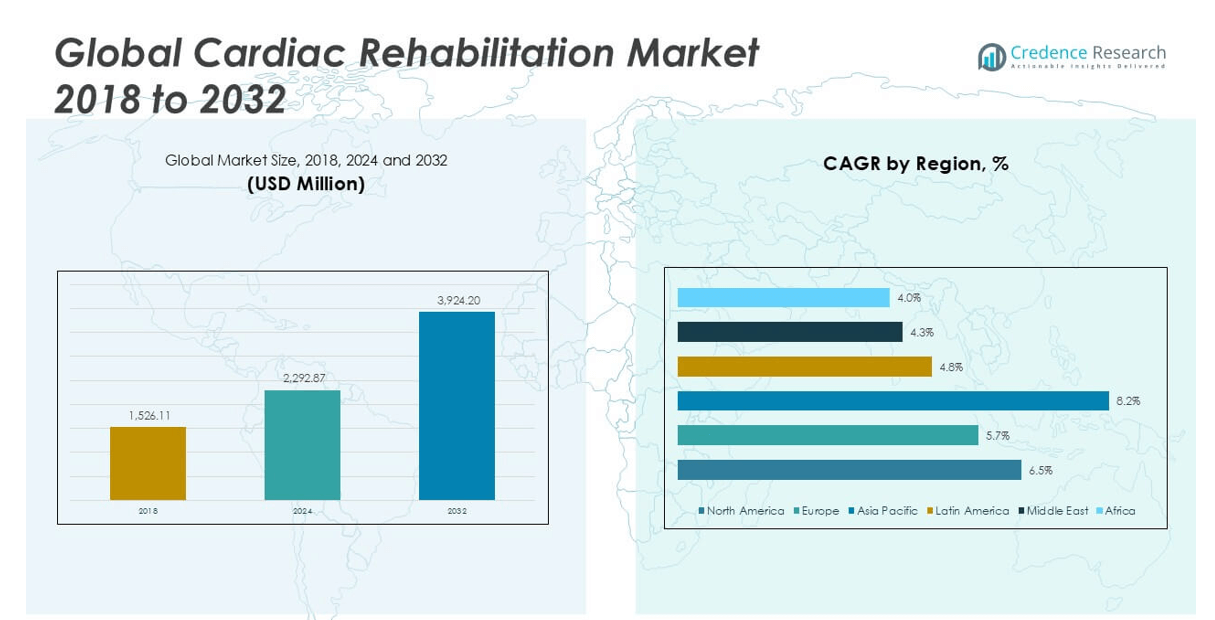
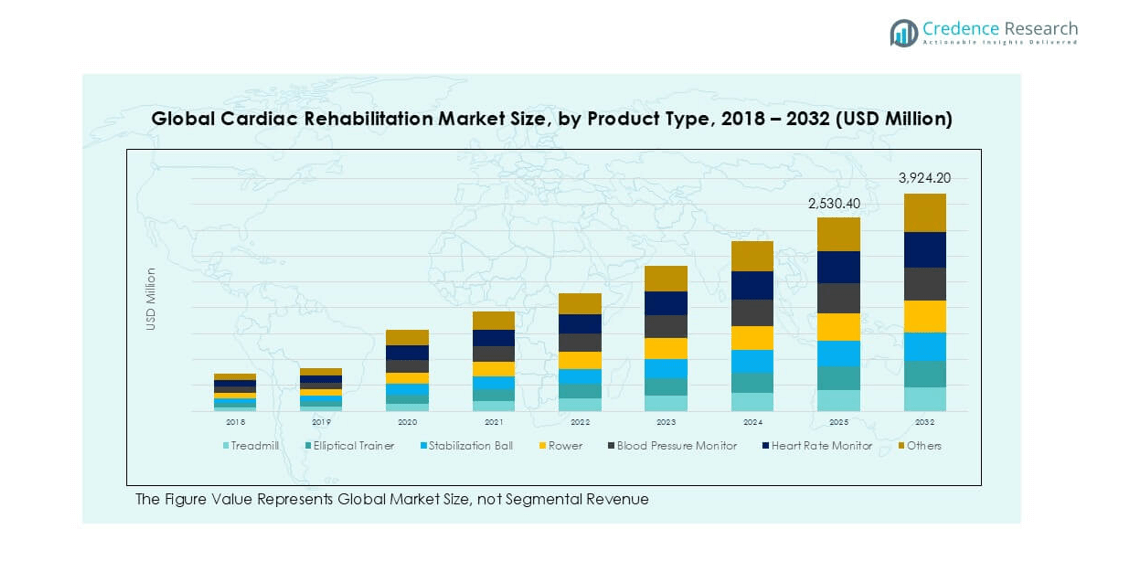
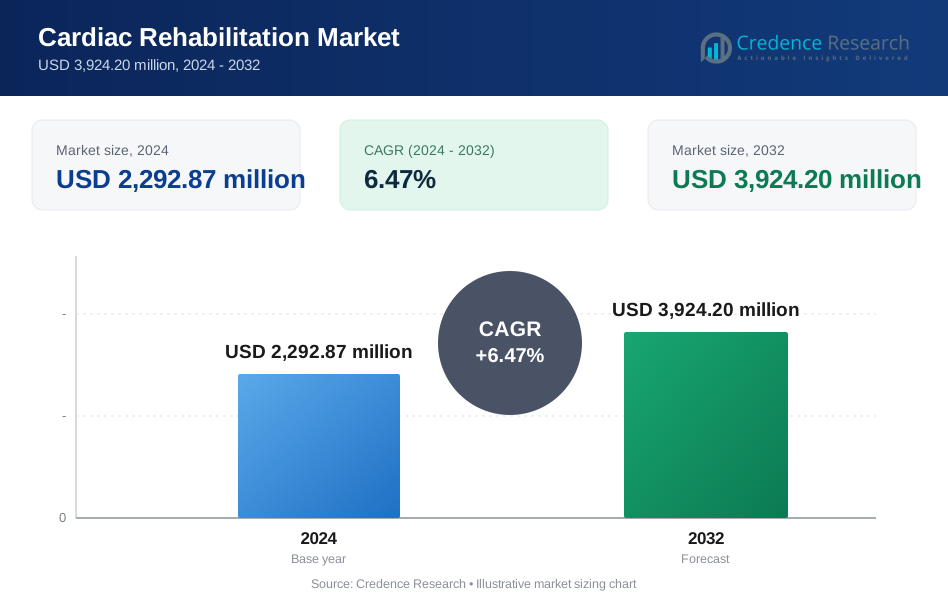
The Cardiac Rehabilitation market size was valued at USD 1,526.11 million in 2018, increased to USD 2,292.87 million in 2024, and is anticipated to reach USD 3,924.20 million by 2032, at a CAGR of 6.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cardiac Rehabilitation Market Size 2024 | USD 2,292.87 million |
| Cardiac Rehabilitation Market, CAGR | 6.47% |
| Cardiac Rehabilitation Market Size 2032 | USD 3,924.20 million |
The cardiac rehabilitation market is led by prominent players such as Philips Healthcare, Medtronic PLC, GE Healthcare, LivaNova PLC, Baxter International Inc., and BioTelemetry, Inc., all of which offer advanced cardiac monitoring systems, rehabilitation equipment, and integrated care solutions. These companies maintain their competitive edge through innovation, strategic collaborations, and global reach. North America emerged as the leading region in 2024, capturing 42.3% of the global market share, driven by high healthcare expenditure, favorable reimbursement policies, and widespread adoption of technologically advanced rehabilitation programs. Asia Pacific, with a rapidly growing patient base and rising healthcare investments, represents the fastest-growing regional market.
Market Insights
- The cardiac rehabilitation market was valued at USD 2,292.87 million in 2024 and is projected to reach USD 3,924.20 million by 2032, growing at a CAGR of 6.47% during the forecast period.
- The market is primarily driven by the rising prevalence of cardiovascular diseases, aging populations, and growing awareness about the benefits of cardiac rehabilitation in preventing recurrent cardiac events.
- Technological advancements such as tele-rehabilitation and wearable health monitoring devices are trending, enabling home-based and hybrid cardiac care solutions to gain traction globally.
- Leading players like Philips Healthcare, Medtronic, and GE Healthcare dominate the market through strategic partnerships, diversified portfolios, and geographic expansion; treadmill remains the dominant product type, while hospitals and clinics are the key end users.
- Regionally, North America leads with a 42.3% share, followed by Europe (28.2%) and Asia Pacific (20.2%); however, limited infrastructure in low-income regions and low patient adherence rates pose ongoing restraints.
Market Segmentation Analysis:
By Product Type
The Treadmill segment held the largest share in the cardiac rehabilitation market by product type, accounting for a significant portion of the revenue in 2024. Treadmills are widely used in rehabilitation programs due to their effectiveness in controlled cardiovascular training, ease of monitoring patient progress, and adaptability to various fitness levels. The increasing adoption of technologically advanced treadmills with real-time heart rate monitoring and connectivity features is further driving segment growth. Rising awareness about physical activity in cardiac recovery and the incorporation of treadmills in both clinical and home-based settings contribute to their dominant market share.
- For instance, Life Fitness introduced the Integrity+ Cardio series in 2023, featuring a 24-inch console and Wi-Fi/Bluetooth integration that connects with over 50 third-party rehab and fitness apps used in over 2,000 rehabilitation facilities worldwide.
By Indication
Coronary Artery Disease (CAD) emerged as the leading indication segment, capturing the highest revenue share in 2024. The high prevalence of CAD globally, combined with its role as a primary cause of cardiovascular morbidity, has resulted in its dominance. The increasing number of lifestyle-related risk factors, such as obesity, diabetes, and smoking, continues to fuel demand for structured rehabilitation programs. Cardiac rehab for CAD patients improves cardiovascular function and reduces hospital readmissions, which makes it a key therapeutic focus. Supportive guidelines and reimbursement policies for CAD rehabilitation further boost segment expansion.
- For instance, Cleveland Clinic reported that out of 3,128 CAD patients enrolled in its cardiac rehab program in 2022, 1,972 completed all 36 prescribed sessions, resulting in a 22% reduction in readmission rates within six months.
By End User
Hospitals and Clinics represented the largest end-user segment in 2024, driven by their integrated care infrastructure, skilled personnel, and advanced diagnostic capabilities. These facilities offer comprehensive cardiac rehabilitation programs that encompass physical therapy, nutritional counseling, and psychological support. The segment benefits from the growing number of cardiovascular procedures and hospitalizations, necessitating post-discharge rehabilitation. Additionally, government initiatives and insurance coverage for in-hospital rehab services have bolstered demand. While homecare is gaining traction due to convenience and tele-rehab technologies, hospitals remain the primary choice for supervised and intensive cardiac recovery programs.
Market Overview
Rising Prevalence of Cardiovascular Diseases (CVDs)
The increasing incidence of cardiovascular diseases such as coronary artery disease, myocardial infarction, and heart failure is a primary driver for the cardiac rehabilitation market. As sedentary lifestyles, obesity, smoking, and diabetes continue to rise globally, the demand for structured rehabilitation programs has surged. Cardiac rehabilitation has proven effective in reducing mortality rates, improving quality of life, and preventing disease recurrence. This growing burden of CVDs is pushing healthcare providers and policymakers to emphasize secondary prevention, thus driving widespread adoption of cardiac rehab programs across healthcare settings.
- For instance, the American Heart Association partnered with Apple in 2021 to track cardiovascular health using Apple Watch, resulting in over 60,000 users actively participating in fitness and recovery challenges tied to cardiac health across 40 U.S. states.
Favorable Reimbursement Policies and Government Initiatives
Supportive reimbursement frameworks, particularly in developed regions like North America and Europe, are significantly boosting market growth. Public health authorities and insurance providers increasingly recognize the cost-effectiveness of cardiac rehabilitation in reducing long-term hospital readmissions and enhancing patient recovery. Government-funded programs and mandates promoting preventive healthcare have led to expanded access to rehab services. These financial incentives not only encourage patients to enroll in rehabilitation programs but also motivate healthcare providers to offer integrated cardiac care, contributing to consistent market expansion.
- For instance, in 2023, the U.S. Centers for Medicare & Medicaid Services (CMS) reimbursed up to 72 rehabilitation sessions per patient under its Comprehensive Cardiac Rehabilitation program, covering over 1.4 million eligible beneficiaries across the country.
Advancements in Tele-rehabilitation and Remote Monitoring Technologies
The integration of digital health technologies, such as tele-rehabilitation platforms and wearable health monitors, has revolutionized the cardiac rehabilitation landscape. These innovations enable remote patient monitoring, virtual consultations, and personalized therapy plans, making cardiac rehab more accessible, especially in rural or underserved regions. Post-pandemic demand for home-based care has accelerated the adoption of these tools, allowing patients to participate in structured programs without visiting healthcare facilities. This technological evolution enhances patient engagement, compliance, and clinical outcomes, thereby fueling growth in the global cardiac rehabilitation market.
Key Trends & Opportunities
Shift Toward Home-based and Hybrid Rehabilitation Models
A notable trend in the cardiac rehabilitation market is the transition from traditional, facility-based models to home-based and hybrid approaches. Driven by patient preference for convenience, reduced mobility in elderly populations, and the impact of COVID-19, healthcare systems are investing in hybrid programs that combine virtual and in-person care. This shift offers opportunities for technology providers, app developers, and wearable device manufacturers to collaborate with healthcare institutions. The trend supports broader access to rehab services and aligns with value-based care models aimed at long-term patient wellness.
- For instance, Kaiser Permanente launched a home-based cardiac rehab model in 2021 that enrolled over 3,400 patients across California, achieving a completion rate of 77% compared to 54% in traditional clinic-based programs.
Expansion into Emerging Markets
Emerging economies in Asia-Pacific, Latin America, and the Middle East present significant growth opportunities due to the rising burden of CVDs and improving healthcare infrastructure. Increasing public health awareness, urbanization, and economic development are pushing governments to invest in preventive healthcare and chronic disease management. Multinational healthcare providers and medical device companies are eyeing these regions for strategic expansion. As affordability improves and digital health technologies penetrate new markets, the cardiac rehabilitation sector stands to benefit from higher patient volumes and diversified revenue streams.
- For instance, Medtronic established its first regional cardiac care center in Hyderabad, India, in 2022, training over 500 cardiologists and deploying 1,200 remote patient monitoring devices in its first year to support cardiac rehab accessibility.
Key Challenges
Limited Access in Low- and Middle-Income Countries
Despite its proven benefits, cardiac rehabilitation remains underutilized in many low- and middle-income countries due to inadequate infrastructure, limited awareness, and high out-of-pocket costs. Many healthcare systems in these regions prioritize acute care over long-term recovery programs, leading to poor implementation of rehabilitation services. Additionally, cultural stigmas and logistical barriers prevent widespread participation. This access gap not only limits market growth but also underscores the need for global initiatives to make cardiac rehab more affordable and scalable in resource-constrained settings.
Patient Adherence and Dropout Rates
Maintaining patient adherence throughout the rehabilitation process is a persistent challenge. Factors such as lack of motivation, time constraints, transportation difficulties, and insufficient family support often lead to high dropout rates. Even with home-based programs, sustaining engagement over the long term requires structured follow-ups and behavioral interventions. Healthcare providers struggle to personalize rehab plans at scale, which affects patient retention and the overall effectiveness of treatment. Improving adherence remains critical to maximizing outcomes and realizing the full market potential of cardiac rehabilitation services.
Regional Analysis
North America
North America held the largest share in the global cardiac rehabilitation market in 2024, accounting for approximately 42.3% of the total market, with a valuation of USD 969.69 million, up from USD 652.33 million in 2018. The region is projected to reach USD 1,664.31 million by 2032, registering a CAGR of 6.5% during the forecast period. The high adoption rate of advanced medical technologies, favorable reimbursement policies, and a well-established healthcare infrastructure contribute to North America’s dominance. Moreover, the rising prevalence of cardiovascular diseases and lifestyle-related health conditions continues to fuel the demand for cardiac rehabilitation services.
Europe
Europe accounted for approximately 28.2% of the global cardiac rehabilitation market in 2024, with a market size of USD 647.10 million, rising from USD 446.31 million in 2018. The market is expected to reach USD 1,044.71 million by 2032, growing at a CAGR of 5.7%. The growth is driven by increasing government focus on preventive healthcare, aging population, and improved access to rehabilitation services across countries such as Germany, the UK, and France. Europe’s healthcare systems support cardiac rehab integration into post-surgical recovery protocols, encouraging broader participation and investment in facility-based and hybrid rehabilitation models.
Asia Pacific
Asia Pacific is emerging as the fastest-growing region in the cardiac rehabilitation market, expanding at a CAGR of 8.2%. The market size increased from USD 284.37 million in 2018 to USD 464.25 million in 2024, and is projected to reach USD 903.02 million by 2032, capturing approximately 20.2% of the global market share in 2024. Rapid urbanization, growing prevalence of cardiovascular diseases, and increasing healthcare investments across China, India, and Southeast Asia are key growth drivers. Rising awareness of rehabilitation benefits and the expansion of tele-rehabilitation programs are also contributing to the region’s accelerated market expansion.
Latin America
Latin America held a modest share of around 4.6% of the global cardiac rehabilitation market in 2024, valued at USD 104.65 million, up from USD 70.55 million in 2018. The market is forecasted to reach USD 158.08 million by 2032, growing at a CAGR of 4.8%. Growth in this region is supported by the increasing incidence of non-communicable diseases, improvements in healthcare accessibility, and a rising middle-class population. Countries like Brazil and Mexico are making strides in integrating rehabilitation programs within public health systems. However, limited infrastructure and uneven access remain challenges for more widespread adoption.
Middle East
The Middle East accounted for 2.6% of the global cardiac rehabilitation market in 2024, with a market value of USD 59.71 million, up from USD 43.42 million in 2018. The region is expected to reach USD 86.50 million by 2032, registering a CAGR of 4.3%. Market growth is being driven by the rising burden of cardiovascular diseases, especially in Gulf countries, along with increasing healthcare investments and public-private partnerships. However, the availability of comprehensive rehabilitation services remains limited in several countries, and there is growing interest in home-based and digital rehab models to address accessibility gaps.
Africa
Africa represented the smallest share in the global cardiac rehabilitation market in 2024, accounting for about 2.1%, with a market value of USD 47.46 million, up from USD 29.12 million in 2018. The market is projected to reach USD 67.58 million by 2032, growing at a CAGR of 4.0%. The region faces challenges such as limited awareness, insufficient infrastructure, and a lack of specialized cardiac care centers. However, gradual improvements in healthcare access, increasing non-communicable disease burden, and support from international health organizations are expected to create opportunities for the expansion of cardiac rehabilitation services in the coming years.
Market Segmentations:
By Product Type
- Treadmill
- Elliptical Trainer
- Stabilization Ball
- Rower
- Blood Pressure Monitor
- Heart Rate Monitor
- Others
By Indication
- Coronary Artery Disease
- Myocardial Infarction
- Coronary Artery Bypass Grafting
- Percutaneous Coronary Intervention
- Others
By End User
- Rehabilitation Centers
- Hospitals and Clinics
- Homecare
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The cardiac rehabilitation market features a moderately competitive landscape, driven by innovation, strategic collaborations, and a strong focus on integrated healthcare solutions. Leading players such as Philips Healthcare, Medtronic PLC, GE Healthcare, and LivaNova PLC dominate through diverse product portfolios and global distribution networks. These companies invest heavily in research and development to introduce advanced monitoring systems, tele-rehabilitation platforms, and connected cardiovascular care technologies. Strategic mergers, acquisitions, and partnerships further strengthen their market positioning, enabling broader service offerings and entry into emerging markets. Mid-sized players like Cardiac Science Corporation, BioTelemetry, Inc., and Hill-Rom Holdings, Inc. contribute by offering specialized rehabilitation equipment and wearable devices. Market participants are increasingly focusing on home-based and hybrid rehabilitation models to cater to the growing demand for personalized and remote care. As the market evolves, the competition is expected to intensify, particularly with the entry of technology-driven startups and regional firms offering cost-effective solutions.
Key Player Analysis
- Philips Healthcare
- Medtronic, PLC
- GE Healthcare
- Cardiac Science Corporation
- LivaNova PLC
- Baxter International Inc.
- Fujifilm Holdings Corporation
- BioTelemetry, Inc.
- Milwaukee Instruments, Inc.
- Hill-Rom Holdings, Inc.
Recent Developments
- In July 2025, Philips Healthcare announced a collaboration with Epic EHR to seamlessly integrate its cardiac ambulatory monitoring and diagnostics with Epic’s Aura platform, streamlining workflows and enhancing diagnostic and patient outcomes in cardiac care.
- In June 2025, Philips healthcare partnered with Williamson Health (Tennessee) to expand access to advanced, community-based cardiac care using Philips technology for smart imaging, real-time data, and integrated digital workflows.
- In June 2025, GE Healthcare Showcased the newly launched Flyrcado PET imaging tracer for myocardial perfusion (CAD diagnosis), now available across the U.S. with Medicare and commercial insurance coverage. Flyrcado enables improved diagnostic accuracy, especially with GE Healthcare’s Omni Legend PET/CT system, representing a new era for precise, personalized cardiac imaging.
- In April 2025, Medtronic presented positive one-year outcomes for its Sphere-360 pulsed field ablation (PFA) catheter at the Heart Rhythm Society conference, demonstrating high efficacy and safety in treating atrial fibrillation. The data showed 88% of patients were free from arrhythmia recurrence and 98% achieved durable pulmonary vein isolation, with no reported serious adverse events. The Sphere-360 catheter is part of Medtronic's FDA-approved PFA systems for atrial fibrillation.
- In November 2024, Medtronic launched the ALERT study, a multicenter initiative in partnership with Tempus, to address disparities in valve disease care, particularly for underserved patient populations. The study uses artificial intelligence (AI) and integrated electronic health records (EHRs) to identify patients with severe aortic stenosis or moderate-to-severe mitral regurgitation who may be undertreated for these conditions, with a focus on evaluating treatments like TAVR (transcatheter aortic valve replacement.
Market Concentration & Characteristics
The Cardiac Rehabilitation Market exhibits a moderately concentrated structure with a mix of global leaders and regional players competing across product, service, and technology categories. It is characterized by steady growth, driven by the high burden of cardiovascular diseases, increasing clinical adoption of structured rehab programs, and expanding home-based care options. The market benefits from strong participation by established companies such as Philips Healthcare, Medtronic, GE Healthcare, and LivaNova PLC, which hold significant shares due to their wide-ranging portfolios and global presence. It features a high degree of innovation, particularly in digital health solutions and remote monitoring technologies that improve patient access and adherence. Most providers operate in an integrated care model, combining diagnostic tools, exercise equipment, and real-time patient tracking. It shows high barriers to entry in developed regions due to strict regulatory requirements and the need for technological expertise. Demand continues to grow in emerging markets where healthcare investments are rising steadily.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Indication, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for cardiac rehabilitation services will continue to rise due to the increasing global burden of cardiovascular diseases.
- Home-based and hybrid rehabilitation models are expected to gain wider adoption, supported by digital health technologies.
- Tele-rehabilitation platforms and wearable monitoring devices will play a critical role in improving patient engagement and compliance.
- Emerging economies will present strong growth opportunities driven by improving healthcare infrastructure and rising awareness.
- Personalized rehabilitation plans tailored to individual patient needs will become more common across care settings.
- Collaborations between technology firms and healthcare providers will enhance service delivery and innovation.
- Regulatory support and favorable reimbursement policies will continue to expand access to cardiac rehab services.
- Artificial intelligence and data analytics will be increasingly integrated to optimize therapy outcomes and track patient progress.
- Equipment manufacturers will focus on portable, user-friendly devices to meet the growing demand for at-home care.
- Market competition will intensify as new entrants and startups introduce cost-effective and tech-enabled solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases
The global increase in cardiovascular diseases such as coronary artery disease, myocardial infarction, and heart failure is fueling demand for cardiac rehabilitation programs, as these interventions are proven to reduce mortality and improve patient outcomes.
Technological Advancements in Tele-rehabilitation and Wearables
Innovations in tele-rehabilitation platforms and wearable health monitoring devices are making cardiac rehab more accessible, especially for remote and home-based care, thereby expanding the market and improving patient adherence.
Favorable Reimbursement Policies and Government Initiatives
Supportive reimbursement frameworks and government mandates, particularly in North America and Europe, are encouraging both providers and patients to participate in cardiac rehabilitation, driving market growth by reducing financial barriers.
Shift Toward Home-based and Hybrid Rehabilitation Models
The adoption of home-based and hybrid cardiac rehabilitation models, accelerated by the COVID-19 pandemic and patient preference for convenience, is broadening access and creating new opportunities for technology providers and healthcare institutions.
Expansion into Emerging Markets
Rapid urbanization, increasing healthcare investments, and rising awareness of cardiac rehabilitation benefits in Asia Pacific, Latin America, and the Middle East are opening new growth avenues as these regions address the growing burden of cardiovascular diseases.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cardiac Rehabilitation, and what is its projected size in 2032?
Which Cardiac Rehabilitation market segment held the largest share in 2024?
Who are the leading companies in the Cardiac Rehabilitation market?
Which region commanded the largest share of the Cardiac Rehabilitation market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Rehabilitation Centers
- 1.2.2 Hospitals and Clinics
- 1.2.3 Homecare
- 1.2.4 Others
- 1.3 By Indication
- 1.3.1 Coronary Artery Disease
- 1.3.2 Myocardial Infarction
- 1.3.3 Coronary Artery Bypass Grafting
- 1.3.4 Percutaneous Coronary Intervention
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Treadmill
- 1.4.2 Elliptical Trainer
- 1.4.3 Stabilization Ball
- 1.4.4 Rower
- 1.4.5 Blood Pressure Monitor
- 1.4.6 Heart Rate Monitor
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,292.87 million → 2032: USD 3,924.20 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cardiac Rehabilitation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cardiac Rehabilitation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cardiac Rehabilitation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cardiac Rehabilitation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cardiac Rehabilitation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cardiac Rehabilitation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cardiac Rehabilitation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cardiac Rehabilitation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,292.87 million → 2032: USD 3,924.20 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cardiac Rehabilitation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Rehabilitation Centers
- 12.3.7.2 Hospitals and Clinics
- 12.3.7.3 Homecare
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Coronary Artery Disease
- 12.4.7.2 Myocardial Infarction
- 12.4.7.3 Coronary Artery Bypass Grafting
- 12.4.7.4 Percutaneous Coronary Intervention
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Treadmill
- 12.5.7.2 Elliptical Trainer
- 12.5.7.3 Stabilization Ball
- 12.5.7.4 Rower
- 12.5.7.5 Blood Pressure Monitor
- 12.5.7.6 Heart Rate Monitor
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cardiac Rehabilitation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cardiac Rehabilitation Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cardiac Rehabilitation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cardiac Rehabilitation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Philips Healthcare
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic PLC
- 18.4 GE Healthcare
- 18.5 LivaNova PLC
- 18.6 Baxter International Inc.
- 18.7 BioTelemetry, Inc.
- 18.8 Cardiac Science Corporation
- 18.9 Hill-Rom Holdings, Inc.
- 18.10 Fujifilm Holdings Corporation
- 18.11 Milwaukee Instruments, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

