
Cardiac Monitoring Market Overview:
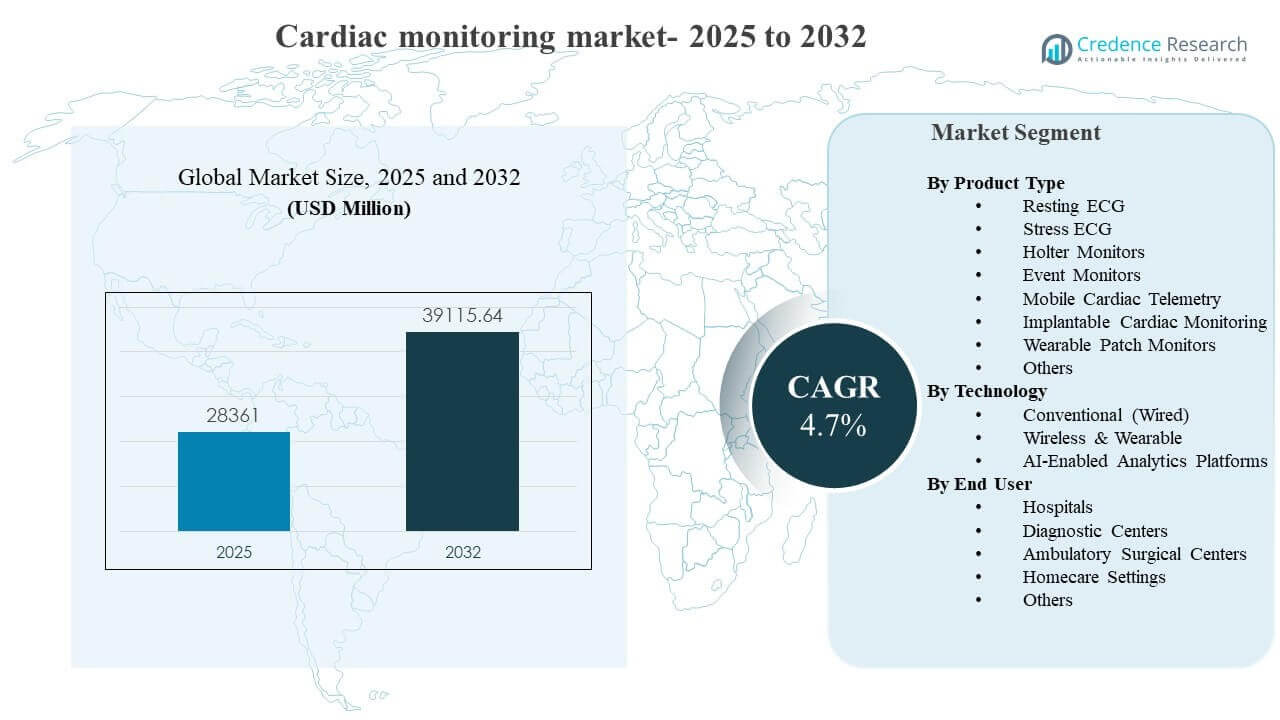
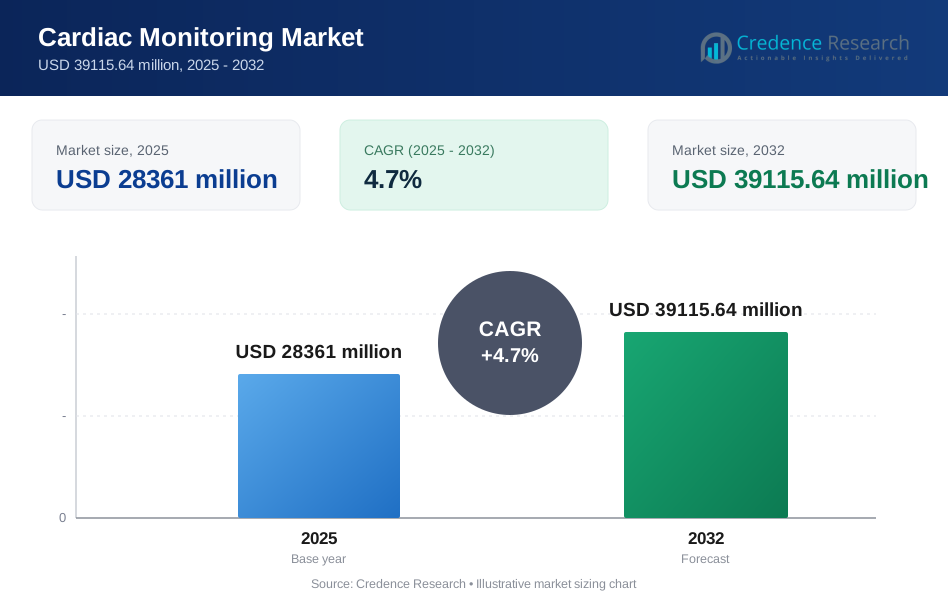
The global Cardiac monitoring market size was estimated at USD 28361 million in 2025 and is expected to reach USD 39115.64 million by 2032, growing at a CAGR of 4.7% from 2025 to 2032. The strongest growth driver is the expansion of ambulatory and remote-care pathways that require longer-duration rhythm capture beyond short in-facility exams, increasing utilization of monitoring across screening, diagnosis, post-discharge surveillance, and chronic disease follow-up. North America continues to anchor demand, supported by high adoption of connected monitoring workflows, with Europe and Asia Pacific contributing incremental expansion through broader access and modernization of cardiac care delivery.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cardiac Monitoring Market Size 2025 | USD 28361 million |
| Cardiac Monitoring Market, CAGR | 4.7% |
| Cardiac Monitoring Market Size 2032 | USD 39115.64 million |
Key Market Trends & Insights
- The Cardiac monitoring market is projected to expand from USD 28361 million in 2025 to USD 39115.64 million by 2032 at a CAGR of 4.7% during 2025–2032.
- Resting ECG accounted for the largest share of 33.4% in 2025, reflecting the foundational role of ECG in screening, triage, and longitudinal rhythm assessment.
- Conventional (Wired) systems held 55.3% revenue share in 2025, indicating continued reliance on established in-hospital monitoring infrastructure.
- Hospitals represented 48.1% share in 2025, supported by acute-care telemetry needs, specialist oversight, and higher patient throughput for cardiac evaluation.
- North America held 42.8% share in 2025, indicating the largest regional revenue contribution within the Cardiac monitoring market.
Segment Analysis
Cardiac monitoring market demand is increasingly shaped by the need to capture intermittent and asymptomatic events over longer periods, which strengthens adoption of ambulatory and wearable modalities alongside established in-facility monitoring. Provider priorities are shifting toward workflow efficiency, signal quality, and actionable interpretation, which elevates the value of connectivity and analytics in daily operations. Care pathway redesign toward earlier detection and continuous follow-up expands monitoring volumes across screening programs, outpatient cardiology, and post-procedure surveillance. Purchasing decisions also reflect integration requirements across enterprise systems, clinical staffing constraints, and expectations for scalable remote monitoring.
Cardiac monitoring market product preference varies by clinical setting and diagnostic intent. Short-duration diagnostic use cases support routine ECG utilization, while suspected paroxysmal arrhythmias increase demand for longer monitoring windows through Holter, event monitoring, and telemetry-based solutions. Implantable monitoring supports prolonged surveillance in hard-to-capture cases, especially when symptom frequency is low and diagnostic yield is critical. Wearable patch monitors continue to gain attention in ambulatory pathways due to simplified patient adherence and operational efficiency for high-volume programs.
By Product Type Insights
Resting ECG accounted for the largest share of 33.4% in 2025. Resting ECG remains widely deployed because ECG-based diagnostics are embedded across primary care, emergency assessment, inpatient telemetry workflows, and routine cardiology follow-up. Broad availability, standardized interpretation protocols, and relatively low operational complexity sustain high procedure volumes across care settings. Demand also benefits from rising screening intensity and structured monitoring in chronic cardiovascular management programs.
By Technology Insights
Conventional (Wired) accounted for the largest share of 55.3% in 2025. Conventional infrastructure remains dominant due to long replacement cycles for hospital monitoring systems and established clinical workflows built around wired bedside and telemetry architectures. Standardized device management, clinical familiarity, and compatibility with existing hospital IT and monitoring stations help sustain utilization. Wireless and wearable growth continues, but conventional deployment retains the largest installed base in acute care.
By End User Insights
Hospitals accounted for the largest share of 48.1% in 2025. Hospitals lead demand because telemetry monitoring supports acute cardiac evaluation, peri-procedural surveillance, and escalation pathways for rhythm-related events. Centralized staffing and specialist availability enable continuous monitoring and rapid clinical response in higher-risk populations. Hospital procurement also tends to favor integrated monitoring ecosystems that support multi-parameter surveillance and broader enterprise workflows.
Cardiac Monitoring Market Drivers
Expanding Burden Of Cardiovascular Disease And Arrhythmia Detection Needs
Cardiac monitoring market growth is supported by a rising clinical need to detect arrhythmias earlier and monitor high-risk patients more consistently. Increasing prevalence of chronic cardiovascular conditions raises diagnostic volumes across outpatient and inpatient settings. Greater clinical emphasis on identifying intermittent rhythm abnormalities increases demand for longer monitoring windows compared with single-visit assessments. Health systems also prioritize continuity of care, which elevates monitoring frequency across follow-up and post-discharge pathways.
Shift Toward Ambulatory And Remote Monitoring Pathways
Cardiac monitoring market adoption increases as care delivery moves from inpatient environments to ambulatory settings and home-based follow-up. Remote monitoring programs reduce avoidable visits and enable earlier intervention when clinically significant rhythm events occur. Patient convenience and adherence considerations support broader use of wearable and patch-based solutions in long-duration surveillance. Payer and provider focus on efficient utilization further accelerates deployment of scalable monitoring services.
Technology Integration And Analytics-Driven Workflow Efficiency
Cardiac monitoring market differentiation increasingly depends on connectivity, analytics, and signal triage features that improve clinician efficiency. Integration with enterprise systems reduces fragmentation across ECG review, telemetry oversight, and remote monitoring coordination. Analytics-supported interpretation improves prioritization of actionable events and reduces operational strain from non-actionable alerts. Health systems increasingly value platforms that support standardized reporting and multi-site deployment across networks.
- For instance, GE Healthcare's MUSE cardiac information management system - used by 87% of top cardiac hospitals in the United States - connects directly with hospital electronic medical records to manage and streamline the flow of cardiac information and ECG data across care settings.
Growth In Procedure Volumes And Post-Acute Surveillance Programs
Cardiac monitoring market demand benefits from growing procedural volumes and a greater need for surveillance during recovery and long-term management. Post-procedure monitoring supports early detection of complications and strengthens clinical outcomes through timely escalation. Clinical pathways increasingly incorporate structured follow-up, which increases monitoring utilization in diagnostic centers and outpatient cardiology. Expansion of specialized cardiac services across emerging markets further supports incremental equipment and service adoption.
- For instance, Medtronic's Reveal LINQ insertable cardiac monitor demonstrated that cardiologists are 3.6 times more likely to reach a diagnosis for unexplained syncope using ICMs versus conventional monitoring strategies, and between 70% and 86% of patients ultimately diagnosed with an ICM would have remained undiagnosed under conventional monitoring approaches alone.
Cardiac Monitoring Market Challenges
Cardiac monitoring market execution faces operational challenges related to data volume, signal noise, and alert burden in high-throughput environments. Clinician time constraints and staffing shortages intensify the need for efficient triage and streamlined interpretation processes. Interoperability limitations across devices, software, and enterprise systems can slow deployment and reduce workflow benefits. Patient adherence challenges also affect longer-duration ambulatory monitoring, influencing diagnostic yield and program efficiency.
- For instance, Philips reports that its Cardiologs AI platform was built on more than 200 million recordings, is used to help diagnose more than 2 million patients each year across 5 continents, reduces Holter analysis time by 42%, detects more than 20 event types, and lowered atrial fibrillation false positives from 17.2% to 1.5% in validation work, highlighting how vendors are using automation to reduce interpretation burden and noise-related workflow inefficiencies.
Cardiac monitoring market expansion is constrained by affordability and reimbursement variability across regions and care settings. Procurement decisions often require clear cost-benefit justification, especially for connected ecosystems and advanced analytics. Regulatory and compliance requirements for software-enabled monitoring can increase time-to-market and validation costs. Service scaling can also be limited by operational capacity for data review and clinical oversight.
Cardiac Monitoring Market Trends and Opportunities
Cardiac monitoring market opportunity is expanding through broader adoption of wireless and wearable monitoring aligned with outpatient growth. Care models increasingly prioritize continuous surveillance for targeted cohorts, supporting new deployment programs across provider networks. Integration of monitoring outputs into longitudinal patient records improves care coordination and strengthens clinical adoption. Demand for simplified patient experience creates openings for patch-based and streamlined multi-day monitoring workflows.
- For instance, iRhythm’s Zio adhesive patch is indicated for up to 14 days of continuous monitoring; across 22 studies, the unweighted mean wear time was 10.4 days, and a comparative study found the device detected 57% more arrhythmia events than 24-hour Holter monitoring, while 81% of patients preferred Zio over Holter monitors.
Cardiac monitoring market evolution increasingly favors analytics-led differentiation and enterprise connectivity. AI-enabled interpretation and workflow automation can reduce review burden and support faster decision-making in resource-constrained environments. Monitoring vendors can expand value through integrated platforms that connect diagnostics, telemetry, and remote follow-up into unified workflows. Growth opportunities also emerge from partnerships that combine devices, services, and clinical programs for scalable monitoring adoption.
Regional Insights
North America
North America accounted for 42.8% share in 2025. Cardiac monitoring market demand in the region is anchored by advanced care infrastructure and strong uptake of connected monitoring workflows across hospital and ambulatory pathways. High screening intensity and structured follow-up programs increase utilization across diagnostic and chronic management settings. Enterprise integration expectations support replacement and upgrade cycles for monitoring ecosystems. Provider focus on remote pathways also supports sustained adoption of wearable and telemetry-enabled services.
Europe
Europe accounted for 25.9% share in 2025. Cardiac monitoring market performance is supported by established cardiology networks and broad access to diagnostic services across major economies. Hospitals and diagnostic centers maintain steady monitoring volumes through standardized rhythm assessment and follow-up practices. Demand is reinforced by modernization of monitoring infrastructure and expansion of ambulatory pathways. Adoption patterns vary by country due to reimbursement differences and procurement cycles.
Asia Pacific
Asia Pacific accounted for 21.7% share in 2025. Cardiac monitoring market growth in the region benefits from expanding access to hospital services, rising awareness of cardiovascular risk, and increasing adoption of ambulatory care pathways in metropolitan centers. Infrastructure investment supports greater deployment of monitoring devices across public and private systems. Demand accelerates as specialized cardiac programs expand and monitoring becomes more integrated into routine care. Market growth remains uneven across countries due to differences in affordability and clinical capacity.
Latin America
Latin America accounted for 6.2% share in 2025. Cardiac monitoring market adoption is concentrated in larger economies with stronger private-sector healthcare capacity and higher access to diagnostics. Budget constraints and uneven distribution of specialty services limit penetration of advanced monitoring technologies in smaller markets. Diagnostic centers play an important role in expanding access to monitoring in urban areas. Gradual expansion of remote monitoring programs creates incremental opportunities across private providers.
Middle East & Africa
Middle East & Africa accounted for 3.4% share in 2025. Cardiac monitoring market deployment is driven by expansion of tertiary care centers and modernization initiatives in select countries. Adoption is strongest in regions with higher healthcare spending and established specialist services. Access constraints and procurement limitations continue to slow broad penetration across many markets. Remote monitoring pilots and network expansion create longer-term opportunity as infrastructure matures.
Competitive Landscape
Cardiac monitoring market competition centers on portfolio breadth, enterprise integration, and differentiated ambulatory monitoring capabilities across hospital, outpatient, and home-care pathways. Major players compete through integrated ecosystems that combine devices, software, and services to improve workflow efficiency and clinical decision support. Differentiation increasingly depends on connectivity, analytics-supported interpretation, and scalable remote monitoring programs. Partnerships, product refresh cycles, and clinical evidence generation remain key levers to expand adoption across provider networks.
Abbott emphasizes long-duration monitoring and ecosystem integration that supports clinical workflows across diagnosis, follow-up, and remote surveillance. Abbott positions monitoring solutions to reduce fragmentation between device data and clinical decision-making pathways. Abbott also benefits from a broad medtech footprint that supports cross-selling within cardiology service lines. Abbott continues to align monitoring offerings with expanding ambulatory and home-based care models.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Abbott
- AliveCor, Inc.
- Baxter
- BIOTRONIK
- Boston Scientific Corporation
- GE HealthCare
- iRhythm Technologies, Inc.
- Koninklijke Philips N.V.
- Medtronic plc
- MicroPort Scientific Corporation
- NIHON KOHDEN CORPORATION
- OSI Systems, Inc.
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- Stryker
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In April 2025, LifeSignals, Inc. launched the UbiqVue 2AYe Holter System in partnership with UltraLinQ Healthcare Solutions at Heart Rhythm 2025. The company said the new Holter solution is built to speed cardiac monitoring workflows, uses a single-use chest-worn biosensor, collects 2-channel ECG and event data for up to five days, and transmits encrypted patient data to a cloud-based analytics platform for faster report delivery.
- In April 2025, CardioOne acquired CardioDiagnostics to strengthen its virtual cardiology and remote cardiac monitoring capabilities for physician practices. CardioOne later stated that the acquisition was intended to support a broader value-based cardiology care model, and the acquired capabilities were incorporated into its CardioOne Connect monitoring and care platform announced in January 2026.
- In September 2025, Health-E Commerce and Biotricity announced a partnership to expand access to Biotricity’s Bioheart wearable cardiac monitoring solution. The collaboration makes Bioheart available to more than 70 million consumers enrolled in FSA and HSA programs, which broadens consumer access to continuous 24/7 cardiac monitoring technology
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 28361 million |
| Revenue forecast in 2032 | USD 39115.64 million |
| Growth rate (CAGR) | 4.7% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Product Type Outlook: Resting ECG, Stress ECG, Holter Monitors, Event Monitors, Mobile Cardiac Telemetry, Implantable Cardiac Monitoring, Wearable Patch Monitors, Others; By Technology Outlook: Conventional (Wired), Wireless & Wearable, AI-Enabled Analytics Platforms; By End User Outlook: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Homecare Settings, Others |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Abbott; AliveCor, Inc.; Baxter; BIOTRONIK; Boston Scientific Corporation; GE HealthCare; iRhythm Technologies, Inc.; Koninklijke Philips N.V.; Medtronic plc; MicroPort Scientific Corporation; NIHON KOHDEN CORPORATION; OSI Systems, Inc.; Shenzhen Mindray Bio-Medical Electronics Co., Ltd.; Stryker |
| No. of Pages | 324 |
By Segmentation
By Product Type
- Resting ECG
- Stress ECG
- Holter Monitors
- Event Monitors
- Mobile Cardiac Telemetry
- Implantable Cardiac Monitoring
- Wearable Patch Monitors
- Others
By Technology
- Conventional (Wired)
- Wireless & Wearable
- AI-Enabled Analytics Platforms
By End User
- Hospitals
- Diagnostic Centers
- Ambulatory Surgical Centers
- Homecare Settings
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Ambulatory and Remote Monitoring Pathways
The shift from inpatient to ambulatory and home-based care is driving demand for cardiac monitoring devices that enable longer-duration rhythm capture and remote surveillance, supporting earlier detection and continuous follow-up.
Rising Burden of Cardiovascular Disease and Arrhythmia Detection Needs
Increasing prevalence of chronic cardiovascular conditions and the need to detect intermittent arrhythmias are boosting diagnostic volumes and necessitating more frequent and prolonged cardiac monitoring across care settings.
Technology Integration and Analytics-Driven Workflow Efficiency
Healthcare providers are prioritizing solutions with advanced connectivity, analytics, and AI-enabled interpretation to streamline workflows, reduce alert fatigue, and improve clinical decision-making, fueling adoption of next-generation monitoring platforms.
Growth in Procedure Volumes and Post-Acute Surveillance
Rising numbers of cardiac procedures and the emphasis on structured post-procedure surveillance are increasing the utilization of monitoring devices for early complication detection and long-term management.
Broader Adoption of Wearable and Patch-Based Monitors
Wearable and patch-based cardiac monitors are gaining traction due to their patient convenience, improved adherence, and operational efficiency, especially in high-volume outpatient and screening programs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Cardiac monitoring market in 2025 and the forecast for 2032?
What is the CAGR of the Cardiac monitoring market during 2025–2032?
Which segment holds the largest share in the Cardiac monitoring market?
What factors are driving growth in the Cardiac monitoring market?
Who are the leading companies in the Cardiac monitoring market?
Which region leads the Cardiac monitoring market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Diagnostic Centers
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Homecare Settings
- 1.2.5 Others
- 1.3 By Technology
- 1.3.1 Conventional (Wired)
- 1.3.2 Wireless & Wearable
- 1.3.3 AI-Enabled Analytics Platforms
- 1.4 By Product Type
- 1.4.1 Resting ECG
- 1.4.2 Stress ECG
- 1.4.3 Holter Monitors
- 1.4.4 Event Monitors
- 1.4.5 Mobile Cardiac Telemetry
- 1.4.6 Implantable Cardiac Monitoring
- 1.4.7 Wearable Patch Monitors
- 1.4.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 28361 million → 2032: USD 39115.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cardiac Monitoring Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cardiac Monitoring Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cardiac Monitoring Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cardiac Monitoring Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cardiac Monitoring Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cardiac Monitoring Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cardiac Monitoring Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cardiac Monitoring Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 28361 million → 2032: USD 39115.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cardiac Monitoring Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Diagnostic Centers
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Homecare Settings
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional (Wired)
- 12.4.7.2 Wireless & Wearable
- 12.4.7.3 AI-Enabled Analytics Platforms
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Resting ECG
- 12.5.7.2 Stress ECG
- 12.5.7.3 Holter Monitors
- 12.5.7.4 Event Monitors
- 12.5.7.5 Mobile Cardiac Telemetry
- 12.5.7.6 Implantable Cardiac Monitoring
- 12.5.7.7 Wearable Patch Monitors
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cardiac Monitoring End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cardiac Monitoring Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cardiac Monitoring Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cardiac Monitoring Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GE HealthCare
- 18.4 Medtronic plc
- 18.5 Boston Scientific Corporation
- 18.6 Koninklijke Philips N.V.
- 18.7 iRhythm Technologies, Inc.
- 18.8 BIOTRONIK
- 18.9 NIHON KOHDEN CORPORATION
- 18.10 Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- 18.11 AliveCor, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

