
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
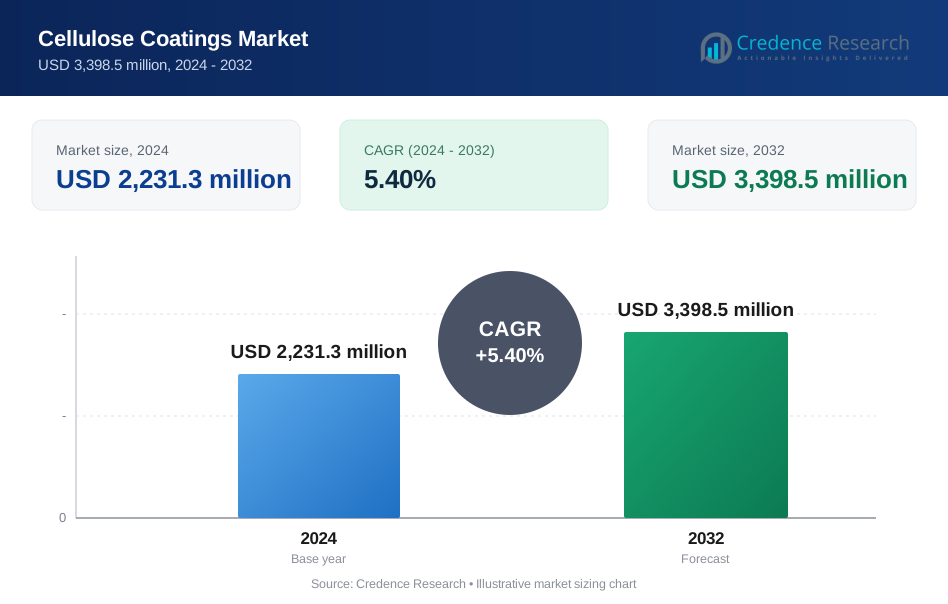
| Cellulose Coatings Market Size 2024 | USD 2,231.3 million |
| Cellulose Coatings Market, CAGR | 5.40% |
| Cellulose Coatings Market Size 2032 | USD 3,398.5 million |
Market Overview
The Cellulose Coatings market size was valued at USD 1,753.3 million in 2018, reached USD 2,231.3 million in 2024, and is anticipated to reach USD 3,398.5 million by 2032, at a CAGR of 5.40% during the forecast period.
The Cellulose Coatings market features prominent players such as AkzoNobel, PPG Industries, Sherwin-Williams, BASF, and Axalta Coating Systems, which lead through robust product portfolios and a strong global presence. These companies consistently invest in innovation to develop eco-friendly and high-performance coatings. Other key participants, including Nippon Paint Holdings, Kansai Paint, Benjamin Moore, RPM International, and Sika AG, focus on expanding their regional footprints and enhancing product sustainability. Asia Pacific dominates the market, holding a significant 30.4% share in 2018, driven by rapid industrialization, growing construction activities, and increasing demand for furniture. Europe and North America follow as major contributors, supported by strict environmental regulations and high consumer preference for sustainable coatings.
Market Insights
- The Cellulose Coatings market was valued at USD 1,753.3 million in 2018, reached USD 2,231.3 million in 2024, and is projected to reach USD 3,398.5 million by 2032, growing at a CAGR of 5.40%.
- Increasing demand for eco-friendly, low-VOC coatings and growing construction and furniture industries are driving market growth globally.
- The market is witnessing a rising trend toward bio-based and waterborne cellulose coatings, supported by technological advancements in coating formulations and application methods.
- The market is moderately competitive, with key players like AkzoNobel, PPG Industries, Sherwin-Williams, and BASF focusing on innovation, while price volatility of raw materials and limited performance in harsh environments act as restraints.
- Asia Pacific holds the largest regional share at 30.4%, while the furniture segment dominates by application; Europe and North America follow with shares of 29.5% and 25.8%, respectively, driven by strict regulations and rising demand for sustainable products.
Market Segmentation Analysis:
By Product Type:
In the Cellulose Coatings market, Nitrocellulose Coatings dominate the product type segment, accounting for the largest market share in 2024. Their strong demand is driven by their fast-drying properties, excellent gloss, and cost-effectiveness, making them highly suitable for high-volume manufacturing industries. Nitrocellulose coatings are widely preferred for applications requiring quick turnaround times and aesthetic finishes, particularly in the furniture and interior sectors. On the other hand, Cellulose Acetate Coatings are gradually gaining traction due to their superior environmental profile and safer chemical composition, aligning with increasing regulatory pressures and growing consumer demand for sustainable products.
- For instance, AkzoNobel’s Sikkens brand offers nitrocellulose coatings that achieve full surface drying in less than 10 minutes per coat when applied in a controlled environment, significantly reducing processing time for furniture
By Application
The Furniture sub-segment holds the largest share in the application segment of the Cellulose Coatings market. The growth of this sub-segment is driven by the rising demand for visually appealing and durable furniture products, where cellulose coatings offer excellent finishing, protection, and aesthetic value. Internal Doors and MDF Building Products also show significant usage of cellulose coatings, particularly in modern construction and home renovation projects. The Children Toys and Hospitals applications are expanding steadily due to growing health and safety standards that favor low-toxicity, environmentally friendly coatings to reduce exposure to harmful chemicals.
- For instance, Sherwin-Williams’ nitrocellulose-based coating systems are used on over 5 million wooden furniture units annually in their Asia Pacific client network, demonstrating large-scale adoption.
Market Overview
Rising Demand for Eco-Friendly and Low-VOC Coatings
The increasing global emphasis on environmental sustainability and stringent regulations on volatile organic compounds (VOCs) are major drivers for the cellulose coatings market. Consumers and industries are steadily shifting towards eco-friendly alternatives, favoring cellulose coatings for their low toxicity and biodegradability. Governments worldwide are promoting the use of green products, which significantly boosts the adoption of cellulose-based coatings across various sectors, including furniture, construction, and healthcare. This environmental advantage positions cellulose coatings as a preferred solution in modern manufacturing and finishing applications.
- For instance, Kansai Paint’s Ales Cool eco-friendly cellulose-based coating achieved certification for containing VOC levels as low as 30 g/L, in line with the Japanese Ministry of the Environment’s standards for sustainable products.
Expanding Furniture and Interior Design Industry
The rapid growth of the global furniture and interior design industry significantly fuels the demand for cellulose coatings. These coatings offer excellent finishing, enhanced durability, and aesthetic appeal, making them highly suitable for wood-based products such as furniture, doors, and MDF panels. Increasing urbanization, rising disposable incomes, and the growing consumer preference for visually appealing interiors are driving furniture sales, especially in Asia Pacific and Europe. This market expansion directly contributes to the growing need for high-performance, safe, and cost-effective cellulose coatings.
- For instance, Nippon Paint’s wood coating division in India reported the supply of coatings for over 12,000 modular kitchens in 2023, highlighting strong adoption in the residential furniture segment.
Growth in Construction and Renovation Activities
Global construction and renovation activities, particularly in emerging economies, present a key growth driver for the cellulose coatings market. The increased use of wood and engineered wood products in modern architecture requires effective coatings that provide both protection and aesthetic value. Cellulose coatings are widely adopted for interior doors, flooring, and paneling applications due to their superior finishing properties. The expanding middle-class population and growing demand for affordable housing further accelerate construction, boosting the consumption of cellulose coatings in both residential and commercial projects.
Key Trends & Opportunities
Rising Adoption of Bio-Based and Waterborne Coatings
There is a growing trend towards bio-based and waterborne cellulose coatings as industries aim to reduce environmental impact. Companies are increasingly investing in research to develop high-performance, sustainable coatings that meet regulatory standards without compromising quality. The shift to waterborne cellulose coatings offers benefits such as reduced odor, lower emissions, and safer application processes. This trend opens new growth opportunities for manufacturers to expand eco-friendly product lines and cater to the evolving preferences of environmentally conscious consumers and industrial buyers.
- For instance, RPM International’s Rust-Oleum division launched a waterborne cellulose coating in 2022 that contains 95% bio-based carbon as verified by USDA BioPreferred certification, positioning it among the most sustainable options in the segment.
Technological Advancements in Coating Application
Technological innovations in coating formulations and application methods are creating significant opportunities in the cellulose coatings market. Advances such as improved spray technologies and fast-drying solutions enhance operational efficiency and reduce production time for manufacturers. Additionally, innovations that improve adhesion, scratch resistance, and longevity are gaining traction across end-use industries. These developments allow cellulose coatings to compete more effectively with synthetic alternatives, opening pathways for market penetration in high-demand sectors like healthcare, furniture, and premium interior applications.
- For instance, PPG’s electrostatic application of its SIGMAGLIDE® 2390 marine coating at the EDR Antwerp shipyard reduced overspray from 100 units to 60 units during the coating of the Stena Transporter hull cutting waste by 40 units per job, per full hull application.
Key Challenges
Raw Material Price Volatility
The cellulose coatings market faces challenges related to the fluctuating prices of raw materials such as cellulose derivatives and solvents. Price instability can significantly impact manufacturing costs and profit margins, making it difficult for producers to maintain competitive pricing. Dependence on agricultural or wood-based sources for cellulose extraction further subjects the supply chain to uncertainties linked to crop yields, climate conditions, and forestry regulations. Managing cost pressures while ensuring consistent supply remains a persistent hurdle for industry participants.
Limited Performance in Harsh Environments
Despite their eco-friendly properties, cellulose coatings often exhibit limited performance in extreme environmental conditions, such as high humidity, UV exposure, or heavy mechanical stress. Compared to synthetic coatings, they may offer lower resistance to water, heat, and abrasion, restricting their application in certain outdoor or industrial settings. This performance gap limits their competitiveness in markets that require highly durable protective coatings, posing a challenge for broader adoption unless technological improvements address these limitations.
Market Competition from Synthetic Alternatives
The cellulose coatings market faces strong competition from well-established synthetic and polyurethane-based coatings that offer superior durability and versatility. These synthetic products often deliver longer lifespan and greater resistance to environmental factors, making them a preferred choice in demanding applications. Overcoming this competitive pressure requires cellulose coating manufacturers to focus on continuous product innovation, improved marketing of sustainability benefits, and the development of advanced formulations that can match or exceed the performance of synthetic alternatives.
Regional Analysis
North America
In the Cellulose Coatings market, North America accounted for 25.8% of the global share in 2018, with a market size of USD 452.3 million. By 2024, the market is expected to reach USD 524.4 million, progressing to USD 720.5 million by 2032, at a CAGR of 4.9%. The steady demand is driven by strong construction, furniture, and healthcare industries, where safety and aesthetic finishes remain key priorities. The region benefits from advanced manufacturing practices and high consumer awareness regarding eco-friendly coatings. North America's continued growth is supported by increasing regulations favoring low-VOC, cellulose-based coating solutions.
Europe
Europe held a 29.5% share of the global Cellulose Coatings market in 2018, valued at USD 517.2 million. The market is projected to rise to USD 624.8 million by 2024 and further to USD 883.6 million by 2032, growing at a CAGR of 5.3%. Europe’s growth is driven by strict environmental regulations, rising demand for sustainable coatings, and a thriving furniture manufacturing sector. Consumers in Europe are increasingly favoring low-emission products, which is boosting cellulose coating adoption. Additionally, technological advancements and the rapid adoption of bio-based solutions contribute significantly to regional market expansion.
Asia Pacific
Asia Pacific dominated the global Cellulose Coatings market with a 30.4% share in 2018, valued at USD 533.0 million. The regional market is forecasted to grow to USD 758.6 million by 2024 and reach USD 1,308.4 million by 2032, registering the fastest CAGR of 6.6%. The region’s rapid industrialization, booming construction sector, and expanding furniture market are key growth drivers. Countries such as China, India, and Japan contribute significantly to the rising demand. Increasing disposable incomes and growing preference for aesthetically appealing and sustainable interior products further accelerate market growth across Asia Pacific.
Latin America
Latin America represented a 4.2% market share in 2018, with a valuation of USD 73.6 million. By 2024, the market is anticipated to reach USD 107.1 million and further grow to USD 190.3 million by 2032, at a CAGR of 4.3%. The region’s growth is supported by increasing urbanization, construction activities, and a rising middle-class population seeking affordable, durable, and visually appealing furniture products. Countries like Brazil and Mexico are the primary contributors. However, the market growth is somewhat limited by moderate manufacturing capabilities and price-sensitive consumer behavior.
Middle East
The Middle East accounted for a 6.2% share in the Cellulose Coatings market in 2018, with a market size of USD 108.7 million. The market is projected to rise to USD 133.9 million by 2024 and USD 197.1 million by 2032, expanding at a CAGR of 3.7%. The region shows steady growth due to increasing investments in the construction and furniture sectors, especially in countries such as the UAE and Saudi Arabia. The demand for premium coatings in commercial and residential projects is creating growth opportunities, although market penetration remains limited due to climatic and regulatory challenges.
Africa
Africa held a 3.9% share in the global Cellulose Coatings market in 2018, with a value of USD 68.4 million. The market is forecasted to grow to USD 82.6 million by 2024 and reach USD 98.6 million by 2032, registering a CAGR of 3.1%. The market in Africa is gradually expanding, driven by growing urban infrastructure and the increasing demand for cost-effective coatings in residential projects. However, limited awareness of eco-friendly coatings and underdeveloped industrial bases in many countries restrain faster growth. Future prospects lie in improving distribution channels and increasing awareness of sustainable coating alternatives.
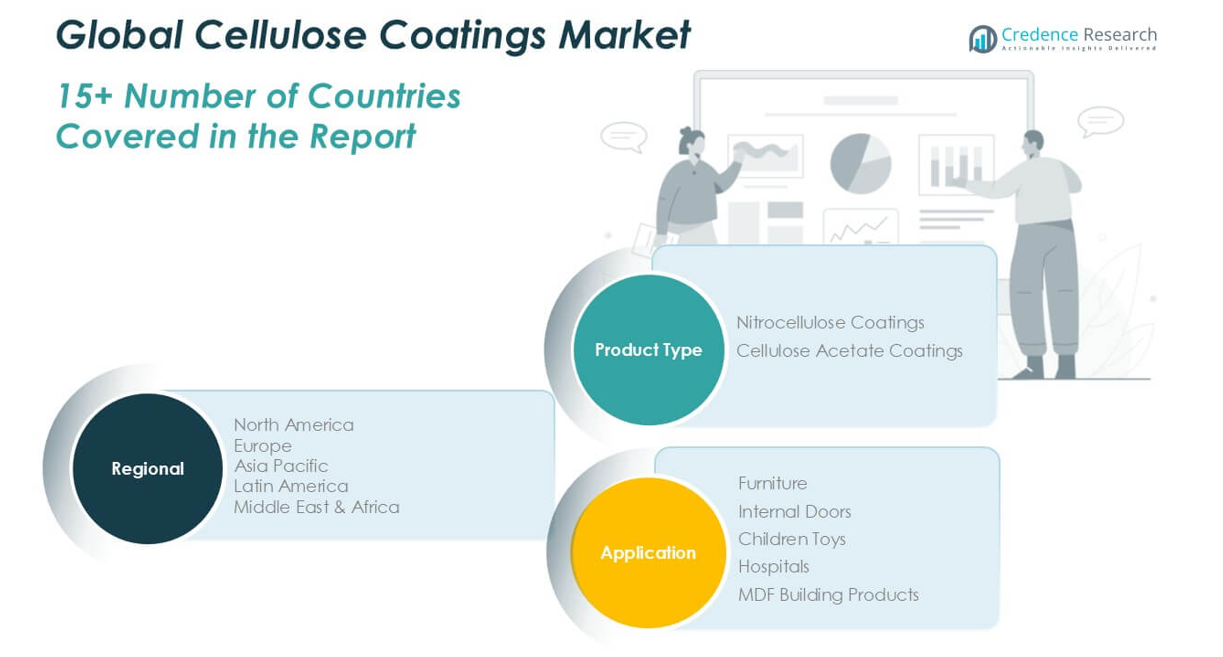
Market Segmentations:
By Product Type
- Nitrocellulose Coatings
- Cellulose Acetate Coatings
By Application
- Furniture
- Internal Doors
- Children Toys
- Hospitals
- MDF Building Products
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Cellulose Coatings market is moderately fragmented, with several global and regional players actively competing to strengthen their market presence. Key companies such as AkzoNobel, PPG Industries, Sherwin-Williams, BASF, and Axalta Coating Systems lead the market through extensive product portfolios, strong distribution networks, and consistent innovation. These players focus on developing eco-friendly, low-VOC, and high-performance coatings to align with growing regulatory demands and shifting consumer preferences toward sustainable solutions. Additionally, companies like Nippon Paint Holdings, Kansai Paint, and Benjamin Moore emphasize expanding their footprint in emerging markets by offering tailored solutions for local industries. Strategic activities such as mergers, acquisitions, and partnerships remain prevalent as companies seek to enhance their market share and technology capabilities. Furthermore, smaller regional players like Barpimo, ICA Group, and Sirca S.p.A. contribute to market competitiveness by offering specialized products and cost-effective solutions, particularly catering to niche applications and regional demands.
Key Player Analysis
- AkzoNobel
- PPG Industries
- Sherwin-Williams
- BASF
- Axalta Coating Systems
- Nippon Paint Holdings
- Kansai Paint
- Benjamin Moore
- RPM International
- Sika AG
- Barpimo
- ICA Group
- Tikkurila
- Sirca S.p.A.
Recent Developments
- In May 2025, BASF expanded its biomass-balanced coatings portfolio (including refinish and OEM coatings), now launching in North America after Europe and Asia. These products use renewable raw materials to replace fossil resources, reducing CO₂ emissions by 8 million kg in 2024. The approach is certified and supports the circular economy, but does not specify cellulose as the feedstock.
- In January 2025, PPG launched its DuraNEXT™ Energy Curable Coil Coatings in the summer of 2024, and the technology was recognized with a METALCON Top Products Award. The DuraNEXT™ platform utilizes electron beam (EB) or UV energy for rapid curing, leading to substantial energy savings and sustainability improvements compared to traditional thermal curing methods. While not cellulose-based, it represents a significant step forward in sustainable coating solutions.
- In January 2024, Axalta Coating Systems received the 2024 BIG Innovation Award for two products: Voltatex® 7345 A ECO Wire Enamel and Raptor® Flameproof Coating. These coatings are recognized for their sustainable and high-performance attributes, specifically in the areas of efficient electrification and high-temperature protection, respectively.
- In February 2024, SaXcell at PV Paris exhibition showed recycled apparel and fabric samples at Birla Cellulose stall (leading manufacturer of manmade cellulose fiber). This partnership aimed to enhance the production of recycled man-made cellulose fibers.
- In February 2024, Birla Cellulose forged a partnership with Bharat Tex aiming to foster innovation in man-made cellulose fiber within textile sector.
Market Concentration & Characteristics
The Cellulose Coatings Market is moderately fragmented, with the presence of several global and regional players competing on product innovation, sustainability, and pricing. It demonstrates a balanced mix of large multinational corporations and smaller niche manufacturers that focus on specialized applications and local market needs. Leading companies actively invest in eco-friendly technologies and low-VOC formulations to align with tightening environmental regulations. The market is characterized by steady demand from industries such as furniture, construction, and healthcare, where aesthetic appeal and safety remain critical factors. It shows a clear shift toward bio-based and waterborne solutions, driven by increasing consumer awareness and regulatory pressures. The competition is defined by a combination of product quality, pricing strategies, and the ability to offer sustainable solutions. Companies consistently work to strengthen their distribution networks and regional presence to maintain a competitive edge. Price sensitivity in emerging markets and raw material cost fluctuations shape purchasing decisions across key segments. It benefits from stable growth opportunities in both developed and developing regions, with Asia Pacific emerging as the fastest-growing market due to rapid industrialization and rising consumer demand for affordable, high-quality coatings.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Cellulose Coatings market is expected to witness steady growth driven by increasing demand for eco-friendly and sustainable coating solutions.
- Regulatory support for low-VOC and biodegradable coatings will continue to shape product development and market strategies.
- Rising applications in the furniture and construction industries will remain a major contributor to market expansion globally.
- Asia Pacific is anticipated to maintain its position as the fastest-growing region due to rapid industrialization and growing consumer demand.
- Advancements in bio-based and waterborne coating technologies will create new growth opportunities for manufacturers.
- Companies are likely to focus on improving coating durability and performance to overcome limitations in harsh environments.
- Competitive pricing and efficient supply chain management will be essential to capture market share in price-sensitive regions.
- Expansion into emerging markets will be a key growth strategy for leading players seeking long-term opportunities.
- Product customization and development of specialized coatings for healthcare and children's products will gain importance.
- Strategic partnerships, mergers, and acquisitions will continue to shape the competitive landscape and drive innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Eco-Friendly and Low-VOC Coatings
Stringent environmental regulations and increasing consumer awareness are driving the adoption of cellulose coatings, which offer low toxicity and biodegradability compared to synthetic alternatives. This shift is particularly strong in regions with strict VOC limits, supporting market growth.
Expansion of Furniture and Interior Design Industries
The rapid growth of the global furniture and interior design sectors, especially in Asia Pacific and Europe, is fueling demand for cellulose coatings due to their excellent finishing, durability, and aesthetic appeal for wood-based products.
Growth in Construction and Renovation Activities
Increasing construction and renovation projects, particularly in emerging economies, are boosting the use of cellulose coatings for interior doors, paneling, and MDF products, as these coatings provide both protection and visual enhancement.
Technological Advancements in Bio-Based and Waterborne Coatings
Ongoing innovation in bio-based and waterborne cellulose coatings is enabling manufacturers to offer products with reduced emissions, improved application properties, and enhanced sustainability, opening new market opportunities.
Health and Safety Standards in Sensitive Applications
Rising health and safety standards in sectors such as children's toys and healthcare are increasing the preference for cellulose coatings, which are favored for their low toxicity and compliance with stringent safety regulations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cellulose Coatings Market?
What are the key segments within the Cellulose Coatings Market?
What are some challenges faced by the Cellulose Coatings Market?
Who are the major players in the Cellulose Coatings Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Furniture
- 1.2.2 Internal Doors
- 1.2.3 Children Toys
- 1.2.4 Hospitals
- 1.2.5 MDF Building Products
- 1.3 By Product Type
- 1.3.1 Nitrocellulose Coatings
- 1.3.2 Cellulose Acetate Coatings
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,231.3 million → 2032: USD 3,398.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cellulose Coatings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cellulose Coatings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cellulose Coatings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cellulose Coatings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cellulose Coatings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cellulose Coatings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cellulose Coatings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cellulose Coatings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,231.3 million → 2032: USD 3,398.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cellulose Coatings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Furniture
- 12.3.7.2 Internal Doors
- 12.3.7.3 Children Toys
- 12.3.7.4 Hospitals
- 12.3.7.5 MDF Building Products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Nitrocellulose Coatings
- 12.4.7.2 Cellulose Acetate Coatings
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cellulose Coatings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cellulose Coatings Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cellulose Coatings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cellulose Coatings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AkzoNobel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 PPG Industries
- 18.4 Sherwin-Williams
- 18.5 BASF
- 18.6 Axalta Coating Systems
- 18.7 Nippon Paint Holdings
- 18.8 Kansai Paint
- 18.9 Benjamin Moore
- 18.10 RPM International
- 18.11 Sika AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

