
Citrus Fibers Market Overview:
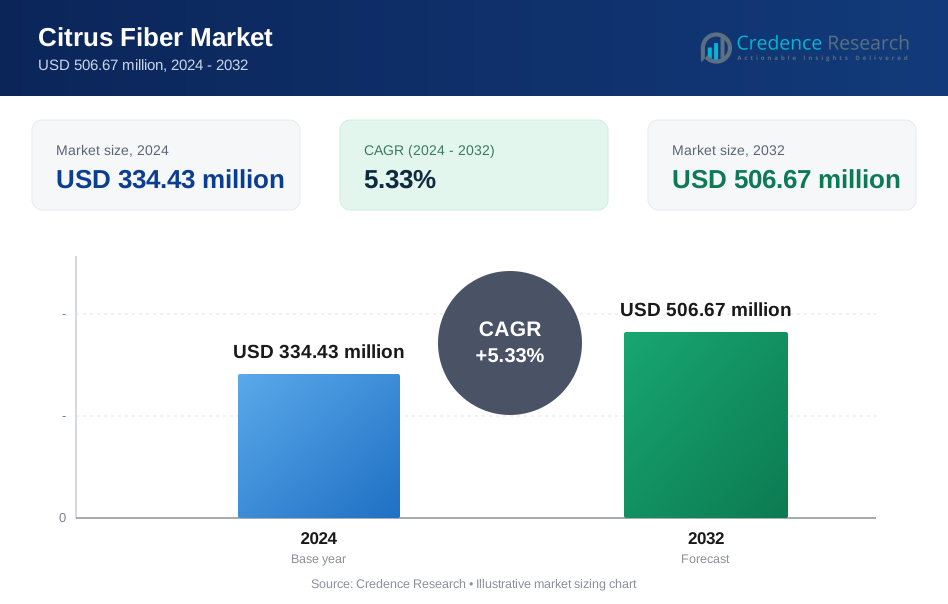
The global citrus fibers market was valued at USD 334.43 million in 2024 and is projected to reach USD 506.67 million by 2032, expanding at a CAGR of 5.33% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Citrus Fibers Market Size 2024 | USD 334.43 million |
| Citrus Fibers Market , CAGR | 5.33% |
| Citrus Fibers Market Size 2032 | USD 506.67 million |
Citrus Fibers Market Insights
- Market growth is primarily driven by rising demand for clean-label, plant-based, and multifunctional ingredients, with citrus fibers increasingly used to replace synthetic stabilizers and texturizers in bakery, sauces, processed meats, and dairy alternatives, while insoluble citrus fibers dominate the type segment due to superior water-binding and texture-enhancing properties.
- Key market trends include strong adoption in plant-based and reduced-fat formulations, growing use of orange-based citrus fibers as the dominant form due to abundant raw material availability, and expanding applications as thickening and stabilizing agents, which collectively account for the largest functional share.
- The competitive landscape features a combination of global ingredient suppliers and specialized fiber producers competing on functionality, sustainability credentials, customized solutions, and secure citrus peel sourcing from juice-processing by-products.
- Regionally, North America leads with approximately 34% market share, followed by Europe at around 29% and Asia-Pacific at nearly 24%, while Latin America and the Middle East & Africa together account for the remaining share, supported by citrus availability and gradual clean-label adoption.

Citrus Fibers Market Segmentation Analysis:
By Type:
The citrus fibers market by type is segmented into insoluble and soluble fibers, with insoluble citrus fibers representing the dominant sub-segment due to their broad functional utility and cost efficiency. Insoluble fibers are widely used in bakery, meat processing, and dairy formulations for water retention, texture enhancement, and yield improvement. Their ability to improve mouthfeel while maintaining clean-label positioning drives strong adoption among food manufacturers. Soluble citrus fibers, while growing steadily, are primarily favored in beverages and nutraceuticals for viscosity control and fiber enrichment, supporting incremental demand across functional food applications.
- For instance, Fiberstar’s Citri-Fi® 100 FG citrus fiber contains approximately 74–80 g of total dietary fiber per 100 g and can bind 9 to 10 times its own weight in water. This enabling of moisture retention and texture stability in processed foods is achieved through a patented physical process without the use of chemical additives.
By Form:
By form, the market includes lemon and lime, orange, mandarins, and grapefruits, with orange-based citrus fibers holding the dominant market share. Orange peels are abundantly available as by-products of large-scale juice processing, ensuring consistent raw material supply and favorable economics. Orange citrus fibers offer balanced water-binding, emulsification, and neutral flavor characteristics, making them highly versatile across bakery, dairy alternatives, sauces, and processed meats. Lemon and lime fibers follow, driven by higher acidity tolerance and niche applications, while mandarins and grapefruits remain smaller segments due to limited availability and specialized usage.
- For instance, Ingredion’s Fibertex® CF citrus fiber range is produced from orange peel and delivers water-binding capacity exceeding 7 g of water per gram of fiber, supporting texture stability in bakery, sauces, and meat applications.
By Function:
Based on function, citrus fibers are used as thickening agents, stabilizers, gelling agents, and fat replacements, with thickening and stabilization functions collectively forming the dominant sub-segment. Their strong water-holding capacity and natural emulsifying properties enable manufacturers to replace synthetic hydrocolloids while maintaining product consistency and shelf stability. Demand is particularly strong in clean-label sauces, dressings, plant-based dairy, and meat analogs. Fat replacement applications are expanding steadily, supported by reformulation trends aimed at calorie reduction, while gelling uses remain application-specific within confectionery and structured food systems.
Key Growth Drivers
Rising Demand for Clean-Label and Natural Ingredients
The citrus fibers market is strongly driven by the accelerating shift toward clean-label food and beverage formulations. Manufacturers are actively replacing synthetic hydrocolloids, emulsifiers, and texturizers with recognizable, plant-derived alternatives that align with consumer expectations for transparency and minimal processing. Citrus fibers, sourced from fruit peels, meet these requirements while delivering essential functional benefits such as water binding, viscosity control, and texture enhancement. Their natural positioning supports label simplification across bakery, dairy alternatives, sauces, and processed foods. This driver is further reinforced by regulatory scrutiny of artificial additives and growing retailer pressure to reformulate products with natural ingredients, positioning citrus fibers as a preferred multifunctional solution.
- For instance, CP Kelco’s Citri-Fi® citrus fiber range enables oil reduction in meat and sauce formulations while maintaining structure, with documented water-holding capacity of up to 8 g per gram of fiber, allowing formulators to eliminate modified starches and emulsifiers.
Expansion of Plant-Based and Reduced-Fat Food Formulations
Growth in plant-based, vegan, and flexitarian diets is significantly boosting demand for citrus fibers. These fibers play a critical role in improving mouthfeel, structure, and stability in plant-based meat and dairy alternatives, where fat and protein systems differ from conventional products. Citrus fibers are also widely used as fat replacers, helping manufacturers reduce fat content without compromising texture or sensory quality. As food brands continue to innovate around healthier, calorie-conscious products, citrus fibers provide formulation flexibility while maintaining product performance. This driver is especially pronounced in dairy-free yogurts, meat analogs, and ready-to-eat meals, where functional performance and clean-label claims must coexist.
- For instance, Cargill has demonstrated that citrus fiber ingredients can retain more than 6 grams of water per gram of fiber, supporting juiciness and bite in plant-based meat applications without added emulsifiers.
Sustainability and Upcycling of Food Processing By-products
Sustainability considerations are increasingly shaping ingredient sourcing strategies, driving demand for citrus fibers derived from upcycled fruit-processing waste. Citrus peels, generated in large volumes by the juice industry, offer a renewable and circular raw material stream. Utilizing these by-products reduces food waste, lowers environmental impact, and supports corporate sustainability goals. Food and ingredient manufacturers are actively integrating upcycled inputs into their supply chains to meet environmental, social, and governance (ESG) commitments. Citrus fibers align well with these objectives, enabling brands to communicate sustainability credentials while maintaining functional performance, thereby strengthening their adoption across global food systems.
Key Trends & Opportunities
Growing Adoption in Functional and Fortified Foods
Citrus fibers are increasingly incorporated into functional and fortified food products due to their dietary fiber content and digestive health benefits. Food producers are leveraging citrus fibers to enhance fiber levels while maintaining appealing textures and stability. This trend creates opportunities in breakfast cereals, nutrition bars, beverages, and medical nutrition products, where fiber enrichment is a key differentiator. As consumers become more health-conscious, the demand for multifunctional ingredients that deliver both nutrition and functionality continues to rise, expanding application potential for citrus fibers beyond traditional food categories.
- For instance, Herbafood Ingredients GmbH’s Herbacel® HF citrus fiber contains more than 85 g of dietary fiber per 100 g and demonstrates water-binding capacity above 7 g per gram, enabling fiber enrichment in extruded cereals without texture collapse.
Innovation in Fiber Processing and Customization
Advancements in citrus fiber processing technologies are enabling the development of application-specific grades with tailored particle size, hydration behavior, and functional performance. Ingredient suppliers are increasingly offering customized citrus fiber solutions optimized for specific end uses, such as high-acid beverages or frozen products. This trend opens opportunities for deeper collaboration between suppliers and food manufacturers, supporting product innovation and premium positioning. Enhanced functionality also allows citrus fibers to compete more effectively with established hydrocolloids in complex formulations.
- For instance, CEAMSA’s Citri-Fibre® range includes customized fibers that maintain structural functionality at pH levels as low as 3.0 and withstand pasteurization temperatures above 90°C, making them suitable for acidic sauces and ready meals.
Rising Demand from Emerging Markets
Emerging economies are presenting new growth opportunities as urbanization, income growth, and changing dietary habits drive demand for processed and packaged foods. Food manufacturers in these regions are increasingly adopting natural stabilizers and texturizers to meet evolving consumer preferences. Citrus fibers, supported by expanding local food processing industries, are well positioned to benefit from this transition, particularly in bakery, dairy, and convenience food segments.
Key Challenges
Variability in Raw Material Supply and Quality
One of the primary challenges in the citrus fibers market is variability in raw material availability and quality. Citrus peel supply depends heavily on seasonal fruit production and fluctuations in juice processing volumes. Variations in citrus species, growing conditions, and processing methods can impact fiber composition and functional consistency. Managing this variability requires robust sourcing strategies, quality control systems, and processing expertise, which can increase operational complexity for manufacturers.
Competition from Alternative Natural Hydrocolloids
Citrus fibers face strong competition from other natural hydrocolloids such as pectin, guar gum, locust bean gum, and cellulose-based fibers. These alternatives are well established and widely accepted across food applications. In certain formulations, they may offer more predictable performance or lower formulation costs. Overcoming this challenge requires continuous innovation, performance optimization, and clear communication of citrus fibers’ clean-label and sustainability advantages to differentiate them effectively in a crowded ingredient landscape.
Regional Analysis
North America
North America holds the largest share of the global citrus fibers market at approximately 34%, driven by strong demand for clean-label, non-GMO, and plant-based ingredients. Food manufacturers across the United States and Canada actively incorporate citrus fibers into bakery, sauces, processed meats, and dairy alternatives to replace synthetic stabilizers. High consumer awareness of dietary fiber benefits and well-established food processing infrastructure support sustained adoption. Additionally, the region benefits from advanced ingredient innovation capabilities and a strong presence of functional food brands, reinforcing North America’s leadership position in terms of both volume consumption and application diversity.
Europe
Europe accounts for around 29% of the global citrus fibers market, supported by stringent food additive regulations and strong consumer preference for natural ingredients. The region shows robust demand from bakery, confectionery, and dairy applications, where citrus fibers are used for texture enhancement and fat reduction. Sustainability plays a central role, as European manufacturers increasingly favor upcycled ingredients derived from food-processing by-products. Countries such as Germany, France, Italy, and the UK lead adoption, driven by clean-label reformulation initiatives and high penetration of premium and organic food products across retail and foodservice channels.
Asia-Pacific
Asia-Pacific represents approximately 24% of the global citrus fibers market and is the fastest-growing regional segment. Rising urbanization, expanding middle-class populations, and increasing consumption of packaged and convenience foods are key growth drivers. Citrus fibers are gaining traction in bakery, beverages, and dairy alternatives as manufacturers adopt natural stabilizers to align with evolving consumer preferences. Countries such as China, Japan, South Korea, and India are witnessing growing investment in food processing and ingredient localization. Improving awareness of fiber-enriched foods and expanding plant-based product launches further strengthen regional demand.
Latin America
Latin America holds an estimated 8% share of the global citrus fibers market, supported by the region’s strong citrus production base and expanding food processing sector. Brazil and Mexico are key contributors, benefiting from abundant orange and lemon peel availability from juice processing industries. Citrus fibers are increasingly used in bakery, processed meats, and sauces to improve yield and texture while maintaining cost efficiency. Growing demand for affordable clean-label solutions and gradual adoption of functional food concepts are driving market development, although penetration remains lower compared to North America and Europe.
Middle East & Africa
The Middle East & Africa region accounts for roughly 5% of the global citrus fibers market, reflecting early-stage but steadily growing adoption. Demand is primarily driven by bakery, dairy, and convenience food segments, particularly in the Gulf Cooperation Council countries. Increasing reliance on imported processed foods and gradual expansion of local food manufacturing are supporting citrus fiber usage as natural stabilizers and thickeners. While market penetration remains limited due to lower awareness and formulation complexity, rising health consciousness and modernization of food supply chains are expected to support incremental growth across the region.
Citrus Fibers Market Segmentations:
By Type
- Insoluble
- Soluble
By Form
- Lemon and Lime
- Orange
- Mandarins
- Grapefruits
By Function
- Thickening Agent
- Stabilizer
- Gelling Agent
- Fat Replacement
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the citrus fibers market is characterized by the presence of established ingredient manufacturers and specialized fiber processors competing on functionality, consistency, and clean-label positioning. Leading companies focus on expanding application-specific citrus fiber portfolios to serve bakery, dairy alternatives, sauces, meat products, and plant-based foods. Competitive differentiation is driven by proprietary processing technologies that enhance water-binding capacity, emulsification performance, and texture stability. Players also emphasize secure raw material sourcing from citrus-processing by-products to ensure supply continuity and sustainability credentials. Strategic collaborations with food manufacturers, customized formulation support, and investments in product innovation are common competitive strategies. Additionally, companies are strengthening their regional footprints through capacity expansions and localized production to meet growing demand in Asia-Pacific and emerging markets. Sustainability-focused branding, regulatory compliance, and the ability to replace multiple additives with a single citrus fiber solution remain key factors shaping competitive positioning in the global market.
Key Player Analysis
- Ingredion Incorporated
- CP Kelco
- Cargill
- Herbafood Ingredients GmbH
- CEAMSA
- Carolina Ingredients
- Lemont
- Edge Ingredients
- Nans Products
- Cifal Herbal Pvt. Ltd
Recent Developments
- In June 2025, CEAMSA published detailed insights on CEAMFIBRE citrus fibre emphasizing its multifunctional use from citrus peel, highlighting over 85% total dietary fiber content and broad application versatility in foods such as bakery, dairy, meat products, and beverages, reinforcing its clean-label and sustainable positioning.
- In July 2024, Ingredion launched its FIBERTEX® CF 500 and FIBERTEX® CF 100 citrus fibers, minimally processed ingredients designed to enhance texture, emulsification, and viscosity in clean-label food and beverage applications globally. These multi-benefit fibers support replacement of modified starches and hydrocolloids while maintaining stability in savory, dairy, bakery, and alternative protein systems.
- In May 2024, CP Kelco completed a capacity expansion project for its citrus fiber production facilities, increasing annual production capability to approximately 5,000 tonnes to meet growing industrial demand and strengthen supply for clean-label applications.
Report Coverage
The research report offers an in-depth analysis based on Type, Form, Function and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Citrus fibers will see wider adoption as clean-label reformulation accelerates across processed and packaged food categories.
- Demand will increase in plant-based meat and dairy alternatives due to their ability to improve texture, stability, and mouthfeel.
- Food manufacturers will increasingly use citrus fibers to reduce fat content while maintaining sensory quality in reformulated products.
- Advancements in fiber processing will enable more application-specific citrus fiber grades with improved functional performance.
- Utilization of citrus-processing by-products will strengthen the role of citrus fibers in circular and sustainable food systems.
- Beverage and high-acid food applications will expand as citrus fiber stability and dispersion technologies improve.
- Growing consumer focus on digestive health will support higher inclusion of citrus fibers in functional and fortified foods.
- Adoption will rise in emerging markets as packaged food consumption and clean-label awareness increase.
- Ingredient suppliers will deepen collaboration with food manufacturers to provide customized formulation support.
- Citrus fibers will continue to replace multiple synthetic additives, reinforcing their value as multifunctional natural ingredients.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Citrus fibers, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Citrus fibers market projected to grow between 2024 and 2032?
Which Citrus fibers segment held the largest share in 2024?
What are the primary factors fueling the growth of the Citrus fibers market?
Who are the leading companies in the Citrus fibers market?
Which region commanded the largest share of the Citrus fibers market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Citrus Fiber Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Citrus Fiber Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 334.43 million → 2032: USD 506.67 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Citrus Fiber Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Citrus Fiber Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Citrus Fiber Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Citrus Fiber Market Drivers
- 3.3 Citrus Fiber Market Restraints & Challenges
- 3.4 Citrus Fiber Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Citrus Fiber Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Citrus Fiber Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Citrus Fiber category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Citrus Fiber Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Citrus Fiber Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Citrus Fiber market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Citrus Fiber Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Citrus Fiber Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Citrus Fiber Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Citrus Fiber (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Citrus Fiber Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Citrus Fiber Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Citrus Fiber Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Citrus Fiber Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Citrus Fiber Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Citrus Fiber Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Citrus Fiber Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Citrus Fiber Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Citrus Fiber Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
