
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cloud Security Monitoring and Analytics Tool Market Size 2024 | UUSD 4,300 million |
| Cloud Security Monitoring and Analytics Tool Market, CAGR | 13% |
| Cloud Security Monitoring and Analytics Tool Market Size 2032 | USD 11,594 million |
Market Overview:
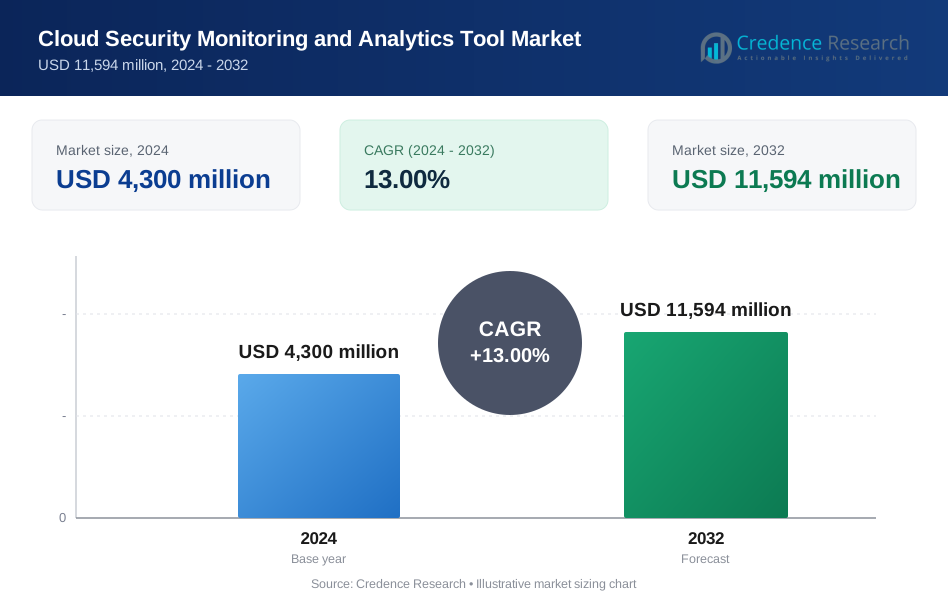
The Cloud Security Monitoring and Analytics Tool Market is projected to grow from USD 4,300 million in 2024 to USD 11,594 million by 2032, expanding at a CAGR of 13% during the forecast period.
The Cloud Security Monitoring and Analytics Tool Market is experiencing significant growth driven by the rising adoption of cloud computing across enterprises, increasing cyber threats, and growing regulatory compliance requirements. Organizations are prioritizing robust security frameworks to safeguard sensitive data, which is accelerating the demand for real-time monitoring and advanced analytics solutions. The integration of artificial intelligence (AI) and machine learning (ML) in security tools is enhancing threat detection and response capabilities, allowing faster identification of anomalies and predictive risk management. Additionally, the growing trend of remote work and the proliferation of IoT devices are expanding the attack surface, necessitating more comprehensive and scalable cloud security solutions. Managed security services and platform-based solutions are gaining traction as companies seek cost-effective and centralized security management. Furthermore, advancements in data visualization and user behavior analytics are improving incident investigation and decision-making processes. These evolving trends collectively propel the market forward, encouraging continuous innovation and investment in cloud-based security technologies.
The Cloud Security Monitoring and Analytics Tool Market demonstrates strong geographical diversity, with North America leading at 41% market share in 2024, followed by Europe at 25%, Asia-Pacific at 20%, and Latin America and the Middle East & Africa collectively accounting for 14%. North America’s growth is fueled by advanced cloud infrastructure and stringent regulatory compliance, while Europe benefits from GDPR-driven security adoption. Asia-Pacific is rapidly expanding due to digital transformation across emerging markets, and Latin America and the Middle East & Africa are gaining momentum through national cybersecurity initiatives. Key players shaping the global landscape include Sumo Logic, IBM, Rapid7, Haystax, Symantec, Aviatrix, McAfee, Argent, BMC Software, Varonis, Check Point Software Technologies, and Compaas, all of which are actively pursuing innovation and strategic expansion across these regions to capture emerging opportunities and address evolving cloud security needs.
Market Insights:
- The Cloud Security Monitoring and Analytics Tool Market is projected to grow from USD 4,300 million in 2024 to USD 11,594 million by 2032, registering a CAGR of 13% over the forecast period.
- Rapid adoption of cloud computing across industries and increasing concerns over data breaches are key drivers boosting the demand for real-time monitoring and advanced analytics tools.
- Integration of AI, machine learning, and automation is significantly enhancing threat detection, anomaly identification, and predictive security responses, fostering innovation in the market.
- Regulatory compliance mandates such as GDPR, HIPAA, and CCPA are pushing organizations to adopt tools that ensure transparency, auditing, and data integrity across cloud infrastructures.
- Managed services and platform-based security solutions are gaining popularity as organizations seek centralized, scalable, and cost-effective security management across hybrid environments.
- Market growth is strongest in North America with 41% share in 2024, followed by Europe (25%), Asia-Pacific (20%), and Latin America & Middle East & Africa combined (14%).
- Key challenges include the complexity of integrating diverse cloud environments and a global shortage of skilled cybersecurity professionals to manage sophisticated tools and evolving threats.
Market Drivers:
Increasing Cloud Adoption Across Industries:
The rapid shift toward digital transformation has led organizations across various industries to increasingly adopt cloud computing solutions. As businesses migrate critical workloads and sensitive data to the cloud, the need for robust cloud security monitoring and analytics tools has become paramount. These tools help enterprises maintain visibility, ensure compliance, and safeguard data across multi-cloud and hybrid environments. For instance, Netflix migrated its infrastructure to Amazon Web Services (AWS) to achieve unparalleled scalability and cost-efficiency, enabling the platform to manage massive data loads and customize content recommendations globally. The scalability, flexibility, and cost-efficiency of cloud platforms further drive their adoption, thereby boosting demand for security solutions capable of adapting to diverse cloud architectures.
Rising Cybersecurity Threats and Sophistication of Attacks:
Cyber threats continue to evolve in complexity and frequency, posing significant risks to organizations operating in the cloud. Threat actors are leveraging advanced techniques such as ransomware, phishing, and zero-day exploits to target cloud infrastructure. In response, businesses are investing in security monitoring and analytics tools that provide real-time threat detection, behavioral analysis, and automated incident response. The ability to detect anomalies and potential breaches proactively is a critical driver behind the growing demand for intelligent cloud security solutions.
Stringent Regulatory and Compliance Requirements:
Regulatory frameworks such as GDPR, HIPAA, and CCPA mandate organizations to implement strong data protection measures and maintain comprehensive audit trails. These compliance requirements are compelling companies to adopt cloud security monitoring and analytics tools that can generate detailed logs, ensure data integrity, and provide reporting capabilities. For instance, Google Cloud supports GDPR and HIPAA compliance through features like encryption of data at rest, access controls limiting data access to authorized personnel, and regular security audits. As regulatory scrutiny intensifies globally, businesses are prioritizing solutions that not only secure their cloud environments but also facilitate compliance with industry standards and legal mandates.
Integration of Advanced Technologies:
The incorporation of artificial intelligence (AI), machine learning (ML), and automation into cloud security tools is significantly enhancing their capabilities. These technologies enable advanced threat prediction, rapid anomaly detection, and real-time response, which are essential for mitigating emerging threats. The integration of AI/ML also supports continuous learning from data patterns, improving the effectiveness of security operations over time. This technological advancement is a key factor driving innovation and adoption within the cloud security monitoring and analytics tool market.
Market Trends:
Adoption of AI and Machine Learning for Threat Detection:
One of the most prominent trends in the Cloud Security Monitoring and Analytics Tool Market is the integration of artificial intelligence (AI) and machine learning (ML) to enhance threat detection and response capabilities. These technologies enable systems to identify unusual patterns, predict potential threats, and automate responses, thus significantly reducing the time required to detect and mitigate security incidents. For instance, Palo Alto Networks provides Cortex XDR, an AI-driven solution that unifies network, endpoint, and cloud analytics, using behavioral analysis and machine learning to uncover suspicious activities and zero-day threats. As cyber threats grow more sophisticated, AI-driven tools are becoming indispensable for organizations seeking to strengthen their cloud security posture.
Growing Popularity of Unified Security Platforms:
Organizations are increasingly seeking unified security platforms that combine monitoring, analytics, incident response, and compliance management into a single solution. This consolidation helps streamline security operations and provides centralized visibility across complex multi-cloud and hybrid environments. By integrating various functionalities, these platforms improve operational efficiency, reduce silos, and enable faster decision-making. The trend toward platform-based solutions is gaining momentum as businesses look for scalable and cost-effective approaches to managing cloud security.
Focus on Real-Time Monitoring and Automation:
The demand for real-time monitoring capabilities is rising as organizations aim to respond to threats more swiftly and effectively. Automated workflows and response mechanisms are being incorporated into security tools to minimize manual intervention and reduce the risk of human error. This trend is particularly important in large-scale cloud environments, where the volume of data and events can be overwhelming. Automation enables timely remediation of threats and supports continuous monitoring for improved threat resilience.
Emphasis on Compliance and Governance:
With an increasing number of regulations governing data protection and cybersecurity, businesses are placing greater emphasis on compliance-driven security monitoring tools. These tools offer built-in features for reporting, auditing, and policy enforcement, helping organizations stay aligned with evolving legal and industry standards. For instance, Drata delivers continuous compliance automation for frameworks like SOC 2, ISO 27001, and GDPR by automatically monitoring controls and centralizing evidence collection for audits. The focus on compliance and governance is expected to remain a key trend as companies navigate the complexities of regulatory landscapes in cloud environments.
Market Challenges Analysis:
Complexity of Cloud Environments and Integration Issues:
One of the most significant challenges facing the Cloud Security Monitoring and Analytics Tool Market is the growing complexity of cloud environments. Organizations increasingly operate across multi-cloud and hybrid cloud infrastructures, which involve a variety of service providers, platforms, and configurations. This diversity creates substantial integration challenges for security tools, as each environment may have unique protocols, data formats, and security policies. Ensuring seamless interoperability and consistent visibility across disparate systems is often difficult, requiring customized solutions and advanced configurations. For instance, CrowdStrike integrated its Falcon Cloud Security platform with Oracle Cloud Infrastructure (OCI) specifically to help organizations break down security silos and gain unified visibility, directly addressing the challenge of managing security across disparate cloud environments. Moreover, legacy systems may not align well with modern cloud-based security tools, adding to the complexity and limiting the scalability of monitoring solutions. As a result, organizations may face delays in deployment, increased costs, and reduced efficiency in their security operations.
Shortage of Skilled Cybersecurity Professionals and Evolving Threat Landscape:
The shortage of skilled cybersecurity professionals remains a critical obstacle for the effective deployment and management of cloud security monitoring and analytics tools. As the demand for cloud security expertise grows, many organizations struggle to find and retain talent capable of handling the sophisticated technologies and rapidly evolving threat landscape. This skills gap can hinder the optimal use of advanced features such as AI-driven analytics, automated response mechanisms, and behavior-based anomaly detection. Furthermore, cyber threats are becoming more sophisticated and unpredictable, with attackers leveraging advanced techniques such as AI-powered malware, deepfakes, and insider threats. Keeping pace with these evolving risks requires continuous updates, proactive monitoring, and strategic investment, which can strain the resources of many businesses, especially small and medium-sized enterprises. The combination of workforce limitations and an increasingly complex threat environment creates significant pressure on organizations to maintain robust cloud security, making this one of the most persistent and pressing challenges in the market.
Market Opportunities:
The Cloud Security Monitoring and Analytics Tool Market presents substantial opportunities driven by the ongoing digital transformation and the global shift toward cloud-first strategies. As organizations continue to migrate critical operations to cloud platforms, the demand for scalable, intelligent security solutions is expected to rise sharply. Emerging markets, particularly in Asia-Pacific and Latin America, offer untapped growth potential due to increasing cloud adoption, growing awareness of cybersecurity risks, and the rapid expansion of small and medium-sized enterprises. These regions are gradually strengthening their regulatory frameworks, prompting businesses to invest in compliance-ready cloud security tools. Additionally, the growing emphasis on secure remote access and hybrid work models creates new avenues for cloud-native monitoring and analytics tools tailored to protect distributed environments.
Another major opportunity lies in the advancement and integration of next-generation technologies such as artificial intelligence (AI), machine learning (ML), and automation into cloud security solutions. Vendors that can offer predictive analytics, autonomous threat detection, and automated incident response are likely to gain a competitive edge. Moreover, industries such as healthcare, finance, and critical infrastructure, which are governed by stringent data protection regulations, continue to seek industry-specific solutions that align with both security and compliance needs. The increasing complexity of cloud environments also opens the door for managed security service providers (MSSPs) to deliver tailored, cost-effective solutions for organizations lacking in-house expertise. As businesses look for unified and intelligent platforms that reduce operational overhead while enhancing visibility and control, the market is poised to benefit from continuous innovation, strategic partnerships, and the growing recognition of cybersecurity as a strategic business priority.
Market Segmentation Analysis:
By Deployment Type:
The Cloud Security Monitoring and Analytics Tool Market is segmented into cloud-based and on-premises deployment types. Cloud-based solutions dominate due to their scalability, flexibility, and cost-effectiveness, especially for enterprises adopting multi-cloud environments. However, on-premises deployment remains relevant for organizations with strict data control and compliance requirements.
By Solution:
The market features a diverse range of solutions, including Security Information and Event Management (SIEM), Network Traffic Analysis (NTA), Cloud Security Posture Management (CSPM), and Cloud Access Security Broker (CASB). SIEM and CSPM are gaining traction for their ability to provide real-time insights and ensure regulatory compliance across cloud infrastructures.
By Service:
Services in this market are categorized into professional services and managed services. Managed services are increasingly preferred by organizations seeking continuous monitoring and expert support without expanding internal teams. Professional services remain essential for deployment, training, and strategy development tailored to specific business security needs.
Segments:
Based on Deployment Type
- Cloud-based
- On-premises
Based on Solution
- Security Information and Event Management (SIEM)
- Network Traffic Analysis (NTA)
- Cloud Security Posture Management (CSPM)
- Cloud Access Security Broker (CASB)
Based on Service
- Professional Services
- Managed Services
Based on End-User
- Healthcare
- Banking, Financial Services, and Insurance (BFSI)
- IT and Telecom
- Retail
- Govement
Based on Deployment Environment
- Public Cloud
- Private Cloud
- Hybrid Cloud
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds the largest share in the Cloud Security Monitoring and Analytics Tool Market, accounting for 41% of the global market in 2024. This dominance is attributed to the presence of major technology companies, advanced cloud infrastructure, and a high level of cybersecurity awareness. The United States leads regional growth due to strict regulatory frameworks such as HIPAA, SOX, and CCPA, which drive the adoption of advanced security solutions. Moreover, early adoption of AI-driven analytics and a mature IT ecosystem continue to support the expansion of cloud-based security tools across various industries, including finance, healthcare, and government.
Europe:
Europe represents 25% of the global market share in 2024, driven by strong data privacy regulations such as the General Data Protection Regulation (GDPR). Countries like Germany, the United Kingdom, and France are leading adopters of cloud security tools, focusing on data sovereignty and compliance. The region emphasizes secure digital infrastructure to support its growing digital economy, which includes e-commerce, online banking, and smart cities. European enterprises are increasingly investing in cloud-native security solutions to address sophisticated threats and comply with strict legal standards.
Asia-Pacific:
Asia-Pacific holds 20% of the market share in 2024 and is considered the fastest-growing region due to the rapid digital transformation across emerging economies. Countries such as China, India, Japan, and South Korea are witnessing increased adoption of cloud services in sectors like telecom, manufacturing, and retail. Government-led cybersecurity initiatives and rising awareness among enterprises are further fueling demand. Additionally, the growing number of startups and small businesses seeking cost-effective, cloud-based security solutions contributes to the region’s market momentum.
Latin America and Middle East & Africa:
Latin America and the Middle East & Africa together account for 14% of the global market share in 2024. In Latin America, countries like Brazil and Mexico are enhancing their cybersecurity capabilities as cloud adoption expands across industries. In the Middle East & Africa, digital initiatives such as smart city projects and national cybersecurity frameworks are creating opportunities for cloud security solution providers. However, limited IT infrastructure and skills gaps remain key challenges. Despite these hurdles, increasing investment in cloud technology is expected to boost regional demand for monitoring and analytics tools in the coming years.
Key Player Analysis:
- Haystax
- Argent
- Symantec
- Compaas
- Rapid7
- BMC Software
- Sumo Logic
- Check Point Software Technologies
- McAfee
- IBM
- Aviatrix
- Varonis
Competitive Analysis:
The Cloud Security Monitoring and Analytics Tool Market is highly competitive, with leading players such as Sumo Logic, IBM, Rapid7, Haystax, Symantec, Aviatrix, McAfee, Argent, BMC Software, Varonis, Check Point Software Technologies, and Compaas driving innovation and market growth. These companies are leveraging advanced technologies including artificial intelligence, machine learning, and automation to enhance their threat detection, response, and compliance capabilities. Strategic initiatives such as product innovation, cloud-native solution development, mergers, and global partnerships are central to maintaining their competitive edge. Additionally, many are focusing on expanding their service portfolios to include managed security and integrated platform offerings to address complex hybrid and multi-cloud environments. Continuous investment in R&D, customer-centric solutions, and scalable security architectures allows these firms to respond swiftly to the evolving cybersecurity landscape. As regulatory requirements tighten and threat actors become more sophisticated, these companies are also prioritizing adaptive analytics and real-time monitoring features to retain market leadership and capture emerging global opportunities.
Recent Developments:
- In March 2025, Rapid7's MDR service enhanced its support for new AWS GuardDuty attack sequence alerts ("Potential Credential Compromise" and "Potential S3 Data Compromise"), providing alert triage, remediation recommendations, and response actions to improve detection of sophisticated cloud attack strategies.
- In June 2023, BMC announced new capabilities focused on mainframe security, particularly hardening defenses against malicious insider threats via BMC AMI Security, which employs automated detection and response for unusual privileged user activity.
- In March 2025, Sumo Logic introduced Sumo Logic Threat Intelligence, allowing Cloud SIEM administrators to import Indicators of Compromise (IoC) files and feeds for security analysis.
- In February 2025, Check Point entered a strategic partnership with Wiz to integrate Check Point's cloud network security with Wiz's Cloud Native Application Protection Platform (CNAPP), aiming for unified insights, enhanced risk context, and optimized security operations.
Market Concentration & Characteristics:
The Cloud Security Monitoring and Analytics Tool Market exhibits a moderately high level of market concentration, with several key players dominating global revenues through strong brand recognition, technological innovation, and strategic partnerships. Companies such as IBM, Sumo Logic, McAfee, and Symantec maintain competitive advantages through extensive product portfolios, global reach, and continuous investments in research and development. The market is characterized by rapid innovation, driven by the integration of artificial intelligence, machine learning, and automation into security solutions. It also demonstrates a strong shift toward cloud-native and platform-based offerings that provide real-time threat detection and centralized visibility. As enterprises increasingly adopt multi-cloud and hybrid architectures, demand is shifting toward scalable, flexible, and integrated security solutions. The market’s dynamic nature is further shaped by regulatory pressures and evolving threat landscapes, encouraging continuous enhancements in security capabilities. Despite the presence of dominant players, emerging vendors and managed service providers are gaining ground through niche offerings and regional specialization.
Report Coverage:
The research report offers an in-depth analysis based on Deployment Type, Solution, Service, End-User, Deployment Environment and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Cloud security tools will increasingly integrate AI and machine learning to enhance predictive threat detection and automated response.
- Enterprises will prioritize unified security platforms that offer centralized visibility across hybrid and multi-cloud environments.
- Regulatory compliance will continue to influence the adoption of advanced monitoring and analytics solutions globally.
- Demand for managed security services will grow as organizations seek expert support and reduced operational burden.
- Real-time data analytics and behavioral monitoring will become standard features in cloud security frameworks.
- Small and medium-sized enterprises will adopt cloud security tools at a faster rate due to scalable and cost-effective solutions.
- Industry-specific security solutions will gain traction, particularly in healthcare, finance, and critical infrastructure sectors.
- Geopolitical tensions and rising cyber warfare risks will drive investment in proactive and resilient cloud security systems.
- Strategic partnerships and mergers among vendors will shape innovation and market expansion.
- Growing use of IoT and edge computing will expand the threat landscape, increasing demand for adaptive cloud security tools.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Cloud Adoption Across Industries
As organizations migrate critical workloads and sensitive data to the cloud for scalability and cost-efficiency, the need for robust cloud security monitoring and analytics tools grows to ensure visibility, compliance, and data protection across multi-cloud and hybrid environments.
Rising Cybersecurity Threats and Attack Sophistication
The increasing frequency and complexity of cyberattacks, including ransomware and zero-day exploits targeting cloud infrastructure, are driving enterprises to invest in advanced monitoring and analytics tools for real-time threat detection and automated incident response.
Stringent Regulatory and Compliance Requirements
Global regulations such as GDPR, HIPAA, and CCPA require organizations to implement strong data protection and auditing measures, compelling adoption of cloud security tools that provide detailed logs, data integrity, and compliance reporting.
Integration of AI, Machine Learning, and Automation
The incorporation of AI and machine learning into cloud security solutions is enhancing threat prediction, anomaly detection, and automated response, making these tools more effective and attractive to organizations seeking proactive security.
Growth of Remote Work and IoT Expansion
The proliferation of remote work and IoT devices has expanded the attack surface, increasing the demand for scalable, real-time cloud security monitoring and analytics solutions capable of protecting distributed and dynamic environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cloud Security Monitoring and Analytics Tool Market?
What factors are driving the growth of the Cloud Security Monitoring and Analytics Tool Market?
What are some challenges faced by the Cloud Security Monitoring and Analytics Tool Market?
Who are the major players in the Cloud Security Monitoring and Analytics Tool Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service
- 1.2.1 Professional Services
- 1.2.2 Managed Services
- 1.3 By End-User
- 1.3.1 Healthcare
- 1.3.2 Banking, Financial Services, and Insurance (BFSI)
- 1.3.3 IT and Telecom
- 1.3.4 Retail
- 1.3.5 Government
- 1.4 By Solution
- 1.4.1 Security Information and Event Management (SIEM)
- 1.4.2 Network Traffic Analysis (NTA)
- 1.4.3 Cloud Security Posture Management (CSPM)
- 1.4.4 Cloud Access Security Broker (CASB)
- 1.5 By Deployment Type
- 1.5.1 Cloud-based
- 1.5.2 On-premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,300 million → 2032: USD 11,594 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cloud Security Monitoring and Analytics Tool Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cloud Security Monitoring and Analytics Tool Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Cloud Security Monitoring and Analytics Tool Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Cloud Security Monitoring and Analytics Tool Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cloud Security Monitoring and Analytics Tool Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cloud Security Monitoring and Analytics Tool Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cloud Security Monitoring and Analytics Tool Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cloud Security Monitoring and Analytics Tool Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,300 million → 2032: USD 11,594 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cloud Security Monitoring and Analytics Tool Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Professional Services
- 12.3.6.2 Managed Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Healthcare
- 12.4.6.2 Banking, Financial Services, and Insurance (BFSI)
- 12.4.6.3 IT and Telecom
- 12.4.6.4 Retail
- 12.4.6.5 Government
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Solution - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Security Information and Event Management (SIEM)
- 12.5.6.2 Network Traffic Analysis (NTA)
- 12.5.6.3 Cloud Security Posture Management (CSPM)
- 12.5.6.4 Cloud Access Security Broker (CASB)
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Cloud-based
- 12.6.6.2 On-premises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cloud Security Monitoring and Analytics Tool End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cloud Security Monitoring and Analytics Tool Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cloud Security Monitoring and Analytics Tool Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cloud Security Monitoring and Analytics Tool Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sumo Logic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 IBM
- 18.4 Rapid7
- 18.5 Symantec
- 18.6 McAfee
- 18.7 Check Point Software Technologies
- 18.8 BMC Software
- 18.9 Varonis
- 18.10 Aviatrix
- 18.11 Haystax
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

