
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Dark Fiber Networks Market Size 2024 | USD 5,779.5 Million |
| Dark Fiber Networks Market, CAGR | 12.32% |
| Dark Fiber Networks Market Size 2032 | USD 14,640.2 Million |
Market Overview
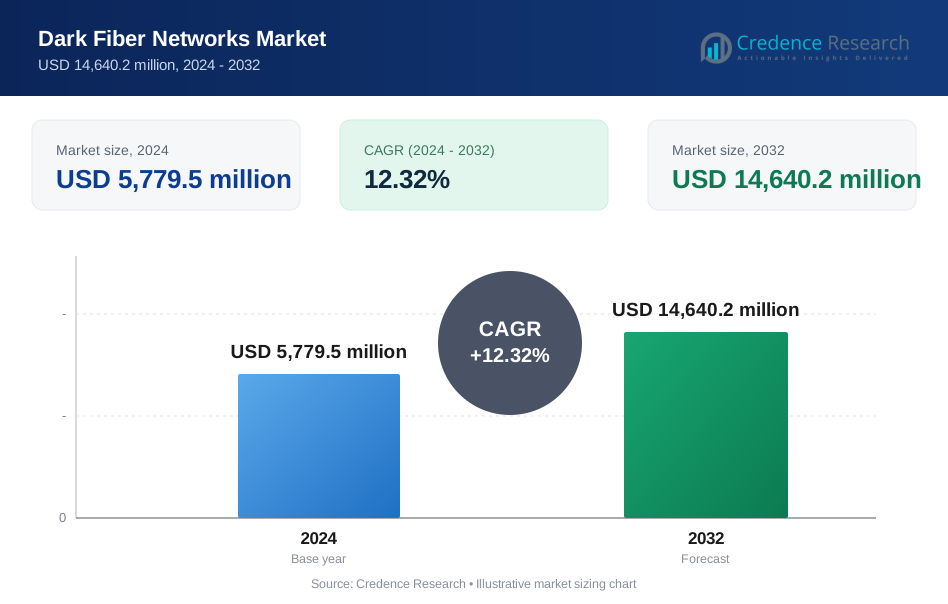
The Dark Fiber Networks Market is projected to grow from USD 5,779.5 million in 2024 to USD 14,640.2 million by 2032, achieving a compound annual growth rate (CAGR) of 12.32%.
The Dark Fiber Networks market is driven by the increasing demand for high-speed connectivity and data transfer, particularly with the growth of cloud computing and data centers. As businesses seek to enhance their network capacity and improve bandwidth, dark fiber provides a cost-effective solution for scalable infrastructure. Additionally, the rise in Internet of Things (IoT) devices and the need for low-latency communication fuel the demand for dark fiber networks. Key trends include partnerships between telecommunications providers and enterprises to expand dark fiber availability and the deployment of advanced technologies to optimize network performance and reliability.
The geographical analysis of the Dark Fiber Networks market reveals significant growth across North America and Europe, driven by increasing demand for high-capacity connectivity and the expansion of data centers. North America holds a substantial market share due to its advanced telecommunications infrastructure and widespread adoption of cloud services. Key players in this market include AT&T, Verizon Communications, and Level 3 Communications (CenturyLink), who are investing heavily in dark fiber infrastructure to meet the needs of enterprises and telecom operators. In Europe, companies like NTT Communications and Colt Application Services are also expanding their dark fiber offerings to enhance connectivity solutions.
Market Drivers
Increasing Bandwidth Demand
The proliferation of data-intensive applications such as video streaming, cloud computing, and IoT is significantly fueling the demand for higher bandwidth. As consumers and businesses increasingly rely on these applications, the need for robust internet connectivity becomes paramount. For instance, the COVID-19 pandemic accelerated the already rapid growth of bandwidth demand across US households, driving unprecedented use of streaming video and video conferencing applications. Additionally, the shift towards remote work and online education has led to a surge in internet usage, further driving the need for high-speed connectivity. This growing bandwidth demand is a primary driver for the expansion of dark fiber networks, as organizations seek reliable and efficient solutions to meet their connectivity needs.
Advancements in Technology
The ongoing rollout of 5G networks necessitates extensive fiber infrastructure, creating substantial demand for dark fiber to support backhaul and fronthaul connections. For instance, the rollout and adoption of fifth-generation (5G) mobile networks have dominated the telecommunications sector in recent years, with forecasts anticipating mobile data traffic of almost 330 exabytes per month by 2028. The deployment of 5G technology enables faster data transmission and improved network capacity, making dark fiber an essential component in this evolution. Furthermore, the rise of edge computing-where processing power is brought closer to data sources-requires high-capacity, low-latency connections. Dark fiber networks can provide the necessary infrastructure to support these technological advancements, ensuring efficient data flow and enhanced performance.
Security and Reliability
Dark fiber networks offer a high level of security, making them particularly suited for applications that require sensitive data transmission. This capability is critical as organizations prioritize data privacy and compliance with regulatory standards. Moreover, dark fiber can be utilized to create redundant networks, significantly enhancing reliability and minimizing downtime. This redundancy ensures that organizations can maintain operational continuity even in the face of unexpected challenges, further reinforcing the appeal of dark fiber solutions.
Scalability and Flexibility
The scalability of dark fiber networks makes them a future-proof investment for businesses. These networks can be easily expanded to accommodate increasing bandwidth demands, allowing organizations to adapt to changing needs without significant overhauls. Additionally, dark fiber provides the flexibility for customization, enabling businesses to tailor their networks to specific requirements. This adaptability ensures optimal performance and cost-effectiveness, making dark fiber an attractive choice for enterprises looking to enhance their connectivity infrastructure.
Market Trends
Expansion of Smart City Initiatives and Focus on Security
Smart city initiatives are also contributing to the increasing demand for dark fiber. These projects require robust communication networks to support various applications, including traffic management, environmental monitoring, and public safety. For instance, the City of Calgary operates around 800 kilometers of fiber at 1,000 locations to support its Smart City program and emergency services. Dark fiber is being deployed as a critical infrastructure component to provide the necessary connectivity for these interconnected systems. In parallel, organizations are placing a greater emphasis on security and reliability in their network solutions. Dark fiber networks are particularly well-suited for applications that require sensitive data transmission due to their high level of security. Furthermore, dark fiber can be utilized to create redundant networks, enhancing reliability and minimizing downtime in the event of disruptions. This focus on security and reliability positions dark fiber as an attractive option for businesses across various sectors.
Emerging Applications and Consolidation Trends
The emergence of new applications and technologies, such as IoT and edge computing, is driving further demand for dark fiber. The growth of IoT devices necessitates high-speed, low-latency connectivity, which dark fiber can readily provide. Additionally, the development of autonomous vehicles requires a reliable and secure communication infrastructure, making dark fiber a potential solution for this evolving sector. Alongside these technological advancements, the dark fiber market is experiencing increased consolidation and partnerships. Companies are actively engaging in mergers and acquisitions to expand their reach and gain market share. Collaborative efforts between network operators, data center providers, and technology companies are becoming more common as they seek to leverage the benefits of dark fiber. This trend not only signifies a growing recognition of the value of dark fiber but also highlights its potential to drive innovation and enhance connectivity in the digital landscape.
Market Challenges Analysis
Economic Downturns and Technological Evolution
Economic downturns can severely impact the dark fiber market, leading to reduced demand for high-bandwidth connectivity. During such periods, businesses may scale back their investments in infrastructure, which can adversely affect the profitability of dark fiber projects. For instance, during economic recessions, companies often delay or reduce the scope of capital-intensive initiatives like constructing new data centers or deploying 5G networks. Alongside these economic challenges, the rapid pace of technological evolution in fiber optics presents its own set of difficulties. As advancements in technology occur at a breakneck speed, keeping up with the latest trends and standards can be daunting for dark fiber providers. This creates a risk of obsolescence for investments made in older dark fiber infrastructure, as newer technologies may render them less competitive. As a result, providers must continually assess their infrastructure and make necessary upgrades to avoid falling behind in an increasingly competitive market. Additionally, the presence of alternative connectivity options, such as wireless technologies and satellite communications, creates further price pressure, squeezing profit margins for dark fiber providers.
High Upfront Costs and Limited Availability
One of the primary challenges facing the dark fiber market is the high upfront costs associated with its infrastructure. The initial investment required for acquiring, deploying, and maintaining dark fiber can be substantial, creating a barrier for many businesses, especially smaller ones. Moreover, navigating regulatory hurdles and obtaining necessary permits can complicate the deployment process, adding to the overall costs. This financial strain may deter potential investors and slow the market's growth. Furthermore, the limited availability of dark fiber in certain geographic regions presents a significant obstacle. In rural areas or underserved markets, the scarcity of infrastructure can hinder access to dark fiber solutions. This issue is exacerbated by intense competition for existing dark fiber infrastructure, which can drive prices up and further restrict availability. Consequently, businesses in these regions may find themselves unable to secure the connectivity they require, limiting their operational capabilities and growth potential.
Market Segmentation Analysis:
By Type:
The dark fiber networks market is primarily segmented by fiber type, which includes Single Mode Fiber, Step-Index Multimode Fiber, and Graded-Index Multimode Fiber. Single Mode Fiber (SMF) is recognized for its ability to transmit data over long distances with minimal signal loss, making it ideal for telecommunications and large enterprise networks. This fiber type is increasingly favored due to the growing demand for high-capacity, low-latency connections. Conversely, Step-Index and Graded-Index Multimode Fibers are suitable for short-distance applications, often used within buildings or data centers. Step-Index Multimode Fiber is known for its simplicity and cost-effectiveness, while Graded-Index Multimode Fiber enhances performance by reducing modal dispersion. As enterprises expand their networking infrastructure, the choice of fiber type becomes critical in ensuring optimal performance and efficiency.
By Application:
The dark fiber networks market is also segmented based on application, which includes data transmission and networking infrastructure. The demand for high-speed data transmission is rising, driven by the proliferation of data-intensive applications, such as cloud computing and IoT. Organizations seek reliable dark fiber solutions to support their growing data transmission needs. Furthermore, networking infrastructure plays a significant role in the adoption of dark fiber networks, as businesses upgrade their existing networks to enhance connectivity and meet the demands of modern technology. Dark fiber provides the necessary bandwidth and scalability, enabling organizations to future-proof their networking capabilities. As industries continue to digitalize and seek efficient solutions for data transmission, dark fiber networks are increasingly recognized as a critical asset in enhancing overall operational performance and maintaining a competitive edge.
Segments:
Based on Type
- Single Mode Fiber
- Step-Index Multimode Fiber
- Graded-Index Multimode Fiber
Based on Application
- Data Transmission
- Networking Infrastructure
Based on End User
- Telecom
- Oil & Gas
- Military & Aerospace
- BFSI
- Others
Based on Network Type
- Metro
- Long-Haul
Based on Material
- Glass
- Plastic
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American region holds a significant share of the dark fiber networks market, accounting for approximately 45% of the global market share. This dominance is attributed to the extensive deployment of advanced telecommunications infrastructure and the rapid adoption of data centers and cloud computing services. The region's robust economic conditions and increasing demand for high-speed connectivity from both enterprises and consumers drive the growth of dark fiber networks. For instance, major telecom operators and technology companies are investing heavily in expanding their dark fiber networks to support the growing demand for bandwidth-intensive applications, including 5G deployment and Internet of Things (IoT) initiatives. As a result, the North American market is poised for substantial growth, with ongoing investments in infrastructure further enhancing its leadership position.
Asia-Pacific
In contrast, the Asia-Pacific region is emerging as a rapidly growing market for dark fiber networks, expected to capture around 30% of the global market share. This growth can be attributed to the increasing digitalization across various sectors, including telecommunications, healthcare, and manufacturing. Countries such as China, India, and Japan are at the forefront of this expansion, driven by government initiatives promoting smart city projects and enhanced broadband connectivity. The demand for reliable and scalable dark fiber networks is also rising as enterprises migrate to cloud-based solutions and seek efficient data transmission methods. Furthermore, the ongoing rollout of 5G networks in the region is creating significant opportunities for dark fiber providers, positioning Asia-Pacific as a critical player in the global dark fiber networks market. The combination of technological advancements and government support will likely drive the continued growth of dark fiber networks in this region.
Key Player Analysis
- AT&T
- Comcast
- GTT Communications, Inc.
- NTT Communications Corporation
- Verizon Communications, Inc.
- Level 3 Communications, Inc. (CenturyLink, Inc.)
- Zayo Group, LLC
- Windstream Communications
- Colt Application Services Group Limited
- Consolidated Communications
- Liberty Global plc
Competitive Analysis
The competitive landscape of the Dark Fiber Networks market is characterized by significant investments and strategic initiatives among leading players, including AT&T, Verizon Communications, Level 3 Communications (CenturyLink), NTT Communications, and Colt Application Services Group Limited. Companies are focused on expanding their fiber optic infrastructure to meet the increasing demand for high-speed, low-latency connectivity. Many players are enhancing their networks through continuous upgrades, partnerships, and innovative technologies to improve performance and security. As the demand for data-intensive applications and cloud services continues to grow, the competitive environment encourages advancements in dark fiber offerings. This enables providers to capitalize on emerging market opportunities, positioning them favorably in the evolving telecommunications sector. With a focus on scalability and reliability, these companies aim to meet the needs of enterprises and data centers seeking robust connectivity solutions.
Recent Developments
- In January 2024, Verizon reported strong fourth-quarter and full-year 2023 results, highlighting growth in wireless customers and fixed wireless services. While not directly related to tablet counting machines, this indicates the company’s focus on expanding its wireless and broadband services.
- In July 2023, Windstream Wholesale announced the introduction of “Regional Rapid Fiber,” a new 400G wave service powered by ZR+ technology. This service is set for network deployment and customer turn-up in early summer 2023. While not specifically about tablet counting machines, this shows Windstream’s focus on advancing optical technology solutions.
- In July 2023, Liberty Global acquired 93.23% of Telenet Group Holding NV and announced plans to reopen its offer on August 24, 2023. This acquisition is not related to tablet counting machines but demonstrates the company’s expansion efforts.
Market Concentration & Characteristics
The market concentration of Dark Fiber Networks is characterized by a mix of established telecom giants and specialized providers. This competitive landscape enables a diverse range of offerings tailored to various customer needs, from large enterprises to small businesses. Major players invest heavily in expanding their fiber optic infrastructure, which often leads to geographical monopolies in specific regions. Additionally, the market features a trend towards consolidation, with mergers and acquisitions aimed at enhancing service capabilities and expanding market reach. The demand for high-capacity, low-latency connectivity fuels competition, compelling providers to innovate continuously. Characteristics such as scalability, customization, and enhanced security distinguish dark fiber services from traditional connectivity solutions, appealing to clients seeking reliable data transmission and networking infrastructure. As businesses increasingly prioritize digital transformation and connectivity, the market is expected to evolve further, promoting competitive dynamics that foster innovation and customer-centric solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User, Network Type, Material and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The dark fiber market is projected to experience significant growth, driven by increasing demand for high-bandwidth applications.
- The deployment of 5G networks will necessitate expanded dark fiber infrastructure to support backhaul and fronthaul connections.
- The rise of edge computing will boost the need for low-latency, high-capacity connections provided by dark fiber.
- More enterprises will adopt dark fiber solutions to enhance their data security and ensure reliable data transmission.
- Smart city initiatives will increase the deployment of dark fiber networks to support connected infrastructure and services.
- Mergers and acquisitions among key players will lead to greater market consolidation and expanded service offerings.
- Advancements in fiber optic technology will enhance the performance and efficiency of dark fiber networks.
- Companies will increasingly leverage dark fiber to meet the growing demands of IoT applications and connected devices.
- Economic factors and regulatory environments will influence investment decisions and infrastructure development.
- Sustainability considerations will drive the development of eco-friendly dark fiber solutions and practices in the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Dark Fiber Networks market?
What factors are driving the growth of the Dark Fiber Networks?
What are the key segments within the Dark Fiber Networks?
What are some challenges faced by the Dark Fiber Networks?
Who are the major players in the Dark Fiber Networks?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dark Fiber Networks Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dark Fiber Networks Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,779.5 million → 2032: USD 14,640.2 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dark Fiber Networks Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dark Fiber Networks Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dark Fiber Networks Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dark Fiber Networks Market Drivers
- 3.3 Dark Fiber Networks Market Restraints & Challenges
- 3.4 Dark Fiber Networks Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dark Fiber Networks Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dark Fiber Networks Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dark Fiber Networks category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dark Fiber Networks Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Dark Fiber Networks Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Dark Fiber Networks. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dark Fiber Networks Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dark Fiber Networks Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Dark Fiber Networks Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dark Fiber Networks (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Dark Fiber Networks
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dark Fiber Networks Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Dark Fiber Networks Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dark Fiber Networks Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dark Fiber Networks Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dark Fiber Networks Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dark Fiber Networks Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dark Fiber Networks Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dark Fiber Networks Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
