
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
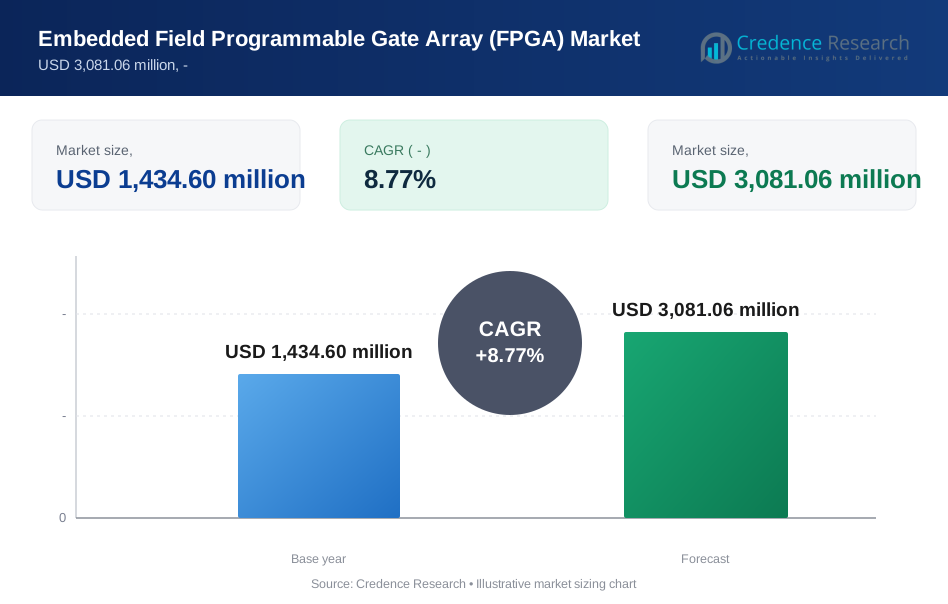
| Embedded Field Programmable Gate Array (FPGA) Market Size 2023 | USD 1,434.60 million |
| Embedded Field Programmable Gate Array (FPGA) Market, CAGR | 8.77% |
| Embedded Field Programmable Gate Array (FPGA) Market Size 2032 | USD 3,081.06 million |
Market Overview:
The Embedded Field Programmable Gate Array (FPGA) market is expected to grow from USD 1,434.60 million in 2024 to USD 3,081.06 million by 2032, registering a robust compound annual growth rate (CAGR) of 8.77% during the forecast period. Embedded FPGAs are gaining significant traction due to their ability to offer high configurability, low power consumption, and improved performance across a wide range of applications, particularly in telecommunications, automotive, industrial automation, and consumer electronics. The rising demand for edge computing and AI acceleration is further contributing to the market's growth, as FPGAs provide flexibility in adapting to new protocols and algorithms without needing to change hardware.
Key market drivers include the growing adoption of embedded FPGAs in automotive electronics for applications like advanced driver assistance systems (ADAS) and autonomous driving, where real-time data processing and adaptability are essential. The telecommunications sector also plays a significant role, as embedded FPGAs are increasingly integrated into 5G infrastructure to meet the high bandwidth and low latency requirements. Furthermore, the trend towards AI and machine learning applications in edge devices is accelerating the demand for embedded FPGAs, as they offer parallel processing capabilities and adaptability in varying use cases.
Regionally, North America dominates the market, holding the largest share due to the presence of leading FPGA manufacturers and early adoption in AI-driven industries such as healthcare and automotive. Asia-Pacific is anticipated to witness the fastest growth during the forecast period, driven by the rapid adoption of 5G technology, industrial automation, and the proliferation of smart devices in countries like China, Japan, and South Korea. Europe also holds a significant market share, with increasing investments in automotive electronics and telecommunications infrastructure contributing to the growth of embedded FPGA adoption.
Market Drivers:
Rising Demand for AI and Machine Learning Applications:
One of the primary drivers of the Embedded FPGA (Field Programmable Gate Array) market is the increasing adoption of artificial intelligence (AI) and machine learning technologies. Embedded FPGAs offer unique advantages in AI applications by enabling real-time data processing and parallel computing, which are essential for AI algorithms. For instance, NVIDIA and Intel have integrated embedded FPGA technology into their AI accelerators to enhance performance in data centers and edge devices. Additionally, government initiatives, such as the U.S. National AI Initiative Act of 2020, have highlighted the importance of advancing AI capabilities, further propelling demand for FPGA solutions.
Growing Adoption in 5G Infrastructure:
The deployment of 5G networks is a significant driver for embedded FPGA adoption, particularly in the telecommunications sector. Embedded FPGAs are being increasingly used in 5G base stations and network infrastructure due to their ability to handle high bandwidth, low latency, and complex signal processing tasks. For example, Xilinx has developed FPGAs specifically optimized for 5G applications, allowing telecom providers to meet evolving demands. Governments are also investing in 5G technology; according to the European Commission, 5G infrastructure investments in Europe are expected to reach EUR 700 billion by 2025, further boosting the demand for embedded FPGAs.
Expanding Role in Automotive Electronics:
The automotive industry is embracing embedded FPGAs to support advancements in advanced driver-assistance systems (ADAS) and autonomous driving. FPGAs' ability to perform real-time data processing and adapt to new protocols makes them ideal for autonomous vehicles, where safety and accuracy are critical. Companies like Tesla and NXP Semiconductors are incorporating FPGA technology into their automotive platforms to improve sensor fusion, navigation, and object detection capabilities. The rising demand for connected cars and electric vehicles further drives FPGA integration in automotive electronics.
Growth in Edge Computing and IoT Devices:
The expansion of edge computing and Internet of Things (IoT) devices is another key driver of the embedded FPGA market. FPGAs offer low-power, flexible computing solutions, enabling real-time data analysis at the edge, which is critical for IoT applications. Companies such as Amazon Web Services (AWS) and Microsoft Azure are adopting FPGAs for cloud-edge computing environments, enhancing performance for IoT and AI workloads. Government initiatives, like the U.K. Industrial Strategy, which promotes the adoption of IoT and smart devices, further contribute to this growing demand.
Market Trends:
Integration with AI Accelerators:
A key trend in the Embedded FPGA (Field Programmable Gate Array) market is its increasing integration with AI accelerators. Companies are embedding FPGA technology into AI systems to improve data processing capabilities in real-time environments. For instance, Intel has developed its Agilex FPGAs, designed to work with AI workloads, offering greater flexibility in machine learning tasks. This trend is particularly evident in data centers and cloud platforms, where real-time AI processing is essential for applications like video analytics and natural language processing. The ability of embedded FPGAs to adapt to new AI algorithms without hardware changes makes them increasingly relevant in this space.
Rising Popularity in Security and Encryption:
Embedded FPGAs are becoming vital in cybersecurity and encryption applications, where their programmability allows for dynamic adaptation to evolving security threats. With an increasing number of data breaches, companies are turning to FPGA technology to safeguard critical information. For instance, Microsoft Azure uses embedded FPGAs to enhance security in its cloud infrastructure, ensuring real-time encryption and decryption of sensitive data. Governments are also prioritizing secure hardware solutions; according to a U.S. Department of Defence report, the demand for secure, programmable hardware for defence applications has risen sharply, with FPGAs playing a central role.
Growth in Reconfigurable Computing:
Another emerging trend is the rise of reconfigurable computing, where FPGAs are used to create adaptable computing systems that can be tailored for specific tasks. This trend is particularly prevalent in industries such as telecommunications and finance, where workload requirements frequently change. Companies like AMD are leveraging FPGAs to offer reconfigurable computing solutions that allow businesses to optimize their hardware for different applications, reducing costs and improving performance. The flexibility offered by embedded FPGAs aligns well with the need for hardware that can adapt to new computing challenges without frequent upgrades.
Expansion in Healthcare Technologies:
The healthcare industry is also recognizing the benefits of embedded FPGAs in advanced medical devices. FPGAs are increasingly being used in medical imaging and diagnostic tools, where real-time data processing and accuracy are critical. Philips Healthcare, for instance, has incorporated FPGA technology into its ultrasound and MRI machines, enhancing imaging speed and quality. The growing adoption of wearable health devices and remote patient monitoring is further driving the demand for embedded FPGAs, as they provide the necessary computational power to handle complex health data in real time.
Market Challenges Analysis:
High Initial Costs and Complexity:
One of the key restraints in the Embedded FPGA (Field Programmable Gate Array) market is the high initial cost of implementation. Designing and integrating embedded FPGAs into devices often require significant investment in both hardware and expertise. For smaller companies, the high cost of development, combined with the specialized knowledge required to program and optimize FPGA-based systems, can create barriers to entry. Moreover, the manufacturing costs associated with FPGA chips, especially in low-volume production, tend to be higher compared to fixed-function ASICs (Application-Specific Integrated Circuits), limiting the widespread adoption of FPGAs in some industries.
Power Consumption and Performance Limitations:
While embedded FPGAs offer flexibility and adaptability, they can sometimes suffer from power inefficiency compared to traditional fixed-function chips. For power-sensitive applications, particularly in mobile and wearable devices, the higher power consumption of FPGAs poses a challenge. This limits their integration into battery-operated devices, where energy efficiency is a key factor. Additionally, although FPGAs are reprogrammable, they often lag behind ASICs in terms of performance for specific tasks, especially in high-volume, performance-critical applications, where customized chips offer better optimization.
Limited Expertise and Programming Complexity:
Another challenge in the embedded FPGA market is the complexity of programming and the limited pool of skilled developers. Designing systems that can take full advantage of FPGA’s reconfigurability requires specialized knowledge in hardware description languages (HDLs) like Verilog and VHDL, which are not as widely used as software programming languages. This steep learning curve creates a talent gap, making it difficult for organizations to effectively adopt and utilize FPGAs without the necessary expertise. The lack of standardization and more intuitive design tools further adds to the challenge, slowing down the rate of adoption in less technical industries.
Market Segmentation Analysis:
By Type, the market is divided into low-end, mid-end, and high-end FPGAs. High-end FPGAs are designed for complex applications like AI acceleration and telecommunications infrastructure, where high performance and adaptability are critical. Mid-end FPGAs are utilized in industrial automation and automotive applications, offering a balance between cost and performance. Low-end FPGAs cater to simpler, cost-sensitive applications in consumer electronics and IoT devices.
By Technology, the market includes SRAM-based, Flash-based, and Antifuse-based FPGAs. SRAM-based FPGAs dominate due to their reconfigurability and flexibility, particularly in telecommunications and data centers. Flash-based FPGAs offer non-volatility and lower power consumption, making them ideal for automotive and aerospace applications, where reliability is paramount. Antifuse-based FPGAs are used in highly secure and radiation-hardened environments like defence and space exploration.
By End User, the market serves industries such as telecommunications, automotive, aerospace, healthcare, and consumer electronics. The telecommunications sector is a significant consumer of embedded FPGAs, driven by the deployment of 5G infrastructure and the need for high-speed data processing. The automotive industry is also a growing segment, leveraging embedded FPGAs for advanced driver-assistance systems (ADAS) and autonomous driving applications. Healthcare and aerospace sectors are increasingly adopting FPGAs for real-time data processing in imaging and sensor fusion.
Segmentation:
By Technology
- EEPROM
- Antifuse
- SRAM
- Flash
- Others
By Application
- Data Processing
- Consumer Electronics
- Industrial
- Military & Aerospace
- Automotive
- Telecom
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the Embedded FPGA (Field Programmable Gate Array) market, accounting for approximately 40% of the global market. This dominance is driven by the region’s early adoption of advanced technologies such as AI, machine learning, and 5G infrastructure. In the United States, key industries like automotive, aerospace, and telecommunications are integrating embedded FPGAs into their systems to improve performance and flexibility. Major FPGA manufacturers such as Intel and Xilinx (a subsidiary of AMD) are headquartered in the U.S., providing the region with a competitive edge. The U.S. government’s focus on defence and cybersecurity also contributes significantly to the growth, with embedded FPGAs being critical in real-time data processing for defence applications.
Europe
Europe accounts for around 25-30% of the global Embedded FPGA market, with countries like Germany, France, and the United Kingdom leading adoption. The region’s strong focus on automotive electronics and industrial automation drives the demand for embedded FPGAs. In particular, Germany, known for its automotive innovations, has been leveraging embedded FPGAs for autonomous vehicles and advanced driver-assistance systems (ADAS). Additionally, telecommunications companies in Europe are incorporating FPGAs in their 5G networks, enhancing network infrastructure for faster and more efficient data transmission. The European Union’s emphasis on sustainable technologies also supports the use of embedded FPGAs in renewable energy systems, further boosting regional demand.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the Embedded FPGA market, contributing around 20-25% of the global share. This growth is fueled by the rapid adoption of 5G technology and the proliferation of consumer electronics in countries like China, Japan, and South Korea. China, in particular, is investing heavily in telecommunications infrastructure and smart manufacturing, where embedded FPGAs are integral to improving operational efficiency. Japan is also leveraging FPGA technology in robotics and automotive applications, while South Korea continues to expand its use of FPGAs in semiconductor manufacturing and AI-driven innovations. The region’s strong industrial base and government-backed initiatives in technology are accelerating the demand for embedded FPGAs.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively account for approximately 5-10% of the global Embedded FPGA market. Although smaller in market share, these regions are experiencing steady growth due to increasing investments in industrial automation and telecommunications infrastructure. Brazil and Mexico are leading in Latin America, where embedded FPGAs are being used in manufacturing and energy sectors. In the Middle East, countries like Saudi Arabia are integrating FPGA technology into oil and gas operations, while South Africa is focusing on expanding telecommunications networks. Government initiatives aimed at diversifying economies and improving technology adoption are expected to drive further growth across these regions.
Key Player Analysis:
- Intel Corporation (through its acquisition of Altera)
- Xilinx, Inc. (a subsidiary of AMD)
- Achronix Semiconductor Corporation
- Microchip Technology Inc.
- Lattice Semiconductor Corporation
- QuickLogic Corporation
- Flex Logix Technologies, Inc.
- Mentor Graphics (a Siemens business)
- Menta SAS
- Syntiant Corp.
Competitive Analysis:
The Embedded FPGA (Field Programmable Gate Array) market is highly competitive, with several key players driving innovation and market growth. Intel and Xilinx (AMD) dominate the market, offering a wide range of advanced FPGA solutions for industries like telecommunications, automotive, and aerospace. Achronix Semiconductor and Lattice Semiconductor are also prominent competitors, focusing on high-performance, low-power FPGA solutions for data centers, AI, and edge computing. Companies like Flex Logix and Menta are gaining traction by specializing in embedded FPGA technology for AI acceleration and reconfigurable computing. Additionally, QuickLogic and Microchip Technology are key players providing cost-effective, low-power FPGAs for IoT and industrial applications. The competitive landscape is characterized by continuous investment in research and development, partnerships, and an emphasis on enhancing FPGA performance and adaptability across various sectors.
Recent Developments:
- Intel Corporation launched Altera as an independent company in March 2024, focusing on opportunities in sectors such as cloud, network, and edge computing. The launch aims to capture new market potential, with a focus on FPGA applications across various industries.
- In October 2023, Achronix Semiconductor Corporation partnered with ai to introduce an accelerated automatic speech recognition (ASR) solution using their Speedster7t FPGA. This technology enables real-time speech-to-text conversion across over 1,000 concurrent streams, with a 20-fold improvement in performance.
- Lattice Semiconductor introduced the CrossLinkU-NX FPGA family in September 2023, the industry’s first FPGA with integrated USB device functionality. This product targets sectors such as computing, industrial, and automotive, enhancing system design with built-in USB controller capabilities.
- Microchip Technology launched a mid-range industrial edge stack in June 2023, designed to assist industrial users with cryptography and secure boot libraries for FPGA designs, further expanding its presence in the industrial and automotive
Market Concentration & Characteristics:
The Embedded FPGA (eFPGA) market is moderately concentrated, with a few dominant players driving innovation and competition. Major companies such as Intel, Xilinx (AMD), and Achronix Semiconductor lead the market due to their advanced technology offerings and significant investments in research and development. These key players hold a competitive edge through their ability to cater to industries like telecommunications, automotive, and aerospace, where embedded FPGAs are critical for high-performance computing and adaptability. Additionally, smaller companies like Flex Logix and Lattice Semiconductor are gaining market traction by focusing on cost-effective and power-efficient solutions for industrial and IoT applications. The market is characterized by a strong emphasis on innovation, with continuous advancements in AI acceleration, edge computing, and 5G infrastructure, making embedded FPGAs essential for a wide range of applications.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The adoption of Embedded FPGAs (eFPGAs) will continue to expand in AI and machine learning applications due to their flexibility and real-time processing capabilities.
- The 5G infrastructure rollout will drive significant demand for eFPGAs, especially in base stations and network devices where low latency and high performance are crucial.
- Automotive electronics, particularly in autonomous driving and ADAS systems, will increasingly rely on eFPGA technology for real-time data processing and adaptability.
- Edge computing will see broader implementation of eFPGAs, as they provide efficient, low-power solutions for processing data closer to the source in IoT devices.
- Growing adoption of reconfigurable computing will enhance the role of eFPGAs in sectors such as telecommunications, finance, and industrial automation.
- Security and encryption applications will continue to benefit from eFPGAs, with increasing use in cybersecurity and secure communications.
- The development of next-generation AI accelerators will be supported by eFPGAs, enabling greater customization and performance optimization in data centers.
- Healthcare and medical devices will integrate eFPGAs into imaging and diagnostic equipment for faster and more accurate data processing.
- The ongoing shift towards sustainable technologies will push eFPGA adoption in industries seeking to reduce energy consumption and material waste.
- Government and defence sectors will continue to invest in eFPGAs for applications requiring secure, real-time processing, such as radar systems and satellite communications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Embedded FPGA Market?
What factors are driving the growth of the Embedded FPGA market?
What are some challenges faced by the Embedded FPGA market?
Who are the major players in the Embedded FPGA Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Embedded Field Programmable Gate Array (FPGA) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Embedded Field Programmable Gate Array (FPGA) Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 1,434.60 million → forecast year: USD 3,081.06 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Embedded Field Programmable Gate Array (FPGA) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Embedded Field Programmable Gate Array (FPGA) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Embedded Field Programmable Gate Array (FPGA) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Embedded Field Programmable Gate Array (FPGA) Market Drivers
- 3.3 Embedded Field Programmable Gate Array (FPGA) Market Restraints & Challenges
- 3.4 Embedded Field Programmable Gate Array (FPGA) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Embedded Field Programmable Gate Array (FPGA) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Embedded Field Programmable Gate Array (FPGA) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Embedded Field Programmable Gate Array (FPGA) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Embedded Field Programmable Gate Array (FPGA) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Embedded Field Programmable Gate Array (FPGA) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Embedded Field Programmable Gate Array (FPGA) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Embedded Field Programmable Gate Array (FPGA) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Embedded Field Programmable Gate Array (FPGA) Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Embedded Field Programmable Gate Array (FPGA) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Embedded Field Programmable Gate Array (FPGA) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Embedded Field Programmable Gate Array (FPGA) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Embedded Field Programmable Gate Array (FPGA) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Embedded Field Programmable Gate Array (FPGA) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Embedded Field Programmable Gate Array (FPGA) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Embedded Field Programmable Gate Array (FPGA) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Embedded Field Programmable Gate Array (FPGA) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Embedded Field Programmable Gate Array (FPGA) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Embedded Field Programmable Gate Array (FPGA) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Embedded Field Programmable Gate Array (FPGA) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
