
Market Overviews
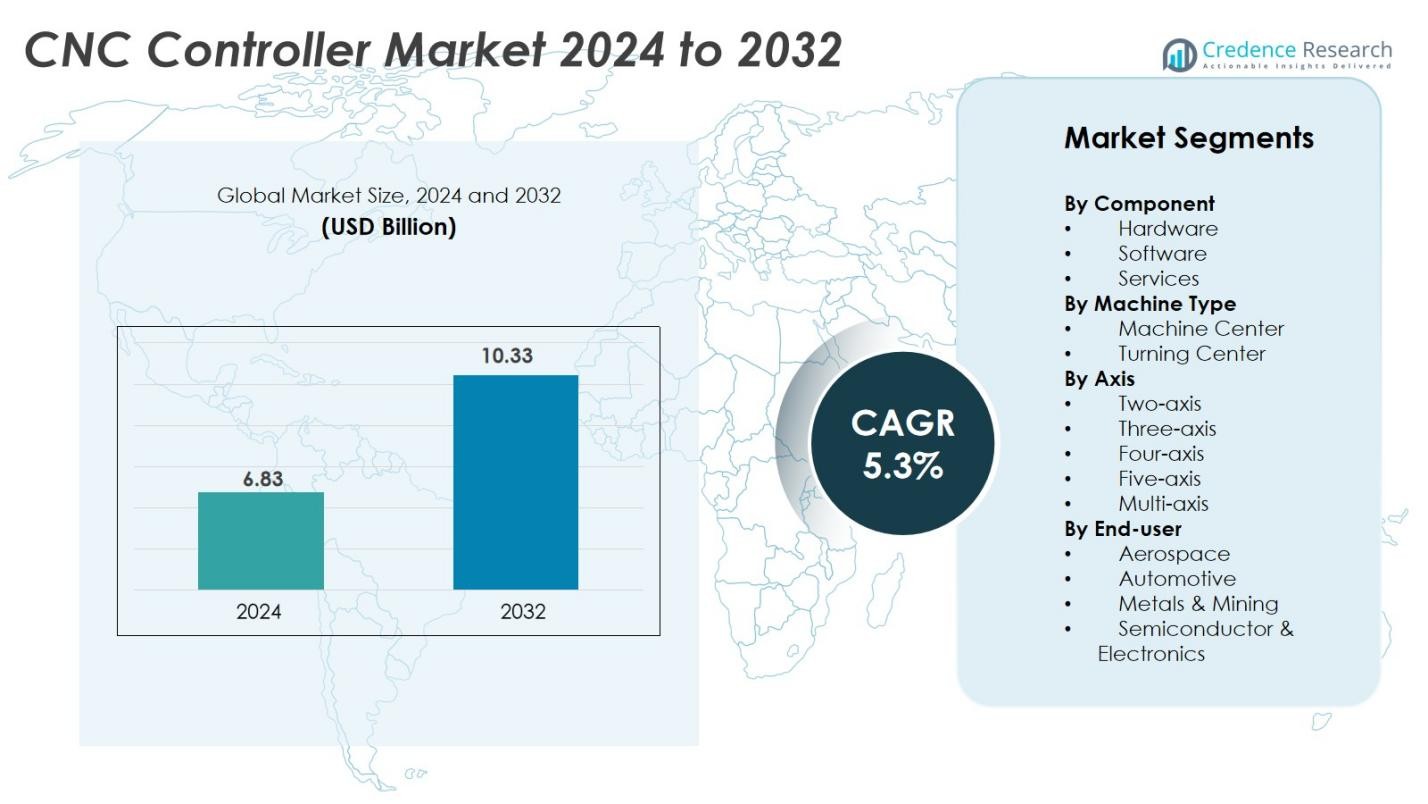
CNC Controller market size was valued USD 6.83 Billion in 2024 and is anticipated to reach USD 10.33 Billion by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| CNC Controller Market Size 2024 | USD 6.83 Billion |
| CNC Controller Market, CAGR | 5.3% |
| CNC Controller Market Size 2032 | USD 10.33 Billion |
The CNC Controller Market is dominated by key players such as Mitsubishi Electric Corporation, FANUC Corporation, Siemens AG, Bosch Rexroth AG, Heidenhain Corporation, NUM Group, Okuma Corporation, HAAS Automation Inc., Hurco Companies Inc., and Fagor Automation. These companies compete through advanced multi-axis controllers, high-speed processing, and software-driven automation features that support smart factory operations. Product strategies focus on precision machining, cloud connectivity, predictive maintenance, and retrofit-ready platforms to upgrade legacy equipment. Asia-Pacific leads the market with over 45% share, driven by strong machine tool production, rapid industrial automation, and large-scale manufacturing in automotive, electronics, and metalworking sectors.
Market Insights
- The CNC controller market reached USD 6.83 Billion in 2024 and is projected to hit USD 10.33 Billion by 2032 at a 5.3% CAGR.
- Rising demand for automation in automotive, aerospace, and precision engineering drives strong adoption of CNC-controlled machining centers and multi-axis systems.
- Key trends include digital retrofitting of aging equipment, cloud-based monitoring, and integration of AI for real-time toolpath optimization and predictive maintenance.
- Competition is shaped by Mitsubishi Electric, FANUC, Siemens, Bosch Rexroth, and HAAS Automation, with companies upgrading hardware, motion control, and software platforms to support Industry 4.0.
- Asia-Pacific leads with over 45% market share, supported by large machine tool manufacturing bases and investments in smart factories, while hardware remains the dominant component with above 60% share, driven by controller upgrades and new installations.
Market Segmentation Analysis
By Component
Hardware holds the dominant position in the CNC controller market, accounting for over 60% share. Controllers, servo drives, and motors form the core of CNC machine functionality, making hardware indispensable for accuracy, rigidity, and high-speed machining. Rising deployment of automated milling, cutting, and grinding machines in automotive and aerospace plants strengthens demand. Software and services show steady growth as factories add programming platforms, remote diagnostics, and predictive maintenance. However, hardware remains the clear leader due to mandatory replacement cycles and continuous upgrades in high-volume production facilities.
- For instance, FANUC's Series 30i/31i/32i Model B controllers are widely adopted in automotive and aerospace milling operations, enabling high accuracy and rigidity.
By Machine Type
Machine centers lead the segment with more than 65% market share, supported by their ability to perform milling, drilling, and cutting in a single setup. These machines allow unattended, continuous machining, which lowers production time and operational cost across automotive, metal fabrication, and precision engineering. Turning centers grow steadily as powertrain and shaft machining rises, but machine centers stay ahead due to their flexibility with three-axis and five-axis configurations. Their higher throughput and capability to manufacture complex geometries continue to drive large-scale industrial adoption.
- For instance, Mazak’s Variaxis i-700 five-axis machining center allows simultaneous precision machining of automotive transmission components, enhancing operational efficiency and minimizing manual intervention.
By Axis
Three-axis CNC machines dominate this segment, holding above 50% share, driven by extensive use in metal fabrication, woodworking, furniture, and plastic molding. They offer a cost-efficient balance of precision and speed, making them ideal for mid-complexity components in automotive, consumer electronics, and packaging industries. Two-axis machines continue to serve basic lathe operations, whereas demand for five-axis and multi-axis systems accelerates in aerospace, mold making, and medical implants. Despite the growth of advanced machining, three-axis controllers maintain the lead due to wide affordability and easy integration for small and medium manufacturers.
Key Growth Drivers
Rising Demand for Industrial Automation Across Manufacturing
Industrial automation remains the strongest driver for the CNC controller market as manufacturers move toward fully automated and precision-driven production. Automotive, aerospace, and metal fabrication plants increase CNC integration to boost accuracy, repeatability, and output consistency. Faster production cycles reduce labor dependency and downtime, while multi-axis machining supports complex designs at scale. The rising shift from manual processes to automated cutting, drilling, and milling drives controller deployments in both new installations and retrofits. Small and medium manufacturers also adopt CNC to improve part quality and reduce scrap rates.
- For instance, Mitsubishi Electric’s M800 series CNC controllers are widely adopted in Asian automotive and metal cutting industries for their high-speed and high-accuracy processing.
Rapid Growth of Multi-Axis and High-Precision Machining
The demand for high-accuracy machining supports strong adoption of five-axis and multi-axis CNC controllers. These systems help produce intricate components for aerospace structures, turbine blades, defense parts, medical implants, and automotive molds. Multi-axis control reduces setup time, improves tolerances, and enables machining from multiple angles without repositioning. Manufacturers value shorter lead times, precision in complex geometries, and reduced material wastage. Growing investments in aerospace and electric vehicle production further strengthen multi-axis implementation. Precision machining also rises in medical manufacturing as CNC supports titanium, stainless steel, and polymer implant shaping with tight tolerances. As innovation advances, controller suppliers introduce real-time tool monitoring, adaptive feed control, and AI-based error prevention to improve machining efficiency and tool life.
- For instance, Lockheed Martin employs true 5-axis simultaneous machining in aerospace R&D for parts like landing gear, allowing intricate geometry machining in one setup without repositioning.
Increased Retrofits and Digitalization of Legacy Equipment
Retrofitting older machines with modern CNC controllers presents a major growth avenue, driven by cost efficiency and sustainability goals. Many factories extend the life of existing mechanical systems by upgrading controls, drives, and software instead of buying new equipment. Retrofitted CNC units improve spindle control, speed, toolpath accuracy, and diagnostics, bringing outdated line operations closer to smart factory standards. Predictive maintenance, real-time data capture, and remote troubleshooting help manufacturers reduce unplanned downtime and improve asset utilization. Adoption grows especially in small and mid-sized workshops that seek automation without heavy capital investment. In addition, digital retrofits support IoT connectivity, allowing operators to track machine health and performance.
Key Trends & Opportunities
Expansion of Connected CNC and Cloud-Based Monitoring
CNC controllers increasingly integrate IoT, cloud analytics, and edge computing to support connected machining. Factories adopt smart CNC systems that track tool wear, energy use, and spindle performance in real time. Cloud-based platforms analyze machine data and optimize production schedules, enabling predictive maintenance and continuous improvement. Remote monitoring becomes valuable in multi-plant operations, reducing on-site service needs and enabling centralized control. The trend aligns with smart factory adoption, offering machine-level intelligence and reduced downtime. Controller manufacturers invest in sensors, digital twins, and AI-based optimization to capture this emerging opportunity in high-volume and precision machining facilities.
- For instance, MachineMetrics uses IIoT sensors and edge computing to track real-time machine condition data, allowing manufacturers to set automatic alerts for maintenance before downtime occurs, improving overall equipment effectiveness.
Growing Penetration of CNC in Small and Medium Enterprises
Cost-efficient controller models, modular hardware, and simplified programming software support CNC adoption in small and medium enterprises. SMEs use CNC to improve accuracy, reduce scrap, and shorten delivery timelines for custom parts and low-batch production. Affordable three-axis and compact machining centers attract woodworking, furniture, signage, and consumer goods producers. The rise of digital training platforms, operator-friendly HMIs, and cloud programming widens accessibility. Government programs that promote local manufacturing, export capacity, and skill development further accelerate SME integration. The shift also creates opportunities for retrofit specialists and service providers offering cost-effective automation upgrades.
- For instance, CubeBOX, a modular digital twin solution designed to integrate with legacy machines in SMEs incrementally, enabling gradual adoption of advanced monitoring without full system overhaul.
Key Challenges
High Initial Investment and Integration Cost
Despite clear operational advantages, CNC controllers require substantial capital investment in hardware, software, and skilled installation. Many small manufacturers find cost barriers difficult, especially when upgrading to multi-axis or high-speed systems. Integration into existing workflows can also require downtime, facility redesign, or operator retraining. Advanced controllers with AI-based monitoring and IoT connectivity add licensing costs and subscription fees. These financial challenges slow adoption in cost-sensitive sectors and emerging manufacturing economies. Vendors respond by offering leasing models, modular upgrades, and retrofit kits, but high upfront expense remains a key constraint for widespread deployment.
Shortage of Skilled CNC Programmers and Maintenance Experts
The CNC controller market faces a global skill gap, as factories struggle to hire experienced programmers, operators, and maintenance specialists. Complex multi-axis machining demands advanced G-code knowledge, tooling expertise, and familiarity with CAD/CAM platforms. Without trained staff, manufacturers experience slower setup times, higher scrap rates, and machine downtime. This skill shortage impacts both large and small plants, especially in regions with limited technical training infrastructure. Controller vendors introduce operator-friendly HMIs, automated toolpath generation, and online training modules to reduce dependency on specialized staff. However, workforce readiness remains a significant challenge for scaling CNC adoption in high-growth manufacturing markets.
Regional Analysis
Asia-Pacific
Asia-Pacific holds the largest share of the CNC controller market, accounting for over 45% of global revenue. China, Japan, South Korea, and India drive strong demand due to rapid industrial automation, expanding automotive production, and growth in metalworking industries. Government initiatives encouraging smart factories and robotics adoption accelerate CNC deployment across manufacturing clusters. Local machine tool manufacturers and competitive pricing increase accessibility for small and medium enterprises. The region also benefits from strong export activity in machinery and precision components. Rising investments in aerospace, EV manufacturing, and electronics further strengthen regional dominance.
North America
North America commands more than 25% of the CNC controller market, supported by advanced aerospace, defense, and automotive manufacturing. The United States leads adoption with high demand for multi-axis machining and high-precision metal fabrication. Strong investments in automation, retrofits, and Industry 4.0 projects modernize production lines in automotive parts and industrial machinery plants. Technological leadership in cloud monitoring, digital twins, and predictive maintenance platforms promotes next-generation CNC upgrades. Demand for medical devices and customized engineered components also contributes to market growth. Supportive manufacturing policies and reshoring activities keep CNC adoption strong across major industries.
Europe
Europe accounts for around 20% of market share, driven by strong machine tool production in Germany, Italy, and Switzerland. The region focuses on precision engineering, aerospace, renewable energy, and industrial automation, which require high-performance CNC systems. Adoption of five-axis and multi-axis machining continues to expand in toolmaking and automotive component production. Government support for digital transformation and energy-efficient manufacturing also boosts modernization of existing facilities. European manufacturers emphasize sustainability, resulting in rising demand for retrofits and CNC upgrades to reduce waste and improve efficiency. Strong exports of industrial machinery further reinforce the region’s position.
Latin America
Latin America secures below 7% of global market share, with growth concentrated in Brazil and Mexico. Rising adoption of CNC systems in automotive parts, metal fabrication, and industrial equipment manufacturing supports gradual expansion. Multinational manufacturers establish production bases in Mexico to supply North American markets, leading to increased demand for automated machining centers. Local industries modernize production lines to improve output quality and reduce labor-intensive processes. However, high import costs and limited access to skilled operators slow widespread adoption. The market continues to grow as SMEs invest in cost-efficient controllers and refurbished CNC systems.
Middle East & Africa
The Middle East & Africa holds under 5% of market share but shows steady growth driven by industrial diversification and infrastructure development. GCC countries invest in aerospace, automotive parts, metal fabrication, and renewable energy projects, creating demand for precision machining. Construction equipment and oil-and-gas component manufacturers adopt CNC systems to improve reliability and reduce import reliance. South Africa leads regional adoption, supported by mining equipment manufacturing and aerospace component machining. Limited local machine tool production and dependence on imported systems create cost barriers, yet ongoing industrial expansion strengthens long-term opportunities.
Market Segmentations:
By Component
- Hardware
- Software
- Services
By Machine Type
- Machine Center
- Turning Center
By Axis
- Two-axis
- Three-axis
- Four-axis
- Five-axis
- Multi-axis
By End-user
- Aerospace
- Automotive
- Metals & Mining
- Semiconductor & Electronics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The CNC controller market features strong competition among global automation leaders and specialized machine tool manufacturers, including FANUC Corporation, Hurco Companies, Inc., HAAS AUTOMATION, INC., Siemens AG, Mitsubishi Electric Corporation, and Bosch Rexroth AG. Companies focus on precision control, real-time monitoring, multi-axis capability, and software integration to differentiate their portfolios. Major players offer modular controllers, compact drive systems, and cloud-connected platforms to support smart factory adoption. They also expand through partnerships with OEM machine builders, robotics suppliers, and CAD/CAM software providers. Product upgrades emphasize faster processing, vibration control, and adaptive feed optimization. Retrofitting solutions gain strategic importance as manufacturers modernize legacy equipment. Firms invest in training services and digital programming tools to address the industry skill gap. Price competition increases in emerging economies, where cost-efficient, mid-range controllers attract small and medium enterprises. Leading companies adopt localization of production and service centers to shorten delivery timelines and strengthen after-sales support.
Key Player Analysis
- FANUC Corporation
- Hurco Companies, Inc.
- HAAS AUTOMATION, INC.
- Siemens AG
- Mitsubishi Electric Corporation
- Bosch Rexroth AG
- NUM Group
- Okuma Corporation
- Heidenhain Corporation
- Fagor Automation Corporation
Recent Developments
- In May 2024, Fagor Automation and GEKA announced a collaboration to advance the digitalization of production processes with the Fagor Digital Suite. This modular platform is designed to enhance manufacturing processes, including those involving CNC controllers.
- In March 2024, FANUC America Corporation introduced its new combined PLC/CNC motion controller, the Power Motion i-MODEL A Plus (PMi-A Plus), at MODEX 2024 in Atlanta, Georgia (booth B-4026). The PMi-A Plus allows users to operate FANUC controls for general motion control applications.
- In September 2023, ESAB introduced its Vision T6 CNC controller, a next-generation solution for automated plasma and oxy-fuel cutting machines. Its user-friendly interface, similar to a smartphone or tablet, makes it easy to operate while improving cutting efficiency.
- In August 2023, the OSP-P500 was launched to improve user experiences and optimize modern manufacturing operations. Featuring dual-core processors for enhanced machine processing power, Digital Twin Technology for precise machining simulations, and strong data protection measures, it is designed for advanced performance.
Report Coverage
The research report offers an in-depth analysis based on Component, Machine Type, Axis, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for multi-axis CNC systems will rise as manufacturers produce complex and high-precision components.
- Retrofitting of old machines with modern CNC controllers will increase across small and medium industries.
- Cloud-enabled CNC monitoring and predictive maintenance will become standard in smart factories.
- Integration of AI and digital twins will enhance toolpath accuracy and reduce machining errors.
- Adoption of CNC systems will grow in EV manufacturing, medical implants, and aerospace parts production.
- User-friendly programming interfaces will reduce skill barriers and expand CNC usage in SMEs.
- Controller makers will focus on energy-efficient hardware and faster real-time processing.
- Compact and modular CNC systems will gain traction in workshops with space and cost constraints.
- Service-based business models and subscription software will increase vendor revenue streams.
- Asia-Pacific will continue leading market expansion due to strong machine tool production and industrial automation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for CNC Controller market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the CNC Controller market projected to grow between 2025 and 2032?
Which CNC Controller market segment held the largest share in 2024?
What are the primary factors fueling the growth of the CNC Controller market?
Who are the leading companies in the CNC Controller market?
Which region commanded the largest share of the CNC Controller market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 CNC Controller Market Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global CNC Controller Market Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6.83 Billion → 2032: USD 10.33 Billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 CNC Controller Market Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. CNC Controller Market Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 CNC Controller Market Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 CNC Controller Market Market Drivers
- 3.3 CNC Controller Market Market Restraints & Challenges
- 3.4 CNC Controller Market Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 CNC Controller Market Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 CNC Controller Market Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, CNC Controller Market category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 CNC Controller Market Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. CNC Controller Market Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the CNC Controller Market market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 CNC Controller Market Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 CNC Controller Market Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 CNC Controller Market Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in CNC Controller Market (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New CNC Controller Market Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global CNC Controller Market Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America CNC Controller Market Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe CNC Controller Market Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific CNC Controller Market Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America CNC Controller Market Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East CNC Controller Market Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa CNC Controller Market Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. CNC Controller Market Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
