
Hybrid Electric Vehicle Market Overview:
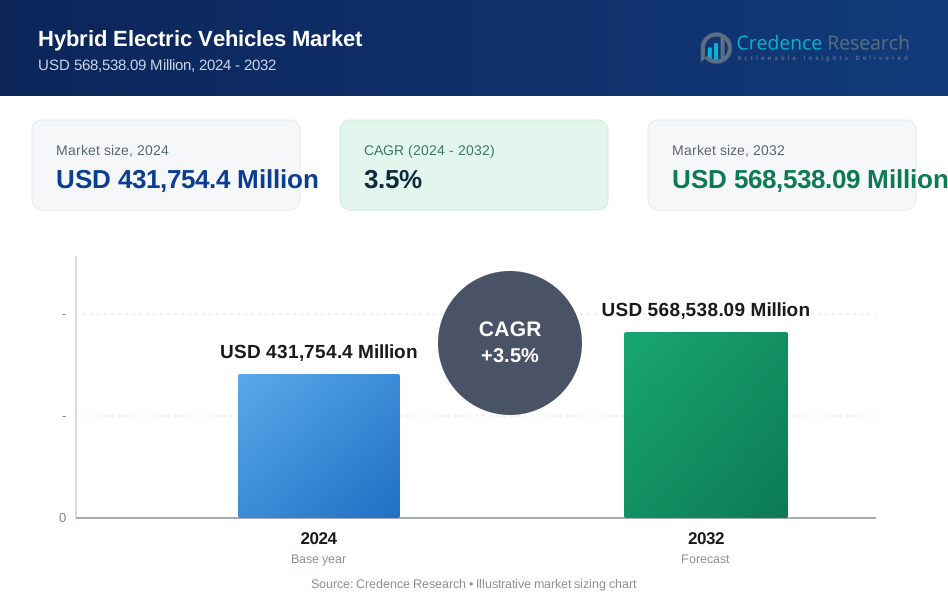
Hybrid Electric Vehicle market size was valued USD 431,754.4 Million in 2024 and is anticipated to reach USD 568,538.09 Million by 2032, at a CAGR of 3.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hybrid Electric Vehicle Market Size 2024 | USD 431,754.4 million |
| Hybrid Electric Vehicle Market, CAGR | 3.5% |
| Hybrid Electric Vehicle Market Size 2032 | USD 568,538.09 million |
Hybrid Electric Vehicle Market Insights
- Market overview highlights steady adoption of full hybrids and parallel hybrid powertrains, with full hybrids accounting for 41.6% share in 2024, driven by high fuel efficiency, strong mass-market penetration, and suitability for urban and suburban driving conditions.
- Market driver is supported by stricter emission regulations, rising fuel costs, and consumer preference for eco-efficient mobility, encouraging automakers to expand hybrid portfolios and integrate battery, motor, and regenerative braking technologies to improve vehicle performance and operating efficiency.
- Market trends and competitive analysis indicate accelerating investment from leading players such as Toyota, Honda, Ford, Hyundai, Nissan, and Volvo, alongside technology suppliers like Continental, ZF, and BorgWarner, focusing on scalable hybrid platforms and powertrain optimization.
- Regional analysis shows Asia Pacific leading the market with 38.6% share in 2024, followed by North America with 26.8% and Europe with 24.5%, while Latin America and Middle East & Africa collectively represent emerging growth regions with rising hybrid adoption.

Hybrid Electric Vehicle Market Segmentation Analysis:
By Type
The Hybrid Electric Vehicle market by type is defined by three key categories: full hybrids, mild hybrids, and plug-in hybrids. Full hybrids dominate the segment with a market share of 41.6% in 2024, driven by their higher fuel efficiency, regenerative braking capability, and ability to operate in electric-only mode for short distances without external charging. Mild hybrids continue to gain traction due to lower system cost and improved fuel economy, while plug-in hybrids benefit from government incentives and extended electric-driving range, appealing to urban commuters transitioning toward full electrification.
- For instance, Toyota’s hybrid lineup, including the Prius and Corolla Hybrid, helped the company surpass 20 million cumulative hybrid-electric vehicle sales globally by 2022, underscoring sustained demand for full-hybrid technology.
By Power Source
The market by power source comprises stored electricity HEVs and on-board electric generator HEVs. Stored Electricity HEVs hold the dominant position with a 57.3% market share in 2024, supported by advancements in lithium-ion battery technology, improved energy density, and declining battery costs. These vehicles provide better emission control and enhanced energy recovery during braking, increasing adoption across passenger vehicles. On-board electric generator HEVs serve niche and commercial applications where continuous power support is essential, particularly in regions with limited charging infrastructure, but their market penetration remains comparatively lower.
- For instance, Honda’s e:HEV systems in models like the Civic and CR‑V leverage compact lithium‑ion batteries to store recovered braking energy and support electric‑only operation at low speeds.
By Powertrain
The Hybrid Electric Vehicle market by powertrain includes series, parallel, and combined hybrid electric vehicles. Parallel Hybrid Electric Vehicles lead the segment with a 46.8% market share in 2024, as their configuration allows the engine and electric motor to operate simultaneously, delivering better fuel efficiency and lower emissions without compromising performance. The architecture is cost-effective and widely adopted in mass-market hybrid models. Combined hybrid systems are expanding rapidly due to their flexibility in switching between power modes, while series hybrids remain preferred in specific applications focused on high-efficiency urban driving conditions.
Key Growth Drivers
Rising Demand for Fuel-Efficient and Low-Emission Mobility
The Hybrid Electric Vehicle market is experiencing strong growth as governments and consumers prioritize fuel efficiency and emission reduction. Increasing global awareness of climate change, coupled with stringent CO₂ and emission regulations, is compelling automakers to expand hybrid portfolios as a bridge technology toward full electrification. HEVs offer measurable reductions in fuel consumption and tailpipe emissions compared with conventional ICE vehicles, making them attractive for urban mobility and fleet adoption. Growing fuel prices, urban congestion, and the need for sustainable transport further accelerate market uptake. Additionally, hybrids provide operational flexibility by combining electric propulsion with internal combustion engines, reducing range anxiety and charging dependency.
- For instance, the Hyundai IONIQ Hybrid and similar models use regenerative braking and optimized engine‑motor coordination to deliver high efficiency without requiring external charging, appealing to drivers who lack reliable access to home or workplace chargers.
Technological Advancements in Batteries, Power Electronics, and Powertrains
Advancements in lithium-ion batteries, regenerative braking systems, electric motors, and power electronics are significantly improving the performance, reliability, and cost-competitiveness of hybrid electric vehicles. Higher energy density batteries, improved battery management systems, and lightweight vehicle architectures enhance fuel economy and extend electric-assist driving capability. Meanwhile, innovations in parallel and combined hybrid powertrains optimize energy distribution between the engine and electric motor, delivering smoother acceleration and lower emissions. Automakers are also leveraging advanced control software and AI-enabled energy optimization to increase drivetrain efficiency. Cost reductions in battery manufacturing and modular hybrid platforms enable scalable integration across multiple vehicle models.
- For instance, the Kia Sportage Hybrid and Hyundai Tucson Hybrid share a modular electrified powertrain with a 1.6‑liter turbocharged engine and electric motor, delivering up to around 42 mpg city and 44 mpg highway in front‑wheel‑drive Sportage Hybrid trims.
Government Incentives, Supportive Policies, and Infrastructure Push
Government initiatives promoting cleaner transportation remain a crucial catalyst for hybrid electric vehicle adoption. Many countries offer tax benefits, purchase subsidies, fuel-efficiency credits, and preferential regulations to encourage hybrid adoption as part of national decarbonization strategies. Corporate Average Fuel Economy (CAFE) norms, emission compliance targets, and urban low-emission mobility programs compel automakers to incorporate hybrid technologies into vehicle lineups. Public investments in smart mobility, electrification infrastructure, and renewable integration further strengthen the ecosystem supporting HEV deployment. In emerging markets, hybrids serve as a practical transition solution where EV charging networks are still expanding, enabling sustainable mobility without full charging dependence.
Key Trends & Opportunities
Expansion of Hybrid Adoption Across Emerging Markets and Fleet Applications
A major trend in the Hybrid Electric Vehicle market is the increasing penetration of hybrids across emerging economies, where full EV readiness remains limited due to infrastructure and affordability barriers. Hybrids provide an ideal transitional solution by reducing fuel consumption while retaining conventional fueling convenience, making them suitable for mass-market buyers. Fleet operators, ride-hailing companies, and logistics providers are increasingly adopting HEVs to reduce operating costs and comply with sustainability mandates. Automakers are introducing localized hybrid models tailored to regional mobility conditions, price sensitivities, and fuel-efficiency preferences. Growing urbanization, rising middle-class vehicle ownership, and expanding smart-transport initiatives create significant growth opportunities. Hybrid penetration across shared mobility and public transportation further enhances long-term adoption potential, reinforcing the role of HEVs as a strategic enabler of sustainable mobility in developing markets.
- For instance, Toyota reported that hybrids made up 42% of its U.S. sales in the first half of fiscal 2026, with strong hybrid demand also helping lift volumes in competitive markets such as China and other regions, underlining their appeal where full EV uptake is slower
Integration of Smart Mobility, Connectivity, and Electrified Powertrain Innovation
The market is witnessing increasing convergence of hybrid technology with connected mobility, digital diagnostics, and intelligent energy-management systems. Automakers are integrating telematics, predictive maintenance, and AI-based driving analytics to enhance vehicle efficiency and lifecycle performance. Hybrid architectures are also evolving with lightweight materials, modular battery packs, and flexible hybrid platforms that support multiple vehicle categories, including SUVs, sedans, and commercial fleets. The emergence of hybrid-compatible autonomous and ADAS-enabled systems further strengthens vehicle utility in urban environments. Additionally, partnerships between OEMs, battery manufacturers, and technology suppliers are accelerating innovation in hybrid drivetrain optimization and component miniaturization. This technological evolution creates new revenue opportunities, enabling cost-effective hybrid vehicle development and expanding their applicability across next-generation mobility ecosystems.
- For instance, Honda’s next‑generation hybrid platform unveiled in 2025 is designed as a modular architecture that increases body rigidity while reducing weight, and will underpin a range of mid‑size and large HEVs planned for North America from the late 2020s
Key Challenges
High Vehicle and System Integration Costs Affecting Affordability
Despite strong growth potential, the Hybrid Electric Vehicle market faces challenges associated with higher production and ownership costs compared with conventional vehicles. Advanced batteries, electric motors, power electronics, and dual-powertrain integration increase manufacturing complexity and supply-chain dependency. These factors elevate vehicle pricing, which may limit adoption in price-sensitive markets, particularly where subsidy support is limited. OEMs also encounter cost pressures associated with R&D investment, technology licensing, and compliance engineering. Additionally, long-term maintenance and battery replacement perceptions may discourage budget-conscious consumers. Balancing performance, cost, and affordability remains a critical challenge for manufacturers attempting to scale hybrid platforms across multiple vehicle segments. Overcoming cost barriers through technology localization, component standardization, and economies of scale is essential to unlocking broader hybrid market penetration.
Competition from Fully Electric Vehicles and Alternative Powertrain Technologies
The rapid acceleration of fully electric vehicle adoption presents a structural challenge to long-term hybrid market growth. As EV charging infrastructure expands and battery prices decline, consumer preference may gradually shift toward zero-emission vehicles, particularly in mature markets with strong electrification policies. Automakers must also balance investment allocation between hybrid platforms and full-electric architectures, creating strategic and financial trade-offs. Furthermore, emerging alternatives such as hydrogen fuel-cell mobility and advanced biofuel-compatible engines introduce additional competitive dynamics. Policy transitions that prioritize full electrification over hybrid solutions may affect regulatory incentives and reshape technology roadmaps. To remain relevant, hybrid vehicle strategies must align with evolving decarbonization frameworks while positioning HEVs as complementary solutions within diversified electrified mobility portfolios.
Regional Analysis
North America
North America holds a significant position in the Hybrid Electric Vehicle market, accounting for 26.8% market share in 2024, supported by strong consumer awareness, stringent emission regulations, and increasing adoption of hybrid powertrains across passenger and fleet vehicles. The United States leads regional demand due to government fuel-efficiency standards, rising fuel prices, and growing preference for hybrid SUVs and crossovers. Canada complements growth through environmental incentives and urban sustainability programs. Expanding charging-ready infrastructure, corporate fleet electrification, and technological leadership from major automakers further strengthen the regional outlook, with demand expected to increase steadily across metropolitan and suburban mobility markets.
Europe
Europe represents a robust market with 24.5% market share in 2024, driven by strict carbon-emission norms, strong policy support for low-emission mobility, and accelerating hybrid vehicle adoption across Western and Northern European economies. Countries such as Germany, France, the United Kingdom, and the Nordic region are key contributors, supported by consumer incentives and eco-friendly transportation initiatives. Growing penetration of hybrid powertrains in premium and midsize vehicle segments, along with the transition toward electrified fleets, strengthens regional momentum. Hybrid models are increasingly positioned as transition technologies for consumers shifting from internal combustion to fully electric mobility across both private and commercial segments.
Asia Pacific
Asia Pacific dominates the Hybrid Electric Vehicle market with the largest market share of 38.6% in 2024, attributed to high vehicle production volumes, government emission-reduction policies, and rapid adoption across Japan, China, South Korea, and India. Japan leads technological development and mass-market deployment, while China benefits from hybrid expansion alongside growing EV penetration. Rising urbanization, fuel-efficiency awareness, and expanding middle-class ownership further accelerate hybrid demand. Local manufacturing ecosystems, battery supply-chain advantages, and strategic OEM investments reinforce the region’s leadership, making Asia Pacific the primary growth engine for hybrid passenger cars, SUVs, and emerging fleet mobility applications.
Latin America
Latin America accounts for 6.7% market share in 2024, with growth supported by rising fuel costs, increasing urban congestion, and gradual adoption of electrified mobility solutions in major markets such as Brazil, Mexico, and Chile. Hybrid vehicles appeal to cost-sensitive consumers due to lower fuel consumption and reduced maintenance compared with conventional engines. Government initiatives promoting cleaner transportation and fleet modernization programs are fostering early-stage hybrid deployment. Limited charging infrastructure in several countries positions hybrids as a practical alternative to full EVs, and expanding availability of hybrid SUVs and compact vehicles is expected to support steady regional market expansion.
Middle East & Africa
The Middle East & Africa region holds 3.4% market share in 2024, representing a developing yet promising market for hybrid electric vehicles. Growth is driven by urban sustainability programs, diversification initiatives in Gulf economies, and increasing awareness of fuel-efficient mobility solutions. The United Arab Emirates, Saudi Arabia, and South Africa lead adoption, supported by government environmental strategies and gradual expansion of electrified vehicle imports. Hybrids are gaining traction among premium and fleet buyers seeking efficiency benefits without dependence on full-scale charging networks. Although market penetration remains relatively modest, improving policy frameworks and rising environmental commitments are expected to enhance future demand.
Hybrid Electric Vehicle Market Segmentations:
By Type
- Full Hybrids
- Mild Hybrids
- Plug-in Hybrids
By Power Source
- Stored Electricity HEVs
- On-Board Electric Generator HEVs
By Powertrain
- Series Hybrid Electric Vehicles
- Parallel Hybrid Electric Vehicles
- Combined Hybrid Electric Vehicles
By Vehicle
- Hybrid Electric Passenger Cars
- Commercial Hybrid Electric Vehicles
- Hybrid Electric Two Wheelers
- Other HEVs (Golf Cart, etc.)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Hybrid Electric Vehicle market is characterized by the strong presence of global automotive manufacturers that are actively expanding their hybrid portfolios to meet fuel-efficiency standards and emission-reduction targets across major regions. Leading companies such as Toyota, Honda, Ford, Hyundai, Nissan, Volvo, Daimler, and BMW continue to strengthen their positions through product innovation, scalable hybrid platforms, and strategic investments in battery technology and powertrain optimization. Japanese and Korean OEMs remain particularly influential due to their early leadership in hybrid technology and high-volume deployment of mass-market models. European manufacturers are increasingly integrating hybrid systems into premium and performance vehicle segments, while U.S. automakers are focusing on hybrid SUVs, crossovers, and fleet applications. Partnerships with battery suppliers, technology firms, and component manufacturers such as BorgWarner, Schaeffler, Continental, and ZF are further enhancing drivetrain efficiency and system integration. Ongoing R&D initiatives, regulatory compliance strategies, and market-specific product launches collectively shape the evolving landscape of hybrid mobility worldwide.
Key Player Analysis
Recent Developments
- In June 2025, BYD introduced the Seal 05 DM-i hybrid sedan in Poland and Slovakia, marking the company’s second plug-in hybrid electric vehicle (PHEV) offering in the European market. The Seal 05 DM-i is positioned around its long driving range, comfortable interior, and generous trunk capacity, with BYD expressing strong confidence in the model’s growth potential across Europe.
- In June 2025, Hyundai launched an affordable compact electric vehicle in Japan priced at approximately $18,000, aiming to gain traction in a market that has been cautious toward EV adoption. The new Inster model leverages a value-driven strategy similar to the competitive pricing approach used by China’s leading EV manufacturer, BYD.
- In February 2025, Lynk & Co. unveiled the 08 plug-in hybrid SUV in Europe, featuring an electric-only driving range of 200 km and fast-charging capabilities. The Swedish-Chinese automaker announced that the model its third lineup entry in Europe will be available starting June 2025, with pricing beginning at €52,995.
Report Coverage
The research report offers an in-depth analysis based on Type, Power Source, Powertrain, Vehicle and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand as hybrids serve as a practical transition between conventional vehicles and fully electric mobility.
- Automakers will increase investment in advanced hybrid powertrains to improve fuel efficiency and reduce lifecycle emissions.
- Government emission regulations and fleet decarbonization policies will remain key factors supporting hybrid adoption across regions.
- Hybrid technology will gain stronger presence in SUVs, crossovers, and commercial fleets as consumers prioritize efficiency and reliability.
- Battery efficiency, lightweight materials, and regenerative braking improvements will enhance hybrid performance and operating economics.
- Emerging markets will witness faster hybrid adoption due to limited charging infrastructure and rising urban mobility needs.
- Partnerships between OEMs and component suppliers will accelerate innovation in motors, electronics, and energy-management systems.
- Hybrid models will increasingly integrate connectivity, predictive diagnostics, and intelligent energy-optimization features.
- Competition between hybrids and fully electric vehicles will shape product strategies and market positioning.
- Long-term market growth will align with sustainability goals, consumer environmental awareness, and ongoing automotive electrification trends.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hybrid Electric Vehicle Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hybrid Electric Vehicle Market projected to grow between 2024 and 2032?
Which Hybrid Electric Vehicle Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hybrid Electric Vehicle Market?
Who are the leading companies in the Hybrid Electric Vehicle Market?
Which region commanded the largest share of the Hybrid Electric Vehicle Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hybrid Electric Vehicles Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hybrid Electric Vehicles Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 431,754.4 Million → 2032: USD 568,538.09 Million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hybrid Electric Vehicles Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hybrid Electric Vehicles Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hybrid Electric Vehicles Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hybrid Electric Vehicles Market Drivers
- 3.3 Hybrid Electric Vehicles Market Restraints & Challenges
- 3.4 Hybrid Electric Vehicles Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hybrid Electric Vehicles Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hybrid Electric Vehicles Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hybrid Electric Vehicles category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hybrid Electric Vehicles Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Hybrid Electric Vehicles Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Hybrid Electric Vehicles. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hybrid Electric Vehicles Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hybrid Electric Vehicles Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Hybrid Electric Vehicles Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hybrid Electric Vehicles (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Hybrid Electric Vehicles
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hybrid Electric Vehicles Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Hybrid Electric Vehicles Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hybrid Electric Vehicles Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hybrid Electric Vehicles Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hybrid Electric Vehicles Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hybrid Electric Vehicles Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hybrid Electric Vehicles Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hybrid Electric Vehicles Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
