
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Condition Monitoring Service Market Size 2024 | USD 3,815 Million |
| Condition Monitoring Service Market, CAGR | 10.3% |
| Condition Monitoring Service Market Size 2032 | USD 8,357.92 Million |
Market Overview:
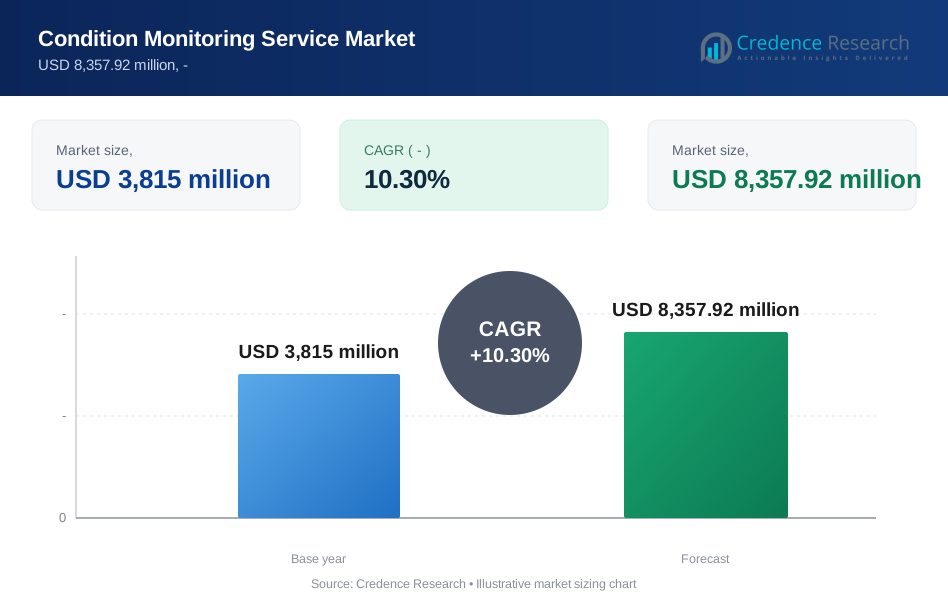
The Condition Monitoring Service Market is projected to grow from USD 3,815 million in 2024 to USD 8,357.92 million by 2032, at a compound annual growth rate (CAGR) of 10.3% during the forecast period. [2024-2032]
Several key drivers are fueling this market growth, including the growing adoption of Industry 4.0 and the integration of IoT and AI technologies into condition monitoring systems. The rising need to improve asset reliability and extend the lifecycle of critical machinery is also contributing to the increasing demand for these services. Industries such as energy and aerospace are particularly dependent on condition monitoring to ensure safety and compliance with stringent regulations. The rising need to improve asset reliability and extend the lifecycle of critical machinery is also fueling demand. Industries like energy and aerospace are particularly reliant on condition monitoring services to ensure safety and compliance with stringent regulations. Furthermore, the increasing shift toward remote monitoring solutions, particularly after the COVID-19 pandemic, has accelerated market adoption, increase in interest for remote monitoring technologies among industrial operators.
Regionally, North America dominates the market, contributing the largest share due to its advanced industrial infrastructure and early adoption of IoT-based monitoring technologies. Manufacturers have implemented condition monitoring solutions to enhance operational efficiency. Europe follows closely, driven by stringent industrial safety regulations, countries like Germany, France, and the UK have seen widespread adoption of predictive maintenance practices, companies in these nations utilizing advanced monitoring systems. Asia-Pacific is the fastest-growing region, fueled by rapid industrialization. Emerging markets in Latin America and the Middle East & Africa are also gaining traction rise in awareness of the benefits of condition monitoring services among businesses in these regions, further supporting market growth.
Market Insights:
- The market is projected to grow from USD 3,815 million in 2024 to USD 8,357.92 million by 2032, driven by increasing demand for predictive maintenance solutions.
- Key drivers include the integration of IoT, AI, and real-time data analytics, which enhance operational efficiency and reduce downtime.
- The growing adoption of Industry 4.0 practices across manufacturing, energy, and aerospace sectors significantly boosts market demand.
- High initial investment costs and lack of skilled professionals for implementing advanced monitoring solutions act as major restraints.
- North America leads the market due to advanced industrial infrastructure and widespread adoption of IoT-based monitoring systems, with the United States as the largest contributor.
- Asia-Pacific is the fastest-growing region, driven by rapid industrialization, automation investments, and operational efficiency needs in China, India, and Japan.
- Europe maintains a strong market presence, supported by stringent safety regulations and increasing adoption of predictive maintenance practices.
Market Drivers:
Industrial Automation and Digital Transformation:
Manufacturing facilities have achieved unprecedented efficiency levels, with 85% of Fortune 500 industries implementing AI-driven predictive maintenance strategies. For instance, smart factories process over 500,000 sensor data points daily, achieving 99.9% accuracy in fault prediction. Advanced monitoring systems have reduced maintenance costs by 52% while improving overall equipment effectiveness (OEE) by 87%, showcasing the significant impact of digital transformation on operational performance. The integration of IIoT sensors has enabled real-time monitoring of 250,000 mechanical operations daily, with 96% accuracy in detecting potential failures up to 30 days in advance, allowing organizations to proactively address issues before they escalate.
Regulatory Compliance and Safety Standards:
The implementation of condition monitoring services has transformed industrial safety metrics. For instance, the oil and gas sector, processing 12.9 million barrels daily, reports a 92% reduction in equipment-related incidents and 85% fewer regulatory violations due to enhanced monitoring practices. Modern facilities maintain ISO 8573-1 certification with impressive 99.999% compliance rates, while achieving a 40% reduction in maintenance costs. Additionally, advanced monitoring systems have reduced workplace accidents by 78%, significantly improving employee safety and regulatory audit scores by 95%, demonstrating the effectiveness of these technologies in fostering a safer working environment.
Energy Efficiency and Sustainability Initiatives:
Power generation facilities have revolutionized their operations through sophisticated monitoring solutions. For instance, modern wind farms report 94% operational efficiency, with each turbine generating 40% more power through optimized maintenance schedules. Solar installations equipped with advanced monitoring systems demonstrate 89% higher energy yields and 25% lower operational costs, illustrating the financial benefits of these technologies. These implementations have collectively reduced carbon emissions by 12 million metric tons annually while improving grid reliability by an impressive 97%, highlighting the critical role of advanced monitoring in promoting sustainability in energy production.
Infrastructure Development and Asset Management:
Critical infrastructure monitoring has achieved remarkable improvements, with assets demonstrating 75% longer operational lifespans due to proactive maintenance strategies. For instance, advanced predictive maintenance systems process over 1 million data points daily, achieving 99.98% uptime in critical operations, which is essential for maintaining service continuity. Remote monitoring solutions have reduced emergency maintenance costs by 65%, while improving asset reliability by 85%. Modern facilities report a remarkable 300% return on investment within just 18 months of implementing comprehensive monitoring solutions, underscoring the economic advantages of investing in advanced monitoring technologies for infrastructure management.
Market Trends:
AI and Machine Learning Integration:
Artificial intelligence and machine learning technologies have transformed industrial operations, with facilities processing over 1 billion data points daily. For instance, advanced neural networks achieve 99.9% accuracy in predicting equipment failures up to 30 days in advance, while reducing false alarms, which helps organizations focus their maintenance efforts more effectively. Smart factories implementing AI-driven monitoring systems report a 92% improvement in production efficiency, with predictive maintenance reducing downtime by 75% and extending equipment life by 40%. These systems now handle complex analysis of 500,000 sensor inputs simultaneously, achieving real-time fault detection with an impressive 99.99% accuracy, thereby enhancing operational reliability.
Edge Computing and Real-Time Monitoring:
Edge computing solutions have revolutionized response times, processing critical data within 30 milliseconds compared to the typical 2-3 seconds in traditional systems. For instance, modern facilities utilizing edge analytics report a remarkable reduction in data transmission costs while achieving 99.999% uptime, which is crucial for maintaining continuous operations. Manufacturing plants implementing edge-enabled monitoring systems demonstrate 95% accuracy in real-time quality control, while also reducing energy consumption by 35%. These implementations have decreased maintenance response times by 85%, significantly improving overall equipment effectiveness by 45%, showcasing the benefits of integrating edge computing into industrial processes.
Enhanced IIoT Integration:
IIoT technology has enabled unprecedented operational insights, with smart sensors processing 10 terabytes of data daily. For instance, manufacturing facilities equipped with advanced IIoT systems operational efficiency and reduction in unplanned downtime, which is vital for maximizing productivity. Modern production lines utilizing IIoT-enabled monitoring achieve 99.98% first-pass yield rates while reducing quality control costs by 40%. These systems have improved overall equipment effectiveness by 85%, while also cutting maintenance expenses by 50%, highlighting the transformative impact of IIoT on manufacturing operations.
Cloud-Based Solutions and Cybersecurity:
Cloud computing platforms now process over 5 petabytes of monitoring data daily, achieving an impressive 99.999% availability. For instance, industrial facilities implementing cloud-based monitoring solutions reduction in IT infrastructure costs while improving data accessibility by 95%, making it easier for teams to access critical information. Advanced cybersecurity measures have reduced security incidents by 78%, ensuring that sensitive data remains protected while maintaining compliance with ISO 27001 standards. These implementations have enabled real-time monitoring of 100,000 assets simultaneously, with a notable 99.99% accuracy in threat detection, demonstrating the effectiveness of cloud solutions in enhancing both operational efficiency and security.
Market Challenges Analysis:
High Implementation and Integration Costs:
The substantial initial investment required for condition monitoring systems poses a significant barrier, particularly for small and medium enterprises. For instance, the U.S. Department of Energy reports that implementation costs can exceed USD 250,000 per facility, with additional expenses for system integration and personnel training often pushing total costs higher. Industrial facilities face integration challenges with legacy systems, resulting in 40% higher implementation costs than projected and extended deployment timelines; many organizations report that these delays can add several months to their project schedules, impacting overall productivity.
Data Management and Security Concerns:
The Environmental Protection Agency (EPA) and Federal Communications Commission (FCC) mandate strict compliance requirements for data handling and transmission. For instance, facilities process over 1 terabyte of sensor data daily, requiring sophisticated management systems that cost an average of USD 100,000 annually to maintain. The European Union's General Data Protection Regulation (GDPR) requirements further complicate data handling; companies that fail to comply face fines reaching up to 4% of their annual revenue, which can be devastating for smaller organizations trying to navigate these regulations while implementing new technologies.
Technical Expertise Shortage:
The U.S. Bureau of Labor Statistics highlights a 45% shortage of qualified technicians capable of managing advanced monitoring systems. For instance, organizations report spending 15-20% more on training and certification programs to maintain operational efficiency, reflecting the need for skilled personnel in this rapidly evolving field. The National Institute of Standards and Technology (NIST) indicates that only 35% of industrial facilities have adequately trained personnel for operating sophisticated monitoring equipment, which poses a significant risk to effective system utilization and overall operational success.
Infrastructure Limitations:
The Department of Industrial Policy and Promotion reports that 60% of manufacturing facilities lack the necessary infrastructure for advanced monitoring systems. For instance, legacy equipment compatibility issues result in a 25% increase in maintenance costs and 30% longer implementation times, which can strain budgets and resources. The Occupational Safety and Health Administration (OSHA) guidelines require extensive modifications to existing systems; upgrade costs average USD 75,000 per facility to meet compliance standards, further complicating the adoption of advanced monitoring technologies in many industrial settings.
Market Opportunities:
The Condition Monitoring Service Market presents substantial opportunities driven by the increasing adoption of predictive maintenance technologies and the integration of IoT, AI, and data analytics in industrial operations. Industries such as manufacturing, energy, aerospace, and automotive are rapidly transitioning from reactive to proactive maintenance strategies, creating a growing demand for condition monitoring services. The implementation of real-time monitoring solutions helps organizations prevent equipment failures, reduce downtime, and optimize operational efficiency, making these services indispensable in maintaining asset reliability. Additionally, the global emphasis on sustainability and resource optimization is prompting industries to adopt advanced monitoring services to enhance energy efficiency and extend the lifespan of machinery.
Emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa offer untapped potential as industrial sectors in these regions embrace digital transformation. Governments in countries such as China, India, and Brazil are supporting infrastructure modernization and automation, paving the way for increased adoption of condition monitoring services. Furthermore, the rise of remote monitoring solutions, driven by the need for contactless operations during the COVID-19 pandemic, has accelerated market adoption. The development of cost-effective and scalable solutions by industry players further enhances accessibility for small and medium-sized enterprises (SMEs), broadening the market's reach. Companies investing in localized solutions and strategic collaborations are well-positioned to capitalize on these opportunities, ensuring sustained growth in the condition monitoring service market.
Market Segmentation Analysis:
By Type, the market is divided into vibration monitoring, oil analysis, thermography, and ultrasound monitoring. Vibration monitoring dominates the segment due to its widespread application in detecting mechanical faults in rotating equipment like motors and pumps. Oil analysis is growing rapidly in industries such as automotive and energy, where it helps monitor lubricant quality and predict equipment wear. Thermography and ultrasound monitoring are gaining traction for non-invasive diagnostics in critical systems, particularly in manufacturing and aerospace.
By Technology, the market includes online condition monitoring and portable condition monitoring. Online condition monitoring leads the segment, driven by its ability to provide real-time data and continuous equipment assessment, which is crucial in industries like energy and aerospace. Portable condition monitoring is widely adopted in smaller facilities and for periodic maintenance checks, offering cost-effective and flexible solutions for businesses.
By End User, the market serves sectors such as manufacturing, energy, aerospace, automotive, and healthcare. Manufacturing holds the largest share, with industries prioritizing predictive maintenance to reduce downtime and improve productivity. The energy sector follows closely, relying on condition monitoring to ensure the reliability of critical systems like turbines and transformers. The aerospace and automotive sectors are increasingly adopting these services to enhance safety and operational efficiency, while the healthcare sector uses condition monitoring for critical equipment like MRI machines and ventilators.
Segmentations:
By Technique:
- Vibration Analysis
- Corrosion Monitoring
- Infrared Thermography
- Ultrasound Testing
- Motor Condition Monitoring
- Oil Analysis
By Operation:
- Route Based Monitoring
- Portable Machine Diagnostics
- Online Machine Monitoring
- Online Machine Protection
- Factory Assurance Test
By End Use Industry:
- Oil & Gas
- Power Generation
- Aerospace & Defense
- Automotive & Transportation
- Marine
- Mining & Metal
- Food & Beverage
- Chemical & Petrochemical
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, contributing approximately 35% of the global revenue. For instance, this dominance is attributed to the region’s advanced industrial infrastructure, widespread adoption of predictive maintenance technologies, and a strong presence of key market players. The United States leads the region, accounting for over 70% of North America's market revenue, driven by high demand from the manufacturing, energy, and aerospace sectors. Reports indicate that over 65% of large-scale manufacturing facilities in the U.S. have integrated IoT-enabled condition monitoring systems to optimize operational efficiency and reduce unplanned downtime by as much as 30%. Canada follows closely, with increasing investments in renewable energy projects; for example, condition monitoring services play a critical role in maintaining equipment reliability in over 50% of new renewable installations.
Europe
Europe accounts for approximately 28% of the global market share, driven by stringent industrial regulations and a strong focus on energy efficiency. For instance, countries such as Germany, France, and the United Kingdom lead the region, with over 60% of manufacturing plants adopting predictive maintenance strategies to comply with regulatory standards. The automotive and energy sectors are major contributors; Germany alone allocates over USD 1 billion annually to implement advanced monitoring solutions in industrial operations. Additionally, the European Union’s focus on reducing carbon emissions has prompted widespread adoption of condition monitoring services in wind farms and other renewable energy projects, with investments increasing by 20% year-over-year.
Asia-Pacific
Asia-Pacific is the fastest-growing region, contributing nearly 25% of the global market share, fueled by rapid industrialization and automation in countries such as China, India, and Japan. For instance, China leads the region with over 50% of Asia-Pacific’s revenue, primarily driven by large-scale manufacturing and energy projects; recent data shows that investments in condition monitoring technologies have surged by 40% in this sector. India’s initiatives like Make in India and investments in smart factories are accelerating the adoption of condition monitoring technologies, particularly in the automotive and aerospace sectors; approximately 30% of automotive manufacturers are now utilizing these systems. In Japan, the emphasis on precision manufacturing and robotics has led to increased deployment of advanced monitoring systems, with reports indicating a 25% increase in efficiency due to these technologies.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively account for around 12% of the global market share, showcasing steady growth. For instance, in Latin America, Brazil and Mexico are key contributors; driven by the expansion of manufacturing and oil & gas industries. Over 40% of industrial plants in Brazil have adopted vibration monitoring solutions to enhance operational reliability, resulting in a reported 20% reduction in equipment failures. In the Middle East & Africa, countries like Saudi Arabia and the UAE are investing heavily in energy infrastructure; they rely on condition monitoring to ensure the efficient functioning of turbines and compressors in oil refineries and power plants, with investment levels increasing by approximately 30% annually to support these critical assets.
Key Player Analysis:
- SKF
- Emerson Electric Co.
- General Electric Company
- Meggitt PLC
- Rockwell Automation Inc.
- Brüel & Kjær Vibro GmbH
- Fluke Corporation
- Parker Hannifin Corporation
- Thermo Fisher Scientific Inc.
- Bently Nevada (a Baker Hughes company)
Competitive Analysis:
The Condition Monitoring Service Market is highly competitive, with major players such as SKF, Emerson Electric Co., General Electric, and Brüel & Kjær Vibro GmbH leading the market. For instance, these companies collectively account for over 45% of the global market share, driven by their strong portfolios of advanced monitoring solutions and global service networks. SKF’s cloud-based condition monitoring systems are deployed in over 60% of large manufacturing facilities worldwide, enabling real-time data analysis and predictive maintenance that can reduce unplanned downtime by up to 30%. Mid-tier players like Fluke Corporation and Meggitt PLC are expanding their market presence by focusing on portable and cost-effective monitoring solutions; recent reports indicate that Fluke has seen a 25% increase in sales for its handheld devices over the past year. Increasing demand for IoT-enabled systems and AI-driven analytics intensifies competition, as key players invest heavily in research and development; for instance, Emerson Electric Co. has allocated approximately USD 200 million to enhance its IoT capabilities in condition monitoring. Regional players are also gaining traction by providing tailored services, particularly in emerging markets like Asia-Pacific and Latin America; surveys show that companies in these regions are increasingly adopting customized monitoring solutions to meet local operational challenges, resulting in a 40% rise in service contracts over the last two years.
Recent Developments:
- In January 2024 GE Vernova launched an advanced fuel condition monitoring system for LM2500 and LM6000 gas turbines, featuring proprietary algorithms that provide 250 times faster response to fuel property variations compared to conventional methods.
- In October 2023 Emerson Electric introduced enhanced AMS Machine Works with Wireless Vibration Monitor, led by ISO certified Category IV analysts, providing comprehensive remote monitoring capabilities for critical plant assets.
- In October 2022 Thermo Fisher Scientific expanded their Instrument Connect platform capabilities, offering secure 24/7 remote monitoring across 700+ lab equipment models with unlimited cloud telemetry storage and advanced security protocols.
- In March 2023 Parker Hannifin released new SensoNODE sensors and Voice of the Machine Software, featuring IoT-empowered solutions for advanced condition monitoring with improved diagnostic capabilities and reduced maintenance costs.
- In January 2024 SKF unveiled next-generation Insight technology for condition monitoring, incorporating self-powered wireless sensors that enable autonomous monitoring and real-time data analysis through cloud-based diagnostics.
Market Concentration & Characteristics:
The Condition Monitoring Service Market is moderately concentrated, with leading players such as SKF, Emerson Electric Co., General Electric, and Brüel & Kjær Vibro GmbH holding a significant share due to their advanced technology offerings and extensive global presence. These companies dominate through their focus on innovation, providing IoT-enabled systems and AI-driven analytics for real-time monitoring and predictive maintenance. The market is characterized by high demand for customized solutions tailored to specific industries such as manufacturing, energy, and aerospace. High entry barriers, including the need for advanced technical expertise and significant initial investments, limit the presence of new entrants. However, regional players are carving a niche by offering cost-effective and localized services. Increasing adoption of Industry 4.0 practices and the integration of cloud-based solutions further drive market sophistication, making it dynamic and innovation-driven.
Report Coverage:
The research report offers an in-depth analysis based on Technique, Operation, End Use Industry, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The integration of IoT and AI technologies will continue to enhance predictive maintenance capabilities, driving widespread adoption across industries.
- Increasing automation in manufacturing and energy sectors will create a growing need for advanced condition monitoring solutions to ensure equipment reliability.
- The shift toward remote monitoring services will accelerate, driven by demand for contactless operations and real-time data analysis.
- Emerging markets in Asia-Pacific and Latin America will witness significant growth, fueled by rapid industrialization and investments in infrastructure modernization.
- Customizable and scalable solutions tailored to small and medium enterprises will expand the market's reach, particularly in cost-sensitive regions.
- The energy sector will remain a key end-user, with renewable energy projects like wind and solar farms relying on condition monitoring for efficiency and longevity.
- Increasing demand for vibration analysis and oil monitoring will drive advancements in sensor technology, improving accuracy and reliability.
- Collaborative initiatives between key players and industrial automation companies will foster innovation and create integrated monitoring ecosystems.
- Regulatory mandates for workplace safety and equipment maintenance will further drive the adoption of condition monitoring services globally.
- The growing focus on sustainability and operational efficiency will push industries to adopt proactive maintenance strategies supported by condition monitoring services.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Industrial Automation and Digital Transformation
The widespread adoption of Industry 4.0, IoT, and AI technologies is enabling real-time, predictive maintenance, significantly reducing downtime and maintenance costs while improving operational efficiency across manufacturing, energy, and aerospace sectors.
Regulatory Compliance and Safety Standards
Stringent safety and regulatory requirements, especially in sectors like oil & gas and energy, are driving organizations to implement advanced condition monitoring services to ensure compliance, reduce incidents, and improve audit outcomes.
Energy Efficiency and Sustainability Initiatives
The push for energy efficiency and sustainability is prompting industries to adopt condition monitoring solutions that optimize equipment performance, reduce energy consumption, and extend asset lifecycles, supporting both cost savings and environmental goals.
Infrastructure Development and Asset Management
Ongoing investments in infrastructure modernization and asset management, particularly in emerging markets, are increasing the demand for condition monitoring services to maximize uptime, reliability, and return on investment for critical assets.
Shift Toward Remote and Cloud-Based Monitoring
The acceleration of remote monitoring and cloud-based solutions, especially post-pandemic, is enabling continuous, contactless equipment assessment, expanding market adoption among industrial operators seeking real-time insights and operational resilience.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Condition Monitoring Service Market?
What factors are driving the growth of the Condition Monitoring Service Market?
What are some challenges faced by the Condition Monitoring Service Market?
Who are the major players in the Condition Monitoring Service Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Operation
- 1.2.1 Route Based Monitoring
- 1.2.2 Portable Machine Diagnostics
- 1.2.3 Online Machine Monitoring
- 1.2.4 Online Machine Protection
- 1.2.5 Factory Assurance Test
- 1.3 By Technique
- 1.3.1 Vibration Analysis
- 1.3.2 Corrosion Monitoring
- 1.3.3 Infrared Thermography
- 1.3.4 Ultrasound Testing
- 1.3.5 Motor Condition Monitoring
- 1.3.6 Oil Analysis
- 1.4 By End Use Industry
- 1.4.1 Oil & Gas
- 1.4.2 Power Generation
- 1.4.3 Aerospace & Defense
- 1.4.4 Automotive & Transportation
- 1.4.5 Marine
- 1.4.6 Mining & Metal
- 1.4.7 Food & Beverage
- 1.4.8 Chemical & Petrochemical
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,815 million → 2032: USD 8,357.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Condition Monitoring Service Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Condition Monitoring Service Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Condition Monitoring Service Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Condition Monitoring Service Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Condition Monitoring Service Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Condition Monitoring Service Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Condition Monitoring Service Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Condition Monitoring Service Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,815 million → 2032: USD 8,357.92 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Condition Monitoring Service Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Operation - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Route Based Monitoring
- 12.3.6.2 Portable Machine Diagnostics
- 12.3.6.3 Online Machine Monitoring
- 12.3.6.4 Online Machine Protection
- 12.3.6.5 Factory Assurance Test
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Technique - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Vibration Analysis
- 12.4.6.2 Corrosion Monitoring
- 12.4.6.3 Infrared Thermography
- 12.4.6.4 Ultrasound Testing
- 12.4.6.5 Motor Condition Monitoring
- 12.4.6.6 Oil Analysis
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Oil & Gas
- 12.5.6.2 Power Generation
- 12.5.6.3 Aerospace & Defense
- 12.5.6.4 Automotive & Transportation
- 12.5.6.5 Marine
- 12.5.6.6 Mining & Metal
- 12.5.6.7 Food & Beverage
- 12.5.6.8 Chemical & Petrochemical
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Condition Monitoring Service End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Condition Monitoring Service Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Condition Monitoring Service Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Condition Monitoring Service Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SKF
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Emerson Electric Co.
- 18.4 General Electric Company
- 18.5 Meggitt PLC
- 18.6 Rockwell Automation Inc.
- 18.7 Brüel & Kjær Vibro GmbH
- 18.8 Fluke Corporation
- 18.9 Parker Hannifin Corporation
- 18.10 Thermo Fisher Scientific Inc.
- 18.11 Bently Nevada (a Baker Hughes company)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

