
Market Overview
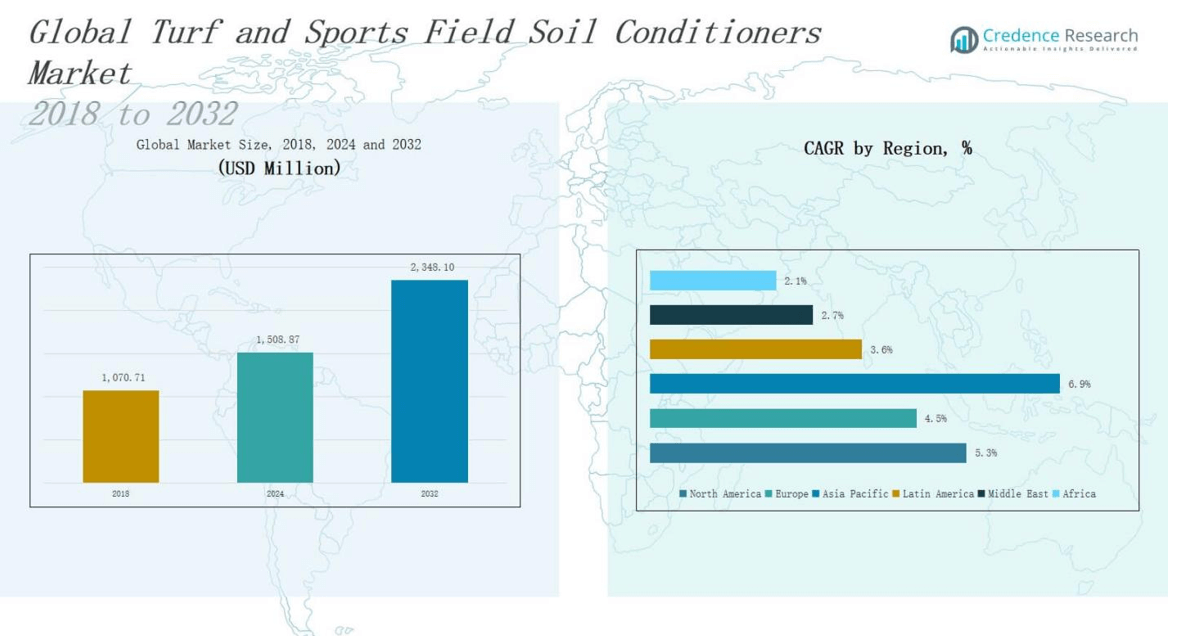
The Turf and Sports Field Soil Conditioners Market size was valued at USD 1,070.71 million in 2018 to USD 1,508.87 million in 2024 and is anticipated to reach USD 2,348.10 million by 2032, at a CAGR of 5.29% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Turf and Sports Field Soil Conditioners Market Size 2024 | USD 1,508.87 million |
| Turf and Sports Field Soil Conditioners Market, CAGR | 5.29% |
| Turf and Sports Field Soil Conditioners Market Size 2032 | USD 2,348.10 million |
The Turf and Sports Field Soil Conditioners Market is driven by rising demand for high-performance playing surfaces, increasing investments in sports infrastructure, and growing awareness of turfgrass health and soil management. The need to enhance soil aeration, water retention, and nutrient availability supports widespread adoption across stadiums, golf courses, and recreational parks. Trends include the integration of organic and sustainable soil conditioners, development of bio-based formulations, and use of precision turf management technologies. Climate resilience and environmental compliance further influence product innovation, while emerging markets witness increased uptake due to expanding sports activities and urban green space development.
The Turf and Sports Field Soil Conditioners Market spans North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads in market share, followed by Europe and the rapidly growing Asia Pacific region. Latin America, the Middle East, and Africa show steady development driven by expanding sports infrastructure. Key players include BASF SE, Syngenta AG, Solvay S.A., UPL Limited, FMC Corporation, The Scotts Miracle-Gro Co., Nutrien Ltd., Novozymes A/S, CLARIANT, Loveland Products, Aquatrols, EarthWorks, Pro’s Choice, Eastman Chemical, and Evonik Industries.
Market Insights
- The Turf and Sports Field Soil Conditioners Market is projected to grow from USD 1,508.87 million in 2024 to USD 2,348.10 million by 2032, at a CAGR of 5.29%.
- North America leads the global market with USD 658.92 million in 2024, driven by advanced infrastructure and early adoption of organic conditioners.
- Asia Pacific is the fastest-growing region, expected to reach USD 563.81 million by 2032 due to urbanization and increased sports investments.
- Rising demand for high-performance athletic surfaces and professional turf maintenance practices fuels market expansion across stadiums and parks.
- Key trends include the use of sustainable and bio-based soil conditioners, and the integration of precision turf management technologies.
- High cost and limited technical expertise among end users remain key challenges, particularly in developing regions.
- Leading companies include BASF SE, Syngenta AG, Solvay S.A., UPL Limited, FMC Corporation, Nutrien Ltd., and The Scotts Miracle-Gro Co.
Market Drivers
Rising Demand for High-Quality Athletic Surfaces
The Turf and Sports Field Soil Conditioners Market is fueled by increasing demand for high-performance, visually appealing, and durable athletic surfaces. Sports complexes, schools, and professional stadiums are investing in turf systems that offer consistent playability and safety. Soil conditioners help improve root zone stability, moisture retention, and nutrient delivery, enhancing turf resilience under heavy use. Facility managers seek solutions that minimize turf degradation and support efficient maintenance schedules. This growing preference strengthens market adoption of advanced soil conditioners.
- For instance, Elitecourt manufactures synthetic acrylic sports surfaces that resist UV fading and cracking, ensuring long-lasting courts suitable for basketball and tennis.
Expansion of Sports Infrastructure Worldwide
Ongoing investments in sports infrastructure across developed and emerging nations are propelling the Turf and Sports Field Soil Conditioners Market. Governments and private entities are constructing new stadiums, training centers, and community fields to support rising participation in organized sports. These projects require soil improvement products that ensure long-term turf health and surface uniformity. The expansion of multi-sport venues and synthetic turf systems further accelerates product demand. It reflects a global push to professionalize sports and improve athletic experiences.
Focus on Sustainability and Environmental Performance
Sustainability is a key driver shaping product innovation within the Turf and Sports Field Soil Conditioners Market. Facility owners are prioritizing eco-friendly inputs that reduce water use, promote organic soil enrichment, and lower chemical dependency. Manufacturers are responding with bio-based, non-toxic, and biodegradable soil conditioners tailored to meet environmental standards. These solutions appeal to institutions aiming to align with green building certifications and public sustainability goals. It enhances the market’s growth prospects in eco-conscious regions.
- For instance, Turface Athletics has developed turf conditioners like Greens Grade and Turface MVP, proven by trials at The Ohio State University to enhance drainage, moisture retention, and turf recovery on natural grass fields, supporting sustainable turf maintenance practices.
Increased Emphasis on Turf Management Technology
Technological advancements in turf management are supporting the growth of the Turf and Sports Field Soil Conditioners Market. Data-driven irrigation, soil monitoring systems, and precision application tools allow tailored conditioner use, improving efficiency and results. Facility managers value the ability to maintain optimal soil conditions with minimal manual intervention. Integration of technology with agronomic practices drives adoption in professional and municipal sports environments. It positions soil conditioners as essential components of modern turf maintenance programs.
Market Trends
Growing Integration of Organic and Sustainable Soil Inputs
A major trend in the Turf and Sports Field Soil Conditioners Market is the growing preference for organic and environmentally safe formulations. Turf managers increasingly select conditioners made from compost, humic substances, and other bio-based materials to reduce chemical exposure and improve soil biodiversity. This shift is driven by rising regulatory pressure and public demand for sustainable practices in sports field maintenance. It encourages manufacturers to develop low-impact solutions that support soil health while meeting environmental standards. The trend aligns with broader sustainability initiatives across municipalities and sports organizations.
- For instance, LIQHUMUS Liquid 18, a potassium humate liquid conditioner, has demonstrated improved nutrient uptake and root development in hydroponic tomato cultivation, supporting its use in environments requiring rapid assimilation and low environmental impact.
Adoption of Precision Turf and Soil Management Practices
Technological integration is reshaping how turf professionals approach soil conditioning. In the Turf and Sports Field Soil Conditioners Market, GPS-guided applicators, real-time soil monitoring sensors, and automated irrigation systems are enabling precise treatment and reduced resource waste. These tools allow groundskeepers to identify specific deficiencies and tailor applications for optimal turf performance. It improves input efficiency while minimizing maintenance costs. The trend reflects a shift toward data-informed turf management that emphasizes performance, accountability, and operational efficiency.
- For instance, the Belfry Hotel & Resort has utilized Soil Scout’s data-driven insights to better manage irrigation across its extensive golf course, leading to optimized water use and improved turf health.
Increasing Popularity of Hybrid and Reinforced Turf Systems
Hybrid turf systems, combining natural grass with synthetic reinforcement, are gaining traction in professional sports venues. The Turf and Sports Field Soil Conditioners Market benefits from this trend, as such systems demand specialized soil conditioners to maintain root integrity and drainage efficiency. These hybrid installations support heavy usage without compromising turf aesthetics or player safety. It encourages the development of conditioners formulated to work within these advanced turf ecosystems. The market sees rising interest in high-resilience products suited for hybrid applications.
Focus on Climate Adaptability and Drought Resistance
Changing climate conditions are influencing turf management priorities, particularly in regions experiencing water scarcity and extreme weather. In the Turf and Sports Field Soil Conditioners Market, demand is increasing for products that enhance water retention, heat tolerance, and root depth. Soil conditioners that support drought-resilient turf systems are in high demand, especially across the southwestern United States, Australia, and parts of Southern Europe. It prompts innovation in water-saving materials and techniques. The trend highlights the market's alignment with long-term environmental resilience and adaptation.
Market Challenges Analysis
High Cost of Advanced and Organic Soil Conditioners
The Turf and Sports Field Soil Conditioners Market faces a significant challenge in the high cost of premium and organic soil conditioning products. Many sports facilities, especially in developing regions or smaller municipalities, operate under limited maintenance budgets. These buyers often prioritize short-term turf solutions over long-term soil health investments. It limits the adoption of advanced conditioners that offer sustainable and performance-driven benefits. Price sensitivity slows market penetration for newer, eco-friendly technologies and creates a barrier for widespread use across all field types.
Limited Awareness and Technical Expertise Among End Users
Many turf managers, especially in amateur sports and municipal settings, lack sufficient knowledge about the benefits and proper use of soil conditioners. The Turf and Sports Field Soil Conditioners Market struggles with uneven education and training across user groups, leading to inconsistent application and suboptimal results. It creates skepticism about product efficacy and deters repeat purchases. Vendors must invest in outreach and technical support to bridge this gap. Without adequate knowledge transfer, product potential remains underutilized, constraining market growth.
Market Opportunities
Expansion into Emerging Sports Markets and Community Facilities
The Turf and Sports Field Soil Conditioners Market holds strong potential in emerging economies where investments in recreational and school sports infrastructure are increasing. Governments and local bodies are building new athletic fields to support youth engagement and public health initiatives. These developments create demand for soil conditioners that ensure safe, durable, and easy-to-maintain playing surfaces. It opens growth avenues for mid-tier and localized product suppliers. Expanding product access and affordability can unlock untapped customer segments in Asia, Latin America, and Africa.
Product Innovation Aligned with Climate-Resilient Turf Systems
Climate variability presents an opportunity to develop soil conditioners tailored to drought-prone and high-temperature regions. The Turf and Sports Field Soil Conditioners Market can capitalize on this shift by offering materials that improve water retention, root strength, and soil structure under stress. Solutions supporting heat and traffic resistance will find strong demand among stadiums, golf courses, and urban parks. It encourages R&D efforts focused on biodegradable polymers, biochar, and mineral-based conditioners. Companies that deliver climate-smart products can build a competitive edge in environmentally sensitive and high-usage regions.
Market Segmentation Analysis:
By Type
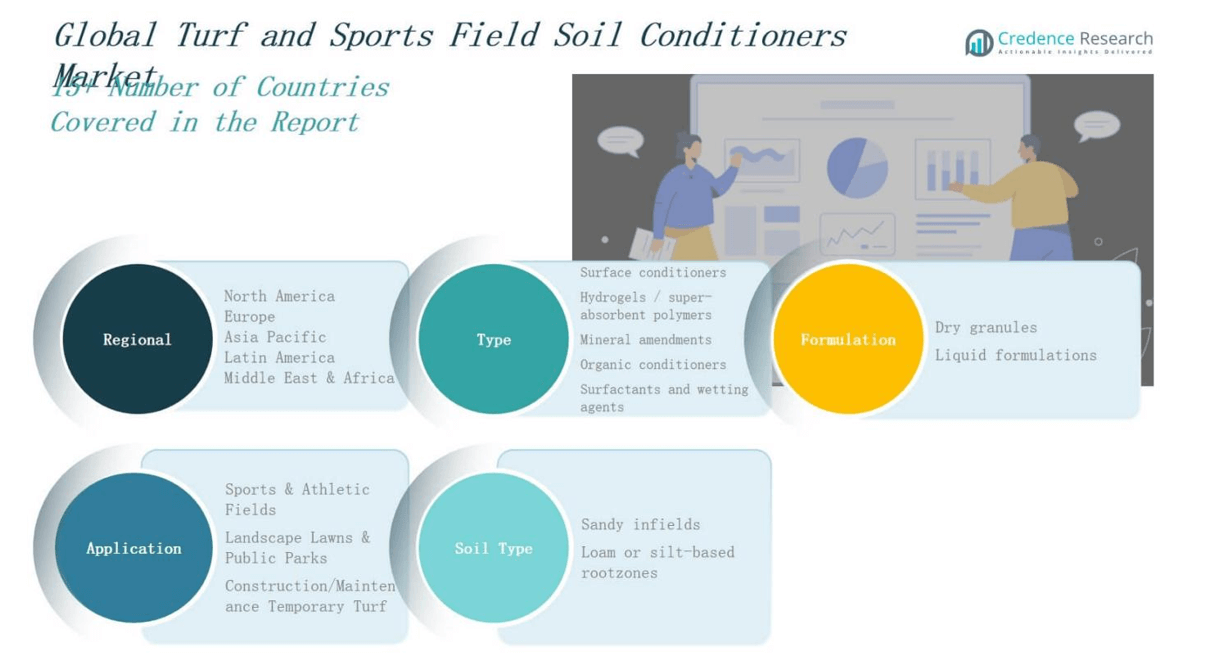
The Turf and Sports Field Soil Conditioners Market includes surface conditioners, hydrogels or super-absorbent polymers, mineral amendments, organic conditioners, and surfactants or wetting agents. Surface conditioners dominate due to their ability to stabilize topsoil and improve playability on sports fields. Hydrogels are gaining traction in drought-prone areas for their superior water retention. Organic conditioners appeal to environmentally conscious users. It benefits from increasing demand for performance-boosting yet sustainable soil amendments in turf management.
- For instance, Turface Athletics’ calcined clay products like Turface MVP® and Pro League® Elite™ are widely used by professional groundskeepers to optimize moisture retention, reduce compaction, and ensure safer playing surfaces due to their superior stability and water management compared to other materials.
By Formulation
Based on formulation, the Turf and Sports Field Soil Conditioners Market segments into dry granules and liquid formulations. Dry granules hold a larger share due to ease of storage, long shelf life, and uniform application across wide turf areas. Liquid formulations offer faster absorption and are ideal for spot treatments and precision turf care. It supports tailored application strategies suited to varying soil conditions and maintenance protocols.
- For instance, The Grounds Guys highlight that granular fertilizer offers slow-release nutrients suited for sustained feeding, while liquid fertilizers provide immediate nutrient absorption for quick green-up effects.
By Application
By application, the Turf and Sports Field Soil Conditioners Market serves sports and athletic fields, landscape lawns and public parks, and temporary turf setups used during construction or events. Sports and athletic fields represent the largest segment due to frequent maintenance requirements and player safety standards. Landscape lawns and parks use conditioners to preserve turf aesthetics and foot-traffic durability. It reflects growing urban investments in recreational green spaces.
Segments:
Based on Type
- Surface Conditioners
- Hydrogels / Super-Absorbent Polymers
- Mineral Amendments
- Organic Conditioners
- Surfactants and Wetting Agents
Based on Formulation
- Dry Granules
- Liquid Formulations
Based on Application
- Sports & Athletic Fields
- Landscape Lawns & Public Parks
- Construction/Maintenance Temporary Turf
Based on Soil Type
- Sandy Infields
- Loam or Silt-Based Rootzones
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Turf and Sports Field Soil Conditioners Market size was valued at USD 472.43 million in 2018 to USD 658.92 million in 2024 and is anticipated to reach USD 1,028.23 million by 2032, at a CAGR of 5.3% during the forecast period. North America holds the largest share of the global market, driven by advanced sports infrastructure, strong turf management practices, and high adoption of premium soil conditioners. The U.S. leads regional demand, supported by frequent sports events and high turf maintenance standards. Universities, stadiums, and recreational parks are key application areas. It benefits from early adoption of organic and climate-resilient soil inputs. Suppliers in this region continue to innovate with customized and eco-friendly product lines.
Europe
The Europe Turf and Sports Field Soil Conditioners Market size was valued at USD 298.14 million in 2018 to USD 404.71 million in 2024 and is anticipated to reach USD 592.24 million by 2032, at a CAGR of 4.5% during the forecast period. Europe accounts for a considerable share due to widespread sports culture, especially in football, rugby, and golf. Western European countries like the UK, Germany, and France drive most of the demand. The market emphasizes sustainability, with strong interest in organic conditioners and low-impact soil technologies. It benefits from government-led environmental policies that encourage sustainable turf care. Public parks and urban green zones represent steady end-use growth areas.
Asia Pacific
The Asia Pacific Turf and Sports Field Soil Conditioners Market size was valued at USD 210.22 million in 2018 to USD 320.60 million in 2024 and is anticipated to reach USD 563.81 million by 2032, at a CAGR of 6.9% during the forecast period. Asia Pacific is the fastest-growing regional market, supported by rapid urbanization, rising investments in sports infrastructure, and growing interest in sustainable landscaping. China, Japan, India, and Australia lead adoption, with government programs promoting green spaces and recreational fields. The market gains traction in schools, community centers, and public stadiums. It shows strong demand for water-saving solutions like hydrogels. Increasing awareness of turf quality and safety enhances future market prospects.
Latin America
The Latin America Turf and Sports Field Soil Conditioners Market size was valued at USD 47.36 million in 2018 to USD 65.86 million in 2024 and is anticipated to reach USD 89.90 million by 2032, at a CAGR of 3.6% during the forecast period. Latin America shows steady market growth, fueled by the expansion of sports facilities and municipal green spaces. Brazil and Argentina are major contributors, hosting regional tournaments and community sports programs. Cost-sensitive buyers seek practical and effective soil management solutions. It sees rising usage in soccer fields and urban parks. Local suppliers are focusing on affordable, climate-resilient conditioners tailored to regional needs.
Middle East
The Middle East Turf and Sports Field Soil Conditioners Market size was valued at USD 26.90 million in 2018 to USD 34.28 million in 2024 and is anticipated to reach USD 43.95 million by 2032, at a CAGR of 2.7% during the forecast period. The region’s market is driven by a growing number of golf courses, stadiums, and luxury real estate projects with manicured landscapes. The UAE and Saudi Arabia lead demand, especially in high-end turf installations. Water scarcity issues push demand for hydrogels and surfactants. It experiences rising interest in sustainable and water-efficient soil management practices. Product adoption remains concentrated in high-investment urban zones.
Africa
The Africa Turf and Sports Field Soil Conditioners Market size was valued at USD 15.65 million in 2018 to USD 24.50 million in 2024 and is anticipated to reach USD 29.96 million by 2032, at a CAGR of 2.1% during the forecast period. Africa represents a small but emerging market, with growth tied to government efforts to improve public sports facilities and community recreation areas. South Africa leads regional demand, followed by Egypt and Kenya. The market faces challenges such as limited awareness and low purchasing power. It holds potential in areas with international sports events and tourism-driven turf development. Vendors offering cost-effective, durable products are well-positioned to capture growth.
Key Player Analysis
- Loveland Products, Inc.
- BASF SE
- CLARIANT
- EarthWorks Natural Organic Products
- The Scotts Miracle-Gro Co.
- Novozymes A/S
- Solvay S.A.
- UPL Limited
- Pro’s Choice Sports Field Products
- Eastman Chemical Co.
- Evonik Industries AG
- Syngenta AG
- Aquatrols (Lamberti Group)
- FMC Corporation
- Nutrien Ltd.
Competitive Analysis
The Turf and Sports Field Soil Conditioners Market is moderately competitive, with key players focusing on innovation, sustainability, and performance-based formulations to strengthen their market presence. Companies such as BASF SE, Syngenta AG, and The Scotts Miracle-Gro Co. lead through diverse product portfolios and established distribution networks. It features both global chemical giants and niche organic solution providers competing across pricing, efficacy, and environmental impact. Strategic partnerships, product launches, and regional expansion remain core growth strategies. Manufacturers invest in R&D to develop conditioners that improve soil structure, water efficiency, and turf resilience. The market also sees rising participation from regional players offering cost-effective solutions tailored to local turf conditions. Companies increasingly emphasize digital turf management support, customized soil testing services, and training programs to improve customer retention and product adoption. Competitive advantage now depends on ecological value, technical support, and the ability to meet evolving turf performance and sustainability standards.
Recent Developments
- In December 2024, Super-Sod formed a partnership with Tri-Tex Grass, enhancing its turfgrass portfolio specifically for sports fields.
- On May 23, 2025, Oakcreek Golf & Turf acquired L.L. Johnson Distributing and Midwest Turf, strengthening its turf equipment and conditioner distribution capabilities.
- On October 9, 2024, Turf Care Supply, LLC-backed by Platte River Equity-acquired Agri‑Nutrients, Inc., enhancing its manufacturing footprint and product range in granular fertilizers and soil amendments.
- In October 2024, Turf Care Supply, LLC further strengthened its capabilities by acquiring Beaty Fertilizer, adding custom granular and liquid fertilizer blending expertise in Tennessee.
Market Concentration & Characteristics
The Turf and Sports Field Soil Conditioners Market features moderate market concentration with a mix of global chemical companies, regional players, and specialized organic product manufacturers. Leading firms such as BASF SE, Syngenta AG, and The Scotts Miracle-Gro Co. hold substantial market shares due to their broad portfolios, established distribution networks, and strong brand recognition. It is characterized by steady innovation, with players investing in bio-based formulations and performance-enhancing technologies. Market differentiation depends on product efficacy, environmental compliance, and technical support. Entry barriers remain moderate, influenced by regulatory requirements and the need for agronomic expertise. The market supports both premium and cost-effective solutions, catering to a diverse customer base across public parks, stadiums, schools, and municipalities. Seasonal demand fluctuations and regional climate conditions impact purchasing cycles. Long-term contracts with institutional buyers and government agencies provide stability. Product customization, regional distribution reach, and field-level support are critical factors shaping competitiveness in this evolving market.
Report Coverage
The research report offers an in-depth analysis based on Type, Formulation, Appliation, Soil Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for soil conditioners will grow with increasing investments in sports infrastructure and turf quality improvement.
- Adoption of organic and bio-based products will rise due to environmental regulations and sustainability goals.
- Advanced turf management technologies will support precision application and efficiency in conditioner usage.
- Climate-resilient formulations will gain traction in regions facing water scarcity and extreme weather conditions.
- Emerging economies will see higher uptake driven by urban development and recreational field expansion.
- Manufacturers will expand product portfolios to address diverse soil types and turf maintenance needs.
- Partnerships with municipalities and educational institutions will help secure long-term supply contracts.
- Cost-effective and locally adapted solutions will grow in demand in price-sensitive markets.
- Training programs and technical support will become key to increasing awareness and proper usage.
- Digital platforms will play a larger role in product education, ordering, and field support services.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Sports Infrastructure
Global investments in new stadiums, training centers, and community sports fields are increasing the need for soil conditioners that ensure durable, high-quality turf surfaces. This infrastructure boom, especially in emerging markets, directly drives demand for advanced soil management products.
Focus on Sustainability and Environmental Compliance
Growing regulatory and public pressure for eco-friendly sports field maintenance is pushing facility managers to adopt organic and bio-based soil conditioners. This trend is accelerating product innovation and market growth, particularly in regions with strong environmental standards.
Adoption of Precision Turf Management Technologies
The integration of data-driven irrigation, soil monitoring, and precision application tools enables more efficient and targeted use of soil conditioners. These technologies improve turf performance and resource efficiency, making conditioners essential in modern turf management.
Climate Resilience and Water Scarcity
Increasing frequency of droughts and extreme weather events is driving demand for soil conditioners that enhance water retention, root strength, and turf resilience. Products tailored for climate adaptability are gaining traction, especially in regions facing water scarcity.
Rising Standards for Athletic Surface Quality
Professional and amateur sports organizations are raising expectations for turf safety, playability, and aesthetics. Soil conditioners that improve root zone stability, moisture management, and nutrient delivery are increasingly adopted to meet these higher standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Turf and Sports Field Soil Conditioners Market?
What factors are driving the growth of the Turf and Sports Field Soil Conditioners Market?
What are some challenges faced by the Turf and Sports Field Soil Conditioners Market?
Who are the major players in the Turf and Sports Field Soil Conditioners Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Surface Conditioners
- 1.2.2 Hydrogels / Super-Absorbent Polymers
- 1.2.3 Mineral Amendments
- 1.2.4 Organic Conditioners
- 1.2.5 Surfactants and Wetting Agents
- 1.3 By Soil Type
- 1.3.1 Sandy Infields
- 1.3.2 Loam or Silt-Based Rootzones
- 1.4 By Application
- 1.4.1 Sports & Athletic Fields
- 1.4.2 Landscape Lawns & Public Parks
- 1.4.3 Construction/Maintenance Temporary Turf
- 1.5 By Formulation
- 1.5.1 Dry Granules
- 1.5.2 Liquid Formulations
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,508.87 million → 2032: USD 2,348.10 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Turf and Sports Field Soil Conditioners Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Turf and Sports Field Soil Conditioners Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Turf and Sports Field Soil Conditioners Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Turf and Sports Field Soil Conditioners Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Turf and Sports Field Soil Conditioners Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Turf and Sports Field Soil Conditioners Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Turf and Sports Field Soil Conditioners Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Turf and Sports Field Soil Conditioners Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,508.87 million → 2032: USD 2,348.10 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Turf and Sports Field Soil Conditioners Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Surface Conditioners
- 12.3.7.2 Hydrogels / Super-Absorbent Polymers
- 12.3.7.3 Mineral Amendments
- 12.3.7.4 Organic Conditioners
- 12.3.7.5 Surfactants and Wetting Agents
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Soil Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sandy Infields
- 12.4.7.2 Loam or Silt-Based Rootzones
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sports & Athletic Fields
- 12.5.7.2 Landscape Lawns & Public Parks
- 12.5.7.3 Construction/Maintenance Temporary Turf
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Formulation - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Dry Granules
- 12.6.7.2 Liquid Formulations
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Turf and Sports Field Soil Conditioners End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Turf and Sports Field Soil Conditioners Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Turf and Sports Field Soil Conditioners Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Turf and Sports Field Soil Conditioners Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Syngenta AG
- 18.4 Solvay S.A.
- 18.5 UPL Limited
- 18.6 FMC Corporation
- 18.7 The Scotts Miracle-Gro Co.
- 18.8 Nutrien Ltd.
- 18.9 Novozymes A/S
- 18.10 CLARIANT
- 18.11 Aquatrols
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

