
Market Overview:
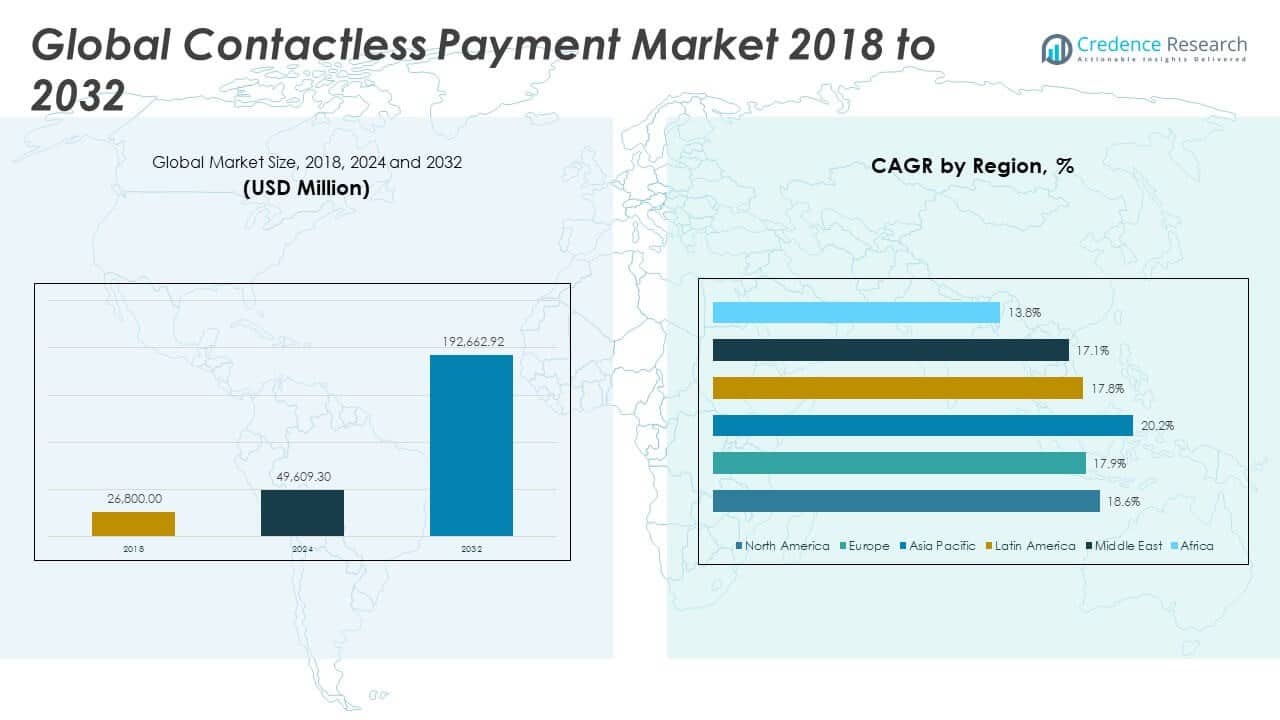
The Contactless Payment Market size was valued at USD 26,800 million in 2018 to USD 49,609.30 million in 2024 and is anticipated to reach USD 192,662.92 million by 2032, at a CAGR of 18.59% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Contactless Payment Market Size 2024 | USD 49,609.30 Million |
| Contactless Payment Market, CAGR | 18.59% |
| Contactless Payment Market Size 2032 | USD 192,662.92 Million |
Rising smartphone penetration, growing preference for seamless transactions, and rapid digitization of payment infrastructure drive the market's momentum. Financial institutions and fintech companies are expanding contactless options through mobile wallets, NFC-based cards, and QR-code systems to improve consumer convenience and speed. Government initiatives supporting digital payment adoption, especially in developing economies, are reshaping the transaction landscape. Consumer behavior has shifted toward cashless preferences due to hygiene concerns and faster checkouts. It leads to expanding use across retail, transportation, and hospitality, strengthening global adoption.
North America, Europe, and Asia Pacific are leading the market, with Asia Pacific emerging as the fastest-growing region due to high mobile usage and e-wallet adoption. North America dominates in technological infrastructure and fintech innovation, while Europe benefits from uniform regulations and widespread contactless card deployment. Latin America, the Middle East, and Africa are experiencing rising adoption due to smartphone growth, improving digital infrastructure, and financial inclusion initiatives. Urbanization and policy frameworks in these regions are pushing the demand upward.
Market Insights:
- The Contactless Payment Market size was valued at USD 26,800 million in 2018 to USD 49,609.30 million in 2024 and is anticipated to reach USD 192,662.92 million by 2032, at a CAGR of 18.59% during the forecast period.
- Rising smartphone penetration and POS upgrades significantly boost transaction volume and user adoption.
- Security risks such as fraud and data breaches continue to challenge the digital payments environment.
- Asia Pacific leads in growth rate, fueled by widespread mobile wallet use and proactive digital strategies.
- Government policies and digital literacy campaigns have expanded financial access and inclusion.
- North America and Europe benefit from advanced infrastructure and harmonized regulatory frameworks.
- Continuous innovation, seamless API integration, and changing consumer habits are reshaping the market landscape.
Market Drivers:
Widespread Smartphone Penetration and Growing Wallet Ecosystems
The Contactless Payment Market continues to expand with increasing smartphone penetration, particularly in emerging economies. Consumers now expect mobile wallet compatibility and intuitive interfaces that streamline daily purchases. Wallet platforms such as Apple Pay, Google Pay, and Samsung Pay have integrated loyalty programs, real-time alerts, and biometric authentication, boosting user retention. Businesses benefit from reduced cash handling, real-time transaction updates, and improved customer satisfaction. The rise of 5G, cloud infrastructure, and edge computing enhances the performance and responsiveness of mobile-based transactions. This convergence of hardware and software innovation reinforces mobile-based payments as the dominant form of contactless solutions.
- For example, at the 2024 Global Fintech Fest, Google Pay introduced six major features, such as UPI Circle (enabling controlled delegations and preset monthly spending limits), ClickPay QR compatibility, and Tap & Pay with RuPay cards. The Tap & Pay for RuPay allows millions to tap their phone for payment without saving any sensitive card data, strengthening security and privacy.
Accelerated Merchant POS Upgrades Across Retail Sectors
Retail, hospitality, and transportation sectors are rapidly updating their point-of-sale terminals to support contactless payments. The Contactless Payment Market sees consistent merchant demand for speed, efficiency, and security. POS manufacturers offer solutions with EMV compliance, NFC capability, and QR-code support, enabling a flexible payment experience. The low cost of hardware and government incentives in countries like India and Brazil accelerate deployment. Retail chains are also integrating contactless loyalty and rewards programs at the checkout. This ecosystem-wide shift promotes smoother customer experiences and drives higher purchase frequency per visit.
Supportive Government Policies and Digital Infrastructure Development Several national governments are creating favorable policy environments for digital transactions. The Contactless Payment Market benefits from programs like India’s Digital India campaign, Singapore’s Smart Nation initiative, and Europe’s SEPA (Single Euro Payments Area). Governments provide funding for rural broadband, fintech innovation hubs, and digital ID systems, all of which support secure contactless systems. Subsidized terminal installations and mandates for QR-code payment availability push adoption among micro- and small businesses. Tax benefits and financial inclusion programs tie payments to healthcare, education, and welfare schemes, creating sustained behavioral change among users.- For example, the Unified Payments Interface (UPI) processed over 14 billion digital transactions in May 2024 alone, supported by Digital India’s rural broadband investments and an allocation of ₹26 billion (US$309 million) dedicated to fintech startups.
Consumer Demand for Hygiene, Speed, and Security
Modern consumers prioritize hygiene and speed during transactions, especially in post-pandemic environments. The Contactless Payment Market has evolved to meet expectations for no-touch checkout, secure biometric validation, and sub-second payment speeds. Shoppers avoid physical cash and PIN inputs, especially in high-traffic locations like supermarkets and metro stations. Retailers deploying contactless systems report higher customer satisfaction and throughput. The shift is permanent among digitally literate urban populations and is steadily percolating into suburban and rural regions. Security layers including dynamic CVV, tokenization, and real-time fraud detection further build user confidence.
Market Trends:
Biometric Authentication Driving User Trust and Regulatory Compliance
The Contactless Payment Market is integrating biometric authentication to boost trust and align with security mandates such as PSD2 and PCI DSS. Solutions range from face recognition in mobile apps to fingerprint verification on cards. Biometric tokens replace static passwords and PINs, making transactions seamless and secure. Banks and fintech startups alike are developing biometric-enabled wearables and mobile apps. Biometric trust is particularly relevant in high-value payments and elder-friendly interfaces. Such innovation helps providers reduce fraud while improving accessibility across demographics.
- For instance, IDEMIA's solutions integrate fingerprint, facial, and iris recognition into payment workflows, offering contactless user verification that meets or exceeds regulatory requirements for PSD2 and PCI DSS in the banking sector.
Adoption of Tap-to-Ride Systems in Urban Transportation Networks
Public transit systems in major cities have rapidly shifted to tap-to-ride systems. The Contactless Payment Market is witnessing widespread implementation in metros, buses, and ferries across North America, Europe, and Asia Pacific. Commuters use contactless cards, smartwatches, or NFC phones to access transportation without queues or tickets. Transit agencies benefit from reduced operating costs and higher efficiency. The integration of mobility-as-a-service (MaaS) platforms allows dynamic fare adjustment and multi-modal journey planning. The trend is being replicated in tier-2 cities, offering robust market growth potential.
Proliferation of SoftPOS Among SMEs and Informal Sector Small merchants are embracing SoftPOS apps that convert smartphones into payment terminals. The Contactless Payment Market is becoming more inclusive through this trend, particularly in countries with high informal economic activity. SoftPOS eliminates hardware costs and empowers micro-enterprises to accept digital payments securely. Payment providers bundle services like invoicing, accounting, and tax tools to increase adoption. This development has strong implications for rural adoption, seasonal businesses, and gig economy workers. The ecosystem enables a broader shift from cash to digital, increasing transaction transparency. Integration of Cryptocurrency and Stablecoin Payments As digital currencies become mainstream, contactless platforms are integrating crypto wallets and cards. The Contactless Payment Market is exploring secure crypto-to-fiat conversions at the point of sale. Platforms such as PayPal and Mastercard support crypto-based contactless cards. Stablecoins offer reduced volatility for everyday spending, appealing to cross-border travelers and tech-savvy users. Merchants benefit from reduced fees and instant settlement. While still a niche trend, regulatory developments and blockchain innovations could accelerate mainstream use in the next five years.- For example, Coinbase Commerce enables merchants worldwide to accept payments in more than 200 cryptocurrencies, with documented quick settlements (often within minutes) and fixed conversion options, reducing exposure to price volatility.
Market Challenges Analysis:
Cybersecurity Vulnerabilities and Evolving Fraud Tactics
The Contactless Payment Market faces persistent concerns around data security, especially in high-volume environments. Attack methods such as RFID skimming, man-in-the-middle intrusions, and token duplication are evolving alongside the technology. Consumers are hesitant to adopt contactless systems unless security protocols are transparent and effective. Payment providers must continually update firmware and cloud systems with encryption standards, anomaly detection, and secure elements. The balance between user convenience and transaction integrity is critical to retaining user confidence, particularly in regions with high fraud rates. Lack of Infrastructure and Digital Literacy in Developing Economies
The Contactless Payment Market experiences uneven growth due to limited infrastructure and low digital awareness in rural and underdeveloped regions. Many small businesses lack access to smartphones, power, or stable internet connections. Users unfamiliar with digital banking are less likely to adopt contactless platforms. Education campaigns and offline solutions like QR codes can mitigate some barriers, but require coordinated efforts from governments and private sector players. Until infrastructure improves, contactless systems remain underutilized in vast segments of the global population.
Market Opportunities:
Financial Inclusion Through Tailored Contactless Ecosystems
The Contactless Payment Market holds strong growth potential in underserved rural and semi-urban areas. Fintech companies are partnering with governments to deliver simplified payment solutions through feature phones, agent-assisted kiosks, and biometric devices. These localized solutions support UPI, QR, and Aadhaar-linked wallets, making digital payments accessible to first-time users. This segment remains large and largely untapped, representing a sustained growth path.
Integration with Smart Cities and Public Utilities Contactless payments are becoming embedded in urban infrastructure projects. The Contactless Payment Market sees emerging opportunities in smart parking, tolls, vending, and public service kiosks. Governments and municipal bodies are issuing contactless ID cards linked to citizen services. This integration creates long-term demand across multiple civic domains and aligns with sustainability and cashless economy goals.Market Segmentation Analysis:
The Contactless Payment Market features a diverse segmentation landscape driven by evolving consumer preferences and advancements in transaction technologies.
By type, the market is divided into Smartphone Based Payments and Card Based Payments. Smartphone-based payments are rapidly gaining popularity due to mobile wallet integration, biometric security, and NFC-enabled devices. They offer convenience, real-time transaction monitoring, and loyalty program syncing. Card-based payments continue to dominate in many mature markets, segmented into credit cards, debit cards, and others. Credit cards hold a major share due to rewards programs and consumer financing flexibility, while debit cards lead in regions with direct bank-to-bank transactions and lower consumer credit reliance.
- For example, Apple Pay and Google Payare widely adopted apps utilizing biometric authentication (such as fingerprint or face ID) to confirm purchases securely. Since most modern smartphones contain built-in biometric sensors, users can simply tap their device to an NFC-enabled terminal, verifying their identity instantly and reducing the risk of unauthorized transactions.
By application, the Contactless Payment Market covers Retail, Consumer Electronics, Transportation, Healthcare, Hospitality, and Others. Retail accounts for the largest share due to high transaction frequency and demand for faster checkouts. The transportation sector is adopting tap-to-ride models, reducing operational delays. Healthcare facilities use contactless systems for streamlined billing and reduced patient wait times. Consumer electronics retailers and hospitality venues increasingly implement mobile POS and QR-code-based systems to enhance user experience. It maintains steady growth across all applications by adapting to sector-specific requirements.
- For instance, hotel staff equipped with mobile POS can handle check-in, room key issues, or dining charges at any location on the property, creating a seamless, high-touch guest experience
Segmentation:
By Type:
- Smartphone Based Payments
- Card Based Payments
- Credit Cards
- Debit Cards
- Others
By Application:
- Retail
- Consumer Electronics
- Transportation
- Healthcare
- Hospitality
- Others
By Region:
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Contactless Payment Market was valued at USD 9,272.80 million in 2018 and reached USD 16,946.24 million in 2024. It is projected to attain USD 65,717.67 million by 2032, growing at a CAGR of 18.6% during the forecast period. The region accounted for 34.17% of the global market share in 2024. North America leads the contactless payment space due to its advanced digital infrastructure, widespread financial literacy, and early adoption of near-field communication (NFC) technologies. The U.S. is at the forefront, driven by tech giants and broad adoption across sectors. Continued innovation in wearable payment solutions and open banking APIs is further solidifying the region’s leadership.
Europe
The Europe Contactless Payment Market stood at USD 7,906.00 million in 2018 and grew to USD 14,127.37 million in 2024. It is expected to reach USD 52,164.00 million by 2032, expanding at a CAGR of 17.9% during the forecast period. The region held a 28.48% share of the global market in 2024. Europe benefits from strong regulatory frameworks, high card penetration, and cross-border payment initiatives like SEPA. The UK, Germany, and France are key contributors, leading in adoption and innovation. Increasing integration of biometric authentication and NFC in public transportation systems is also driving the market forward.
Asia Pacific
The Asia Pacific Contactless Payment Market was valued at USD 6,030.00 million in 2018 and reached USD 11,700.15 million in 2024. It is projected to grow to USD 50,535.64 million by 2032, registering the highest CAGR of 20.2% during the forecast period. The region captured 23.59% of the global market share in 2024. Asia Pacific is the fastest-growing region, driven by mobile-first payment ecosystems, growing smartphone usage, and robust government support. China and India are key players in this surge. The expansion of QR code-based payments and strategic partnerships between banks and tech firms are fostering deeper penetration across rural areas.
Latin America
The Latin America Contactless Payment Market grew from USD 2,283.36 million in 2018 to USD 4,196.45 million in 2024. It is anticipated to reach USD 15,426.52 million by 2032, at a CAGR of 17.8% during the forecast period. The region accounted for 8.46% of the global market in 2024. Growth is supported by fintech expansion, mobile payment penetration, and regulatory efforts to formalize financial systems. Brazil and Mexico are the primary growth hubs. The increasing involvement of international payment providers and expanding smartphone affordability are expected to bolster transaction volumes further.
Middle East
The Middle East Contactless Payment Market increased from USD 1,042.52 million in 2018 to USD 1,810.42 million in 2024. It is projected to grow to USD 6,358.94 million by 2032, registering a CAGR of 17.1% during the forecast period. The region represented 3.65% of the global market share in 2024. The Middle East is investing heavily in digital transformation, with countries like the UAE and Saudi Arabia adopting national platforms and fintech initiatives to modernize transactions. The rise of e-commerce and the growing millennial consumer base are accelerating contactless payment usage across various segments.
Africa
The Africa Contactless Payment Market was valued at USD 265.32 million in 2018 and rose to USD 828.68 million in 2024. It is forecast to reach USD 2,460.16 million by 2032, with a CAGR of 13.8% during the forecast period. Africa accounted for 1.67% of the global market share in 2024. The region is in the early stages of growth, propelled by mobile money platforms and digital inclusion programs. Kenya, Nigeria, and South Africa are emerging as key markets despite ongoing infrastructure and access challenges. Collaborative efforts between telecom providers and fintech startups are expected to play a vital role in accelerating adoption.
Key Player Analysis:
- Visa Inc.
- Mastercard Inc.
- Apple Inc.
- Google LLC
- Samsung Electronics Co., Ltd.
- PayPal Holdings Inc.
- Alipay
- Fiserv, Inc.
- Global Payments Inc.
- Stripe, Inc.
- Adyen N.V
- Ingenico
- Verifone Holdings, Inc.
- Thales Group
- Giesecke+Devrient GmbH
- IDEMIA
- ACI Worldwide Inc.
- Square, Inc.
- PayU
- Infineon Technologies AG
Competitive Analysis:
The Contactless Payment Market exhibits high competition with global and regional players striving for innovation and reach. Companies like Visa, Mastercard, and Apple maintain market leadership through diversified offerings, strategic acquisitions, and global expansion. Emerging players like Stripe and Adyen focus on flexible APIs and fast integration to support merchants. Firms are investing in advanced authentication, blockchain-based security, and user personalization. The market structure remains dynamic with new entrants exploring niche areas such as SoftPOS and crypto integration. Industry leaders maintain competitive advantage through brand trust, wide networks, and regulatory compliance.
Recent Developments:
- In June 2025, PayPal expanded its partnership with Fiserv to advance stablecoin (PYUSD) payments and build interoperability with Fiserv’s FIUSD. This supports innovative, cross-border, and programmable payments, contributing to the evolution of contactless payments.
- In April 2025, Visa launched Visa Intelligent Commerce an AI-powered initiative to personalize, secure, and streamline digital payment experiences. The platform includes new services to help businesses manage payments, insights, and fraud prevention, all of which directly support advancements in contactless payment solutions.
- In March 2025, Fiserv acquired CCV, a European payment solutions provider, to boost its Clover platform widely used for touchless in-person payment. In June 2025, Fiserv also acquired full control of its AIB Merchant Services JV, enhancing omni-channel and contactless merchant payment capabilities in Europe.
- In August 2024, Adyen expanded its partnership with PayPal for Fastlane by PayPal in the U.S., enabling faster, seamless checkouts with card and shipping details-directly reducing friction in contactless online payments.
Market Concentration & Characteristics:
The Contactless Payment Market is moderately concentrated with a blend of legacy financial institutions and disruptive fintech firms. Large players hold significant market share through widespread adoption and multi-channel capabilities. The market is characterized by rapid innovation, evolving consumer behavior, and high scalability. It demonstrates strong growth potential in both developed and emerging economies. Interoperability, real-time transaction capabilities, and strategic partnerships define key competitive attributes. Regulatory compliance and security innovations remain critical for long-term success.
Report Coverage:
The research report offers an in-depth analysis based on Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The integration of biometric authentication with contactless payments will improve transaction security and convenience, reducing the need for physical cards or PINs across sectors like healthcare and banking. This shift will drive higher user trust and adoption.
- Digital wallets and super apps are expected to expand across emerging markets, combining services such as payments, savings, and microloans in a unified interface, accelerating financial inclusion and contactless transaction volumes.
- Public transport systems are increasingly adopting tap-to-pay solutions through partnerships with fintechs, making daily commuting more seamless and boosting the frequency of low-value contactless payments.
- AI-driven POS systems will transform retail by offering real-time promotions, loyalty rewards, and personalized experiences through contactless terminals, encouraging repeat purchases and customer retention.
- The rise of SoftPOS will allow merchants to turn smartphones into payment terminals, removing hardware barriers for small businesses and expanding the acceptance footprint in underserved areas.
- Regulatory momentum toward open banking and payment interoperability will support smooth cross-border contactless transactions, increasing adoption among international travelers and global e-commerce users.
- Embedded finance platforms will incorporate contactless payments into lifestyle and utility apps, driving everyday usage and making payments a seamless part of the digital experience.
- Wearable devices such as smartwatches and rings will offer new ways to make contactless payments, appealing to tech-savvy users and increasing transaction opportunities in fitness and travel sectors.
- Cloud-based infrastructure will enhance real-time analytics, enabling merchants to personalize offerings and optimize fraud detection while maintaining high-speed contactless settlements.
- The preferences of digital-first generations will push brands to integrate gamified loyalty, subscription services, and crypto-linked payments within contactless ecosystems, enriching user engagement and payment diversity.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Contactless Payment Market?
What factors are driving the growth of the Contactless Payment Market?
What are the key segments within the Contactless Payment Market?
What are some challenges faced by the Contactless Payment Market?
Who are the major players in the Contactless Payment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Contactless Payment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Contactless Payment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 49,609.30 million → 2032: USD 192,662.92 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Contactless Payment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Contactless Payment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Contactless Payment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Contactless Payment Market Drivers
- 3.3 Contactless Payment Market Restraints & Challenges
- 3.4 Contactless Payment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Contactless Payment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Contactless Payment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Contactless Payment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Contactless Payment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Contactless Payment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Contactless Payment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Contactless Payment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Contactless Payment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Contactless Payment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Contactless Payment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Contactless Payment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Contactless Payment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Contactless Payment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Contactless Payment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Contactless Payment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Contactless Payment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Contactless Payment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Contactless Payment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Contactless Payment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
