
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Depot Repair Service Market Size 2023 | USD 29,005 Million |
| Depot Repair Service Market, CAGR | 7.10% |
| Depot Repair Service Market Size 2032 | USD 50,208.95 Million |
Market Overview:
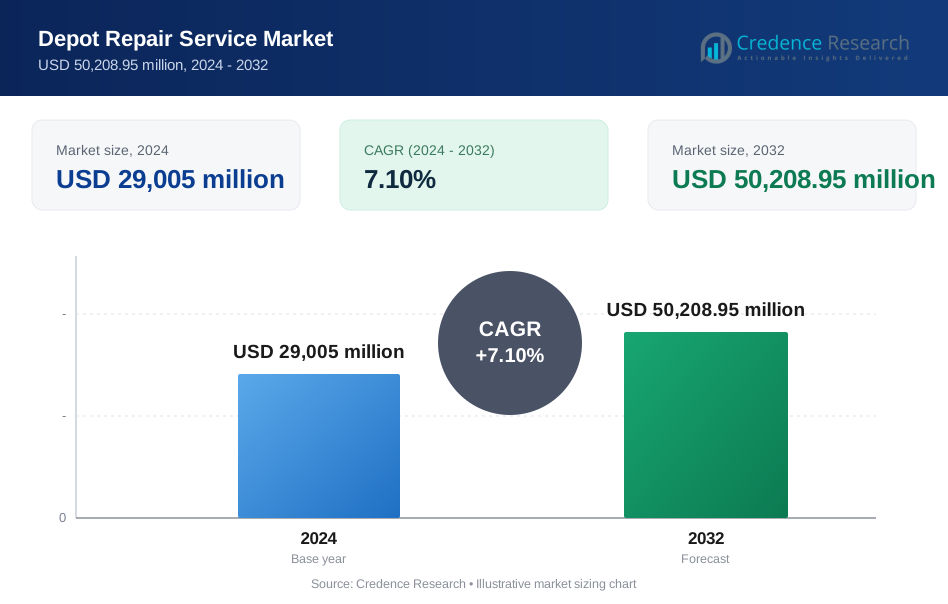
The global Depot Repair Service Market is projected to grow significantly from USD 29,005 million in 2024 to USD 50,208.95 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.10% during the forecast period. This growth is driven by increasing demand for efficient after-sales services, particularly in industries that rely on complex machinery and electronics. Depot repair services, which include refurbishing, testing, and maintenance of equipment, play a crucial role in extending product lifecycles and reducing downtime. The growing focus on customer service excellence and the need for businesses to maintain operational efficiency are further driving the expansion of the depot repair service market.
Key drivers contributing to the market growth include the increasing adoption of sophisticated electronic devices across industries such as healthcare, telecommunications, and manufacturing. The need for regular maintenance and repair services for these devices is crucial for avoiding operational failures and ensuring productivity. Additionally, the rising trend of outsourcing repair services to specialized third-party providers is boosting market demand. Companies seek to minimize costs while maintaining equipment reliability, driving growth in the market. The expansion of industries such as aerospace, defence, and automotive, which rely heavily on complex machinery and equipment, further fuels the demand for depot repair services.
North America holds the largest market share, driven by the presence of leading industrial and technological players in the region and their focus on efficient after-sales services. Europe follows closely, with strong demand from the automotive and electronics sectors. Asia-Pacific is expected to witness the fastest growth, attributed to the rapid industrialization and increased use of electronics in countries like China, Japan, and India. Latin America and Middle East & Africa are also emerging markets, supported by growing industrial infrastructure and the increasing need for maintenance and repair services across sectors.
Market Drivers:
Increasing Adoption of Complex Electronic Devices:
One of the primary drivers in the Depot Repair Service Market is the growing reliance on complex electronic devices across various industries. Sectors such as healthcare, telecommunications, and manufacturing are increasingly dependent on sophisticated equipment that requires regular maintenance and repair. For instance, the U.S. Bureau of Labor Statistics highlighted that the healthcare sector alone has seen a significant rise in medical equipment adoption, necessitating more frequent and specialized repair services. The need to ensure minimal downtime and operational continuity further pushes companies to invest in depot repair services.
Rising Outsourcing Trends:
Another key factor is the increasing trend of outsourcing repair services to specialized third-party providers. Businesses are focusing on cost reduction and efficiency by entrusting repair and maintenance to external service providers, who offer expertise and streamlined processes. A report by Deloitte highlights that over 60% of companies in the U.S. outsource some aspect of their after-sales services, including repairs, to reduce operational costs while maintaining equipment longevity and performance. This outsourcing trend significantly boosts the demand for depot repair services.
Expansion of the Aerospace and Defence Sectors:
The aerospace and defence sectors are also driving growth in the depot repair service market. Both industries rely heavily on the maintenance and repair of complex systems and machinery to ensure optimal functionality and safety. According to data from the Aerospace Industries Association, the U.S. aerospace and defence sector grew by nearly 6% in 2022, driving higher demand for specialized repair services to maintain equipment used in critical operations. This demand extends globally, as governments invest in military modernization and aviation infrastructure.
Government Regulations and Compliance:
Government regulations on equipment maintenance and safety standards play a significant role in driving the market. Regulatory bodies such as the U.S. Occupational Safety and Health Administration (OSHA) mandate regular maintenance checks for industrial equipment to prevent failures and accidents. Similarly, the European Union has stringent regulations around equipment safety and repair, further increasing the need for dependable depot repair services. These compliance requirements compel businesses to invest in regular repair and refurbishment services, fostering market growth.
Market Trends:
Rise of Predictive Maintenance:
One significant trend in the Depot Repair Service Market is the increasing use of predictive maintenance technologies. Companies are leveraging data analytics and IoT (Internet of Things) sensors to predict equipment failures before they occur. For instance, GE Aviation has implemented predictive maintenance in its aircraft engines, allowing operators to address potential issues proactively. This approach reduces unexpected downtime and ensures equipment longevity, boosting the demand for predictive and preemptive repair services in depot facilities.
Integration of Advanced Technologies:
The integration of advanced technologies like AI, machine learning, and automation in depot repair services is gaining traction. Automated diagnostic systems are increasingly being used to identify issues in complex machinery quickly and accurately. For example, Siemens introduced AI-powered maintenance solutions that can analyze machine performance and predict wear and tear. These technologies enable service providers to enhance repair accuracy, reduce human error, and expedite repair processes, ultimately improving service efficiency.
Growing Focus on Sustainability:
Sustainability is becoming a key focus within depot repair services. Many companies are adopting eco-friendly practices in their repair operations by reusing components, reducing waste, and recycling materials. Governments are also encouraging sustainable business practices through regulations and incentives. For example, the European Union’s Circular Economy Action Plan aims to promote the reuse and recycling of electronic components, driving the demand for repair services that focus on refurbishing rather than replacing equipment.
Expansion of Service Contracts:
Another trend in the depot repair market is the growing prevalence of long-term service contracts. Industries like healthcare, aerospace, and telecommunications are increasingly entering into extended service agreements with repair service providers to ensure consistent maintenance and lower costs. A survey by McKinsey found that over 70% of industrial firms in the U.S. prefer long-term contracts to handle maintenance, reducing the risk of unexpected equipment failures and ensuring that devices remain operational throughout their lifecycle.
Market Challenges Analysis:
High Cost of Advanced Technologies:
One of the key restraints in the Depot Repair Service Market is the high cost of implementing advanced repair technologies, such as artificial intelligence (AI), automation, and predictive maintenance systems. While these technologies improve repair efficiency and accuracy, their integration requires significant investment in infrastructure, skilled personnel, and training. Small and medium-sized enterprises (SMEs), in particular, face challenges in adopting these high-tech solutions, which can limit their ability to compete with larger service providers. The initial cost of implementing advanced repair technologies can act as a barrier to entry for many companies.
Shortage of Skilled Technicians:
Another major challenge in the market is the growing shortage of skilled technicians capable of handling complex repairs, particularly for specialized equipment used in industries like aerospace, defence, and healthcare. According to the U.S. Department of Labor, the manufacturing and maintenance sectors are experiencing a skills gap, with a significant portion of the workforce nearing retirement and fewer young workers entering these fields. This shortage makes it difficult for depot repair service providers to meet the growing demand for complex repair services, which require specialized training and expertise.
Supply Chain Disruptions:
Supply chain disruptions are another challenge facing the depot repair service market. The global supply chain, particularly for electronic components and specialized parts, has been significantly affected by events such as the COVID-19 pandemic and geopolitical tensions. These disruptions can lead to delays in acquiring necessary components for repairs, resulting in extended downtime for clients and affecting service providers' ability to meet timelines and contractual obligations. The increasing reliance on global supply chains further complicates the ability to source parts quickly and efficiently, adding pressure to the market.
Market Segmentation Analysis:
By Type, the market is divided into in-warranty and out-of-warranty services. In-warranty services dominate the market, as many manufacturers offer repair services as part of their product warranties, ensuring equipment longevity and reducing operational downtime. Out-of-warranty services are also essential, particularly for industries that rely on extending the life cycle of expensive equipment.
By Technology, the market is segmented into traditional repair services and advanced technology-based services. Traditional services focus on manual repair and refurbishment, while advanced services leverage predictive maintenance, AI, and automation. Predictive maintenance technologies, such as IoT-enabled sensors and AI-powered diagnostics, are becoming more prevalent, enabling service providers to detect potential issues before they result in equipment failure, thereby reducing costly downtime.
By End User, the market includes sectors such as aerospace, automotive, telecommunications, healthcare, and consumer electronics. The telecommunications and automotive sectors are leading end users, driven by the need for regular maintenance and repair of complex electronics and machinery. The healthcare and aerospace industries are also significant users of depot repair services, relying heavily on maintaining the operational efficiency of highly specialized equipment.
Segmentation:
By Repair Type:- Electronics Repair
- IT Equipment Repair
- Consumer Appliance Repair
- Industrial Equipment Repair
- Medical Equipment Repair
- Automotive Equipment Repair
- Others
- Standard Repair Services
- Expedited Repair Services
- Computers and Laptops
- Smartphones and Tablets
- Printers and Scanners
- Home Appliances
- Industrial Machinery
- Medical Devices
- Automotive Components
- Others
- Information Technology
- Electronics
- Healthcare
- Automotive
- Manufacturing
- Retail
- Others
- On-site Repair Services
- Off-site/Depot Repair Services
- Original Equipment Manufacturer (OEM)
- Third-Party Service Providers
- Independent Repair Shops
- Circuit Board Repair
- Power Supply Repair
- Display Repair
- Chipset Repair
- Other Component-level Repairs
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the Depot Repair Service Market, contributing approximately 35% of the global market. This dominance is driven by the region’s advanced industrial base and the presence of key industries such as aerospace, healthcare, and telecommunications, all of which rely on sophisticated equipment requiring regular maintenance. The United States, in particular, leads the region due to the increasing demand for repair services in sectors like electronics and automotive, where technological advancements are rapid. Moreover, the outsourcing of repair services to specialized third-party providers is a growing trend in the region, driven by the need to reduce operational costs. The presence of numerous leading service providers and advanced repair technologies further solidifies North America’s position in the market.
Europe
Europe accounts for around 30% of the global Depot Repair Service Market share. The region’s strong presence is fueled by the high demand for repair services in the automotive and electronics sectors. Countries like Germany, the UK, and France have well-established industries that depend on regular maintenance of complex equipment, particularly in manufacturing and automotive sectors. The European Union’s stringent regulations regarding equipment safety and operational efficiency drive the need for reliable depot repair services. Additionally, the rising trend of sustainability and the focus on extending equipment lifecycles through repair and refurbishment instead of replacement further boost the demand for depot repair services in this region.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the Depot Repair Service Market, with a market share of approximately 25%. Rapid industrialization, increasing demand for consumer electronics, and the growth of the automotive industry are key factors driving the market. Countries like China, Japan, and India are leading in this region, with China emerging as a major hub for electronics manufacturing. The demand for after-sales services, including depot repair, is growing as more businesses outsource maintenance to third-party providers to focus on their core operations. Additionally, the rise in infrastructure development and industrial automation across Asia-Pacific is contributing to the increasing need for repair services.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively contribute to around 10% of the global Depot Repair Service Market. In Latin America, countries like Brazil and Mexico are seeing steady growth in industrial sectors, leading to increased demand for equipment maintenance and repair services. The Middle East, particularly in nations like Saudi Arabia and the UAE, is focused on expanding its industrial base, especially in oil & gas and telecommunications, both of which require regular equipment servicing. Though these regions currently hold a smaller market share, the increasing focus on industrial development and modernization presents significant opportunities for growth in depot repair services.
Key Player Analysis:
- IBM Corporation
- Siemens AG
- Boeing Company
- Honeywell International Inc.
- General Electric (GE)
- Lockheed Martin Corporation
- Samsung Electronics
- Jabil Inc.
- Flex Ltd.
- Ricoh Company, Ltd.
Competitive Analysis:
The Depot Repair Service Market is characterized by intense competition among key players, including IBM Corporation, Siemens AG, Boeing, and Honeywell International Inc., who lead with extensive service portfolios and strong global footprints. These companies provide comprehensive repair and refurbishment services across various industries, such as aerospace, telecommunications, and consumer electronics. Players like Samsung Electronics and Flex Ltd. dominate the consumer electronics repair segment, leveraging advanced technologies such as AI and predictive maintenance tools to enhance service efficiency. Meanwhile, General Electric (GE) and Lockheed Martin excel in servicing complex industrial and defence equipment. The market is highly competitive due to the increasing demand for outsourcing repair services, where companies focus on offering value-added services like lifecycle management and sustainable refurbishment solutions. Continuous innovation in repair processes and the integration of advanced technologies such as IoT and automation further intensify competition.
Recent Developments:
- IBM introduced a suite of new AI-powered offerings in 2024 for its watsonx platform, enhancing depot repair services by streamlining workflows and improving efficiency in diagnosing and addressing repair issues. This innovation reflects IBM’s commitment to integrating AI into repair services, aiming to reduce downtime and improve customer service across multiple industries.
- Honeywell in 2023 expanded its aerospace repair services, particularly focusing on predictive maintenance tools that leverage AI to anticipate potential system failures before they occur. This helps minimize costly downtime in aviation and defence sectors while ensuring equipment reliability.
- In 2023, Dell Technologies upgraded its depot repair services by incorporating IoT-based diagnostics into its offerings, allowing for real-time monitoring of equipment health. This development ensures faster response times and enhances Dell’s capability to offer remote and depot-level repair services to its global customer base.
- HP Inc. in 2022 launched a new initiative to recycle and refurbish IT equipment as part of its sustainability efforts. This initiative aims to reduce e-waste by extending the lifecycle of hardware through depot repair services, particularly for enterprise clients seeking more environmentally friendly solutions.
Market Concentration & Characteristics:
The Depot Repair Service Market is moderately fragmented, with a few major players such as IBM Corporation, HP Inc., and Dell Technologies Inc. dominating the market, alongside numerous smaller service providers. These key players hold a significant market share due to their extensive global presence, advanced technological capabilities, and diversified service offerings. Large companies are increasingly integrating technologies such as AI, IoT, and predictive maintenance to enhance service efficiency and accuracy. The market is characterized by the growing trend of outsourcing repair services to third-party providers, especially in industries like telecommunications, consumer electronics, and aerospace. Service providers are focusing on delivering sustainable repair solutions, aligning with corporate goals to reduce e-waste and extend product lifecycles. While the market shows moderate concentration, it remains competitive due to technological advancements and the increasing demand for customized and rapid repair services across various industries.
Report Coverage:
The research report offers an in-depth analysis based on Repair Type, Service Level, Equipment Type, and Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for advanced repair technologies, such as AI and IoT-based diagnostics, will increase, enabling faster and more efficient repairs.
- Predictive maintenance will play a crucial role in reducing downtime and improving the lifespan of equipment across industries like aerospace, healthcare, and telecommunications.
- Companies will focus on sustainability by integrating recycling and refurbishment into their depot repair services to reduce e-waste.
- The growing trend of outsourcing repair services will continue, as companies seek cost-efficient solutions to manage complex equipment.
- The healthcare sector will see significant growth in depot repair services due to the rising adoption of advanced medical devices and equipment.
- Integration of cloud-based solutions in depot repair services will enhance data tracking and real-time monitoring, improving service efficiency.
- Small and medium-sized enterprises (SMEs) will adopt depot repair services to extend the lifecycle of their equipment and reduce operational costs.
- The rise in 5G technology will increase the demand for telecommunications equipment repairs, creating more opportunities for depot repair service providers.
- Government regulations mandating regular maintenance of industrial equipment will drive the need for repair services across sectors.
- Global supply chain disruptions may impact the availability of spare parts, challenging service providers to maintain timely repairs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Depot Repair Service Market?
What factors are driving the growth of the Depot Repair Service Market?
What are some challenges faced by the Depot Repair Service Market?
Who are the major players in the Depot Repair Service Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Depot Repair Service Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Depot Repair Service Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 29,005 million → 2032: USD 50,208.95 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Depot Repair Service Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Depot Repair Service Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Depot Repair Service Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Depot Repair Service Market Drivers
- 3.3 Depot Repair Service Market Restraints & Challenges
- 3.4 Depot Repair Service Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Depot Repair Service Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Depot Repair Service Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Depot Repair Service category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Depot Repair Service Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Depot Repair Service Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Depot Repair Service. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Depot Repair Service Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Depot Repair Service Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Depot Repair Service Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Depot Repair Service (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Depot Repair Service
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Depot Repair Service Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Depot Repair Service Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Depot Repair Service Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Depot Repair Service Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Depot Repair Service Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Depot Repair Service Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Depot Repair Service Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Depot Repair Service Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
