
Market Overview:
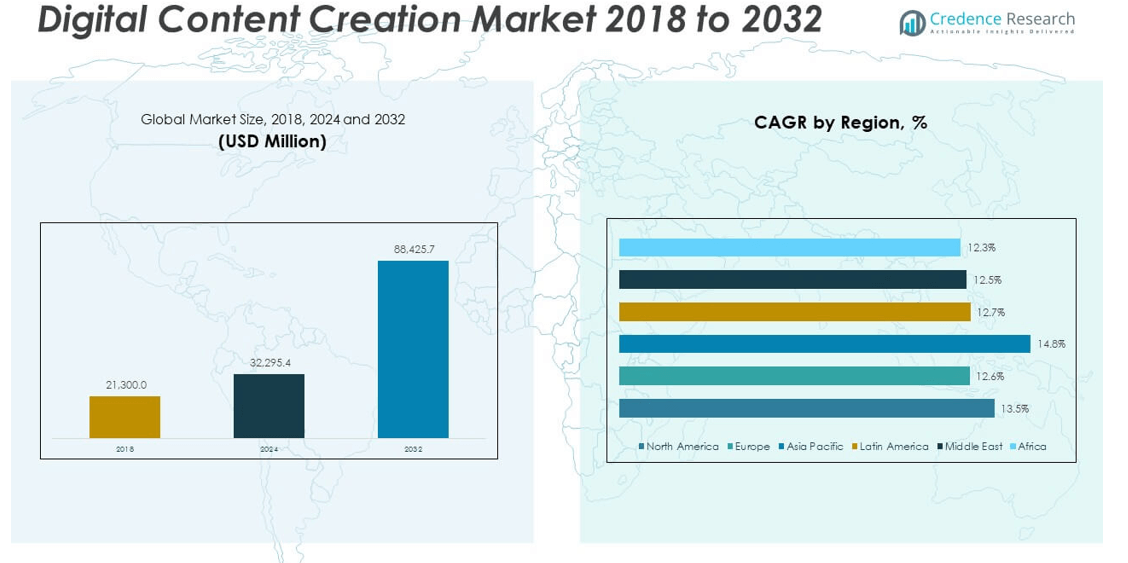
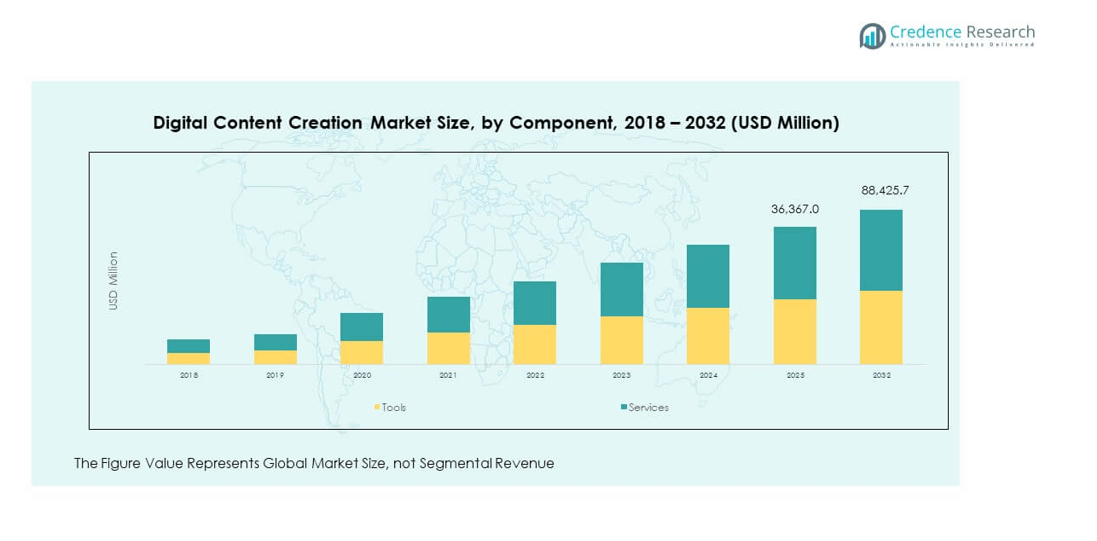
The Global Digital Content Creation Market size was valued at USD 21,300.0 million in 2018 to USD 32,295.4 million in 2024 and is anticipated to reach USD 88,425.7 million by 2032, at a CAGR of 13.50% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Content Creation Market Size 2024 | USD 32,295.4 million |
| Digital Content Creation Market, CAGR | 13.50% |
| Digital Content Creation Market Size 2032 | USD 88,425.7 million |
The market grows due to rising demand for personalized, high-quality digital media across industries, fueled by expanding internet penetration and the rapid adoption of smart devices. Businesses increasingly leverage digital content to enhance customer engagement, support e-commerce growth, and strengthen brand presence. Advancements in content creation tools, cloud-based platforms, and AI-driven design solutions further accelerate adoption, enabling creators to produce interactive, scalable, and visually rich content efficiently.
North America leads the market, driven by strong technological infrastructure, high content consumption, and the presence of major digital media companies. Europe follows with robust adoption in e-learning, marketing, and entertainment sectors. Asia-Pacific emerges as the fastest-growing region, propelled by rising smartphone use, booming social media engagement, and a thriving creator economy in countries like India and China.\
Market Insights:
- The Global Digital Content Creation Market was valued at USD 21,300.0 million in 2018, reached USD 32,295.4 million in 2024, and is projected to attain USD 88,425.7 million by 2032, registering a CAGR of 13.50% during the forecast period.
- Rising digital transformation across industries and the shift from traditional to online marketing drive demand for high-quality, engaging content.
- Technological advancements in AI, AR/VR, and automation improve creative capabilities, reduce production time, and enhance efficiency.
- Content saturation across platforms creates challenges in capturing and retaining audience attention.
- High skill and investment requirements for advanced content formats limit participation by smaller creators and enterprises.
- North America leads due to strong technological infrastructure and major market players, followed by Europe with robust adoption in education, marketing, and entertainment.
- Asia-Pacific emerges as the fastest-growing region, driven by smartphone adoption, social media expansion, and a thriving creator economy in India and China.
Market Drivers:
Rising Digital Transformation Across Industries Accelerating Content Demand:
The Global Digital Content Creation Market benefits from the widespread adoption of digital transformation strategies across industries such as retail, healthcare, education, and media. Organizations prioritize high-quality, interactive content to engage customers and improve brand visibility. The rapid shift from traditional to digital marketing channels strengthens demand for visual and multimedia content. Social media platforms drive a need for continuous and personalized updates. Cloud-based solutions enable scalability and cost efficiency for content production. AI-powered tools enhance efficiency, enabling creators to deliver targeted and relevant experiences. The growth of e-commerce platforms increases the demand for product visuals, videos, and promotional material. Rising competition among brands pushes investment in professional-grade content to capture audience attention.
- For instance, Adobe Sensei’s generative AI capabilities within Adobe Experience Manager (AEM) empower content teams at major retailers like Nike to automate the production of personalized content variations, reducing content creation time by approximately 30% and enabling dynamic adaptation of web and marketing assets at scale in 2024. Adobe GenStudio further automates campaign creation, helping marketers create and optimize thousands of performance marketing assets efficiently.
Advancements in Technology Driving Creative Capabilities and Efficiency:
Technological innovations significantly enhance the creative process in the Global Digital Content Creation Market. AI, machine learning, and automation streamline editing, design, and publishing workflows. Augmented reality (AR) and virtual reality (VR) tools expand possibilities for immersive storytelling. High-resolution video production capabilities improve visual appeal. Integration with advanced analytics allows businesses to measure engagement and optimize strategies. Mobile applications give creators flexibility to produce content anywhere. Affordable access to professional-grade software lowers entry barriers for small and mid-sized businesses. Cloud collaboration tools improve teamwork across geographies. Such developments collectively improve production speed, reduce costs, and enhance quality.
- For instance, Adobe Sensei’s AI-driven features include auto-reframe for videos that automatically adjust aspect ratios, boosting video editing speed by over 40%, and intelligent image tagging that reduces manual metadata assignment by 70%.
Increasing Influence of Social Media and User-Generated Content:
Social media platforms remain a critical driver for the Global Digital Content Creation Market. Constant updates from brands, influencers, and consumers create a competitive environment for engaging posts, videos, and live content. The popularity of short-form video formats amplifies demand for quick, high-impact creation tools. User-generated content fosters authenticity, which drives higher audience engagement. Brands increasingly collaborate with influencers to produce relatable and persuasive campaigns. Integration of social commerce features blends content with sales opportunities. Viral trends push creators to adapt quickly to evolving formats. Content creation platforms now offer templates optimized for different platforms to ensure consistency. The synergy between social media growth and digital content tools sustains strong market expansion.
Expanding E-Learning and Remote Work Culture Boosting Digital Content Adoption:
The growing adoption of e-learning platforms and remote work systems strengthens demand in the Global Digital Content Creation Market. Educational institutions require interactive and visually rich materials for online classes. Businesses rely on training videos, webinars, and virtual presentations for remote workforce engagement. The shift to hybrid events fuels demand for high-quality virtual production. Video conferencing integrations allow for real-time collaboration on creative projects. Demand for localized content rises to cater to diverse audiences. Instructional content, simulations, and explainer videos see significant growth. These trends are supported by the rising availability of affordable tools and improved internet access. The blend of professional and educational needs continues to expand the scope of digital content solutions.
Market Trends:
Growing Popularity of Immersive and Interactive Content Experiences:
The Global Digital Content Creation Market witnesses an increasing shift toward immersive and interactive experiences. AR and VR technologies enable users to engage with content beyond static visuals. Interactive videos allow audiences to choose narratives or explore detailed product views. 360-degree photography offers virtual tours for industries like real estate and tourism. Gaming-inspired interfaces bring engagement to training and marketing materials. Mixed reality applications enhance storytelling in education and retail. Tools for creating such content become more accessible, broadening adoption across business sizes. This evolution aligns with consumer preferences for more personalized and engaging content consumption.
Integration of AI-Driven Content Personalization and Automation:
AI-driven personalization is a defining trend in the Global Digital Content Creation Market. Businesses use data analytics to deliver targeted and contextually relevant experiences. Automation reduces repetitive tasks, allowing creators to focus on strategic and creative elements. Natural language processing enables AI to assist in scriptwriting and text generation. Predictive analytics helps determine optimal publishing times and formats. Automated editing tools speed up production cycles. AI also powers real-time translation, expanding global reach. These capabilities make content creation more agile and data-driven, enhancing engagement and conversion rates. The trend is expected to strengthen as AI capabilities mature.
- For instance, Adobe Sensei leverages predictive analytics to optimize content delivery by forecasting cross-channel campaign performance and prioritizing high-value leads through AI-based scoring, boosting email open rates by up to 35% for users of AI-powered marketing tools. Automated tagging and metadata generation improve asset discoverability by over 50%, enabling faster content reuse and personalization at scale within enterprise environments.
Adoption of Cross-Platform Content Strategies for Wider Audience Reach:
Content strategies increasingly focus on cross-platform adaptability in the Global Digital Content Creation Market. Businesses prioritize creating assets that can be optimized for multiple channels. Tools that repurpose videos, graphics, and articles for varied formats see higher adoption. Consistency across platforms ensures brand recognition and messaging clarity. Integration features enable simultaneous publishing across social media, websites, and e-commerce portals. Analytics dashboards provide performance insights from all channels in one place. Creators adopt responsive design principles to cater to different devices. This trend supports cost efficiency while maximizing audience engagement across the digital ecosystem.
Emergence of Subscription-Based Content Creation Tools and Services:
Subscription-based models gain prominence in the Global Digital Content Creation Market. Affordable monthly or annual plans make advanced tools accessible to startups and freelancers. These models often include regular software updates, cloud storage, and premium templates. The flexibility to scale subscriptions according to project needs appeals to businesses. Collaborative features in subscription packages enhance productivity for distributed teams. Pay-as-you-go plans reduce upfront investment for small enterprises. Access to bundled creative assets and training materials improves efficiency. This shift supports a more democratized content creation environment, enabling wider participation in the market.
Market Challenges Analysis:
Content Saturation and Increasing Competition for Audience Attention:
The Global Digital Content Creation Market faces challenges from growing content saturation across platforms. With millions of videos, articles, and images uploaded daily, standing out becomes difficult. Audiences have limited attention spans, forcing creators to develop high-impact content quickly. The competitive environment increases the cost of acquiring and retaining viewers. Smaller players struggle against established brands with larger budgets. Maintaining originality in an environment flooded with similar formats is challenging. Rapid trend shifts require constant adaptation, straining resources. Algorithm changes on major platforms can significantly impact content visibility. Sustaining consistent engagement remains a persistent challenge.
High Skill and Resource Requirements for Advanced Content Production:
Advanced digital content production often demands significant technical skills and financial investment in the Global Digital Content Creation Market. Professional-grade visuals, animations, and interactive formats require expertise in specialized software. Small businesses and independent creators may find it difficult to compete without access to skilled professionals. High-quality equipment, such as cameras, editing systems, and graphic design tools, adds to costs. Training to keep up with emerging tools and techniques is time-consuming. Balancing creativity with technical execution can slow production cycles. Inexperienced teams may struggle to integrate new technologies effectively. These barriers can limit innovation and scalability in the sector.
Market Opportunities:
Rising Demand for Localized and Culturally Relevant Digital Content:
The Global Digital Content Creation Market holds significant opportunity in localized content production. Brands increasingly tailor their materials to reflect cultural nuances, languages, and regional preferences. This personalization improves engagement in diverse markets. AI-powered translation and voice-over tools make localization faster and more affordable. Regional storytelling approaches enhance authenticity and trust. Demand is particularly strong in emerging markets with rapidly growing online audiences. Companies investing in local influencer partnerships gain deeper market penetration. The potential for growth in this segment is substantial as brands aim for global reach with local resonance.
Expansion of Niche Content Verticals and Specialized Industries:
Specialized industries present lucrative growth avenues in the Global Digital Content Creation Market. Sectors such as telemedicine, e-learning, virtual tourism, and gaming demand highly customized visual and interactive solutions. Businesses seek content that addresses technical, educational, or entertainment-specific needs. Niche audiences value expertise and targeted communication. Partnerships with industry specialists can yield high-quality outputs that meet sector standards. The rise of community-driven platforms supports engagement in focused content ecosystems. Leveraging expertise in niche verticals offers competitive differentiation. This creates sustainable growth pathways for creators and service providers alike.
Market Segmentation Analysis:
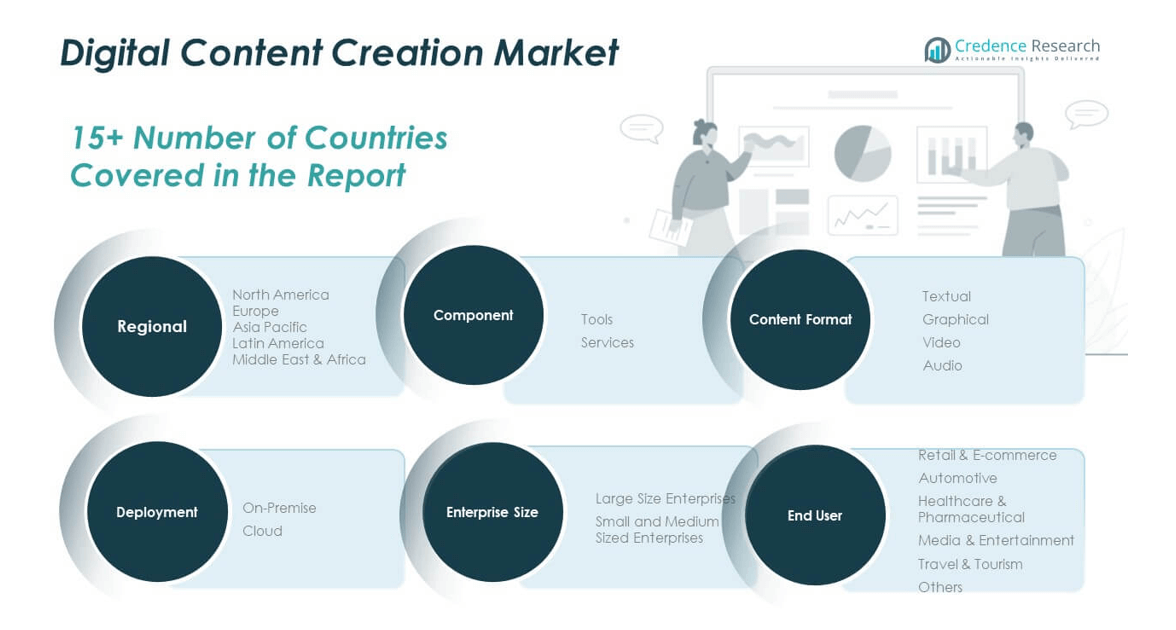
By Component
The Global Digital Content Creation Market is divided into tools and services. Tools hold a significant share, driven by the adoption of advanced software for design, editing, and publishing tasks. Services see rising demand as businesses seek professional expertise for tailored content strategies and execution. Both segments complement each other, with tools enabling production efficiency and services ensuring strategic alignment with brand objectives.
- For instance, Adobe’s Creative Cloud suite (including Photoshop, Premiere Pro, and Illustrator) remains one of the most deployed toolsets, while cloud-based design tool Figma has become a cornerstone for collaborative UI/UX development, adopted by leading global brands for its vector technology and real-time collaboration features.
By Content Format
The market is categorized into textual, graphical, video, and audio formats. Video leads in growth due to its strong engagement potential across marketing, education, and entertainment. Graphical content continues to be essential for branding and digital advertising, while audio gains prominence with the rise of podcasts and voice-based platforms. Textual formats remain relevant for blogs, articles, and SEO-driven content strategies.
- For instance, platforms like Canva and Adobe Illustrator are extensively used globally for infographics and visual campaigns. Audio is rapidly gaining traction due to the rise of podcast platforms and streaming services, while textual formats continue to form the backbone of blogs, articles, and SEO-driven digital publishing strategies for brands and agencies alike.
By End-User
End-user segments include retail & e-commerce, automotive, healthcare & pharmaceutical, media & entertainment, travel & tourism, and others. Media & entertainment dominates, supported by streaming services and advertising needs. Retail & e-commerce rapidly adopt digital content to enhance product visualization and consumer engagement. Healthcare, travel, and automotive sectors leverage content for education, marketing, and brand positioning.
By Deployment
Deployment models consist of on-premise and cloud solutions. On-premise appeals to enterprises prioritizing data control and security. Cloud deployment grows faster, offering scalability, cost-efficiency, and flexibility for remote teams. The shift toward hybrid work models further accelerates cloud adoption.
By Enterprise Size
The market serves large enterprises and small and medium-sized enterprises (SMEs). Large enterprises invest heavily in advanced tools and services for brand differentiation. SMEs experience steady growth, supported by affordable subscription-based platforms and the need to compete in the digital space.
Segmentation:
- By Component
- Tools
- Services
- By Content Format
- Textual
- Graphical
- Video
- Audio
- By End-User
- Retail & E-commerce
- Automotive
- Healthcare & Pharmaceutical
- Media & Entertainment
- Travel & Tourism
- Others
- By Deployment
- On-Premise
- Cloud
- By Enterprise Size
- Large Size Enterprises
- Small and Medium Sized Enterprises
- By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
- North America
Regional Analysis:
North America
The North America Global Digital Content Creation Market size was valued at USD 7,361.3 million in 2018 to USD 11,019.0 million in 2024 and is anticipated to reach USD 30,120.3 million by 2032, at a CAGR of 13.5% during the forecast period. It holds approximately 34.1% of the global market share in 2024. The region benefits from advanced technological infrastructure and the presence of leading content creation platforms and software providers. High internet penetration, robust e-commerce ecosystems, and strong social media engagement fuel demand. Businesses invest heavily in video marketing, AR/VR experiences, and influencer-driven campaigns. The growing adoption of cloud-based collaboration tools supports efficiency for remote creative teams. Entertainment, gaming, and e-learning sectors remain major revenue contributors. Innovation hubs in the US and Canada continuously drive advancements in content production capabilities. The competitive landscape encourages rapid adoption of emerging technologies, sustaining strong growth in the region.
Europe
The Europe Global Digital Content Creation Market size was valued at USD 5,026.8 million in 2018 to USD 7,291.4 million in 2024 and is anticipated to reach USD 18,724.4 million by 2032, at a CAGR of 12.6% during the forecast period. It accounts for about 22.6% of the global market share in 2024. The region benefits from strong creative industries, well-established advertising networks, and expanding digital infrastructure. Adoption of interactive marketing campaigns and data-driven personalization continues to rise. Countries such as the UK, Germany, and France lead innovation in branded content and digital storytelling. The growing demand for multilingual and localized content supports pan-European market growth. Regulations around data privacy encourage the use of secure content management solutions. E-learning adoption in corporate and academic sectors boosts the need for interactive educational materials. Cultural diversity and a thriving design community position Europe as a creative leader in the global market.
Asia Pacific
The Asia Pacific Global Digital Content Creation Market size was valued at USD 5,388.9 million in 2018 to USD 8,521.0 million in 2024 and is anticipated to reach USD 25,593.1 million by 2032, at a CAGR of 14.8% during the forecast period. It holds around 26.4% of the global market share in 2024. Rapid smartphone adoption, expanding internet penetration, and booming social media usage drive the market. Countries like China, India, and Japan lead in digital innovation and online content consumption. E-commerce platforms invest in high-quality visuals and live-streaming content to attract customers. Government initiatives in digital infrastructure and entrepreneurship boost creator economies. Affordable mobile-based content creation tools encourage participation from small businesses and independent creators. Gaming, entertainment, and online education sectors are major growth engines. The region’s diverse cultural landscape fosters demand for localized and engaging content across multiple languages.
Latin America
The Latin America Global Digital Content Creation Market size was valued at USD 1,597.5 million in 2018 to USD 2,402.5 million in 2024 and is anticipated to reach USD 6,179.2 million by 2032, at a CAGR of 12.7% during the forecast period. It represents roughly 7.4% of the global market share in 2024. Growth is supported by rising social media engagement and increasing digital marketing investments by businesses. Brazil and Mexico lead in online content adoption, fueled by high mobile usage. Regional brands focus on producing culturally relevant and interactive content to strengthen engagement. Influencer marketing plays a vital role in brand communication strategies. Expanding internet connectivity in rural areas opens new opportunities for digital reach. The gaming and entertainment sectors contribute significantly to demand. Cloud-based tools and affordable subscription models improve accessibility for small creators and startups.
Middle East
The Middle East Global Digital Content Creation Market size was valued at USD 1,114.0 million in 2018 to USD 1,611.3 million in 2024 and is anticipated to reach USD 4,103.4 million by 2032, at a CAGR of 12.5% during the forecast period. It commands approximately 5% of the global market share in 2024. The region experiences growth from expanding digital economies in countries like the UAE and Saudi Arabia. Government initiatives to promote innovation and entrepreneurship support the market’s development. High demand for Arabic-language content drives localized production. The retail and tourism sectors invest heavily in digital marketing campaigns and immersive experiences. Social media penetration remains among the highest globally, increasing the need for high-quality visuals and videos. Entertainment and sports broadcasting also contribute to demand. The region’s strategic location encourages cross-border digital content collaborations.
Africa
The Africa Global Digital Content Creation Market size was valued at USD 811.5 million in 2018 to USD 1,450.2 million in 2024 and is anticipated to reach USD 3,705.3 million by 2032, at a CAGR of 12.3% during the forecast period. It accounts for about 4.5% of the global market share in 2024. Growth is fueled by rising mobile internet penetration and affordable smartphones. Social media platforms are increasingly used for marketing, education, and entertainment purposes. Nigeria, South Africa, and Kenya lead in digital content adoption. Local startups and entrepreneurs leverage content creation to reach expanding online audiences. The e-learning sector shows strong potential, especially in remote education initiatives. Cloud-based and mobile-friendly content tools make creation more accessible. International collaborations with African creators boost visibility and market engagement.
Key Player Analysis:
- Microsoft Corporation
- Picsart
- Adobe Systems
- Corel Corporation
- Acrolinx
- Google LLC
- Integra Software Services
- MarketMuse, Inc.
- Quark Software Inc.
- Canva
Competitive Analysis:
The Global Digital Content Creation Market is highly competitive, with players focusing on technological innovation, diversified service offerings, and global reach to strengthen their position. Established companies leverage advanced AI, AR/VR, and automation tools to enhance creative capabilities and efficiency. Emerging players compete through cost-effective, subscription-based solutions targeting SMEs and independent creators. Strategic partnerships, acquisitions, and product launches remain key growth tactics. Industry leaders such as Adobe Systems, Microsoft Corporation, Canva, and Google LLC maintain dominance through robust product portfolios and strong customer bases. Intense rivalry drives continuous innovation, rapid adoption of cloud-based solutions, and expansion into emerging markets.
Recent Developments:
- In May 2025, at Microsoft Build 2025, Microsoft revealed over 50 new AI tools intended to transform the future of the internet, dubbed the "agentic web." These tools encompass AI-driven capabilities across search, content creation, automation, and enterprise infrastructure, laying the foundation for autonomous AI agents that can independently operate and interact with users and data. This bold move aims to revolutionize content creation workflows and digital interaction on a broad scale.
- In August 2025, Microsoft shared insights into its vision for the AI-powered workplace of the future. The company is empowering employees to build their own AI agents to enhance productivity and creativity, underpinned by robust governance and security measures. This internal digital transformation journey offers a blueprint for other enterprises to accelerate their AI adoption in content creation and beyond.
Market Concentration & Characteristics:
The Global Digital Content Creation Market demonstrates moderate to high concentration, with a few dominant players holding substantial market shares. It is characterized by rapid technological advancements, strong demand across multiple industries, and increasing adoption of cloud-based content creation tools. The market shows high innovation intensity, driven by AI integration, immersive content technologies, and user-friendly design platforms. Competition is dynamic, with both global enterprises and niche startups targeting specific segments and formats.
Report Coverage:
The research report offers an in-depth analysis based on component and content format. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-powered personalization will dominate content strategies.
- AR/VR will drive immersive brand experiences.
- Cloud-based platforms will see increased enterprise adoption.
- Short-form video content will remain a growth leader.
- Localization will become critical for global expansion.
- Influencer-driven content will shape marketing investments.
- E-learning and training content demand will rise.
- Cross-platform publishing will become standard practice.
- Subscription-based creative tools will expand user base.
- Data-driven content optimization will gain priority.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Transformation Across Industries
Organizations in sectors such as retail, healthcare, education, and media are prioritizing digital transformation, leading to increased investment in high-quality, interactive digital content to engage customers and enhance brand visibility.
Advancements in AI, AR/VR, and Automation
Technological innovations like AI-powered editing, AR/VR storytelling, and workflow automation are streamlining content creation, reducing production time, and enabling more immersive and personalized content experiences.
Proliferation of Social Media and User-Generated Content
The rise of social media platforms and influencer marketing is driving demand for quick, engaging, and authentic digital content, pushing brands and creators to adopt advanced tools for rapid content production and cross-platform publishing.
Expansion of E-Learning and Remote Work
The growth of e-learning platforms and remote work culture is fueling demand for digital training materials, webinars, and virtual presentations, increasing the need for scalable and collaborative content creation solutions.
Localization and Personalization Needs
Brands are increasingly seeking to tailor content for diverse global audiences, leveraging AI-driven translation and personalization tools to create culturally relevant and engaging digital experiences in multiple languages and regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the digital content creation market?
What are the key drivers of the digital content creation market?
How are technological innovations impacting the digital content creation market?
Which regions are leading the digital content creation market?
Why is the digital content creation market expanding rapidly?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Retail & E-commerce
- 1.2.2 Media & Entertainment
- 1.2.3 Healthcare & Pharmaceutical
- 1.2.4 Automotive
- 1.2.5 Travel & Tourism
- 1.2.6 Others
- 1.3 By Component
- 1.3.1 Tools
- 1.3.2 Services
- 1.4 By Deployment
- 1.4.1 On-Premise
- 1.4.2 Cloud
- 1.5 By Content Format
- 1.5.1 Textual
- 1.5.2 Graphical
- 1.5.3 Video
- 1.5.4 Audio
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 32,295.4 million → 2032: USD 88,425.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Digital Content Creation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Digital Content Creation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Digital Content Creation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Digital Content Creation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Digital Content Creation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Digital Content Creation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Digital Content Creation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Digital Content Creation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 32,295.4 million → 2032: USD 88,425.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Digital Content Creation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Retail & E-commerce
- 12.3.7.2 Media & Entertainment
- 12.3.7.3 Healthcare & Pharmaceutical
- 12.3.7.4 Automotive
- 12.3.7.5 Travel & Tourism
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Tools
- 12.4.7.2 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premise
- 12.5.7.2 Cloud
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Content Format - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Textual
- 12.6.7.2 Graphical
- 12.6.7.3 Video
- 12.6.7.4 Audio
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Digital Content Creation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Digital Content Creation Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Digital Content Creation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Digital Content Creation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Adobe Systems
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 Google LLC
- 18.5 Canva
- 18.6 Picsart
- 18.7 Corel Corporation
- 18.8 Acrolinx
- 18.9 Quark Software Inc.
- 18.10 Integra Software Services
- 18.11 MarketMuse, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

