
Market Overview:
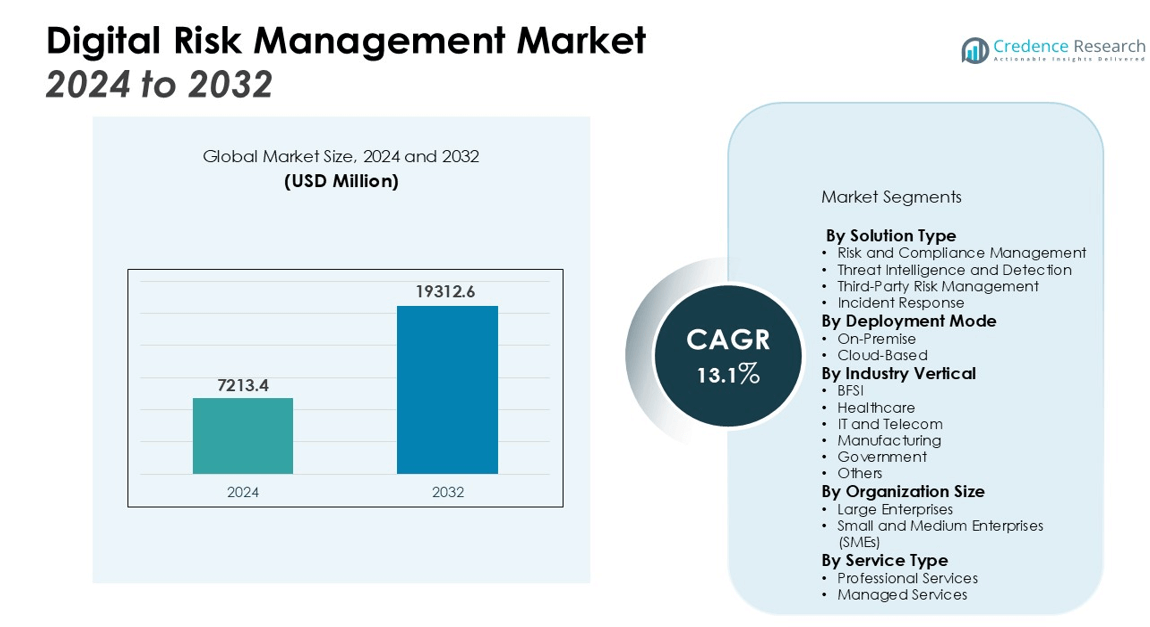
The Digital Risk Management Market size was valued at USD 7213.4 million in 2024 and is anticipated to reach USD 19312.6 million by 2032, at a CAGR of 13.1% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Risk Management Market Size 2024 | USD 7213.4 million |
| Digital Risk Management Market, CAGR | 13.1% |
| Digital Risk Management Market Size 2032 | USD 19312.6 million |
Market expansion is driven by the surge in cyber-attacks, rapid regulatory changes, and the growing reliance on cloud computing, IoT, and advanced analytics. Enterprises are integrating third-party risk management, AI-powered threat detection, and automated incident response into their frameworks to strengthen resilience. The demand for scalable, cloud-based platforms that offer real-time risk visibility is rising, as companies aim to align their digital risk approaches with overall enterprise risk management strategies. Additionally, the increasing focus on proactive risk intelligence and predictive analytics is enabling organizations to anticipate threats before they escalate.
North America holds the largest share due to its mature cybersecurity infrastructure, advanced technology adoption, and stringent compliance frameworks. Asia-Pacific is the fastest-growing region, supported by rapid digital transformation, booming e-commerce markets, and increasing cybersecurity awareness in economies such as China, India, and Southeast Asian nations. Europe remains a strong contributor, underpinned by strict data protection regulations and widespread digital adoption.
Market Insights:
- The Digital Risk Management Market reached USD 7213.4 million and is projected to achieve USD 19312.6 million by 2032, registering a CAGR of 13.1% during the forecast period.
- Rising cyber-attacks, rapid regulatory changes, and growing reliance on cloud computing, IoT, and analytics are fueling demand for advanced risk management solutions.
- Enterprises are implementing third-party risk management, AI-powered threat detection, and automated incident response to enhance operational resilience.
- High complexity and cost of integration, along with limited skilled professionals, are key challenges impacting broader adoption across industries.
- North America holds 39% share, supported by advanced regulatory frameworks, strong technology adoption, and significant investments in unified risk platforms.
- Asia-Pacific holds 28% share and is the fastest-growing region, driven by digital transformation, e-commerce expansion, and national cybersecurity initiatives.
- Europe holds 23% share, reinforced by GDPR compliance requirements, high awareness of data security, and steady investment in governance solutions.
Market Drivers:
Rising Cybersecurity Threat Landscape Driving Adoption
The Digital Risk Management Market is witnessing strong growth due to the increasing volume and sophistication of cyber threats targeting organizations across industries. Businesses face heightened risks from ransomware, phishing, data breaches, and state-sponsored cyberattacks. It is essential for enterprises to adopt comprehensive risk management frameworks to safeguard sensitive data and maintain operational continuity. The integration of advanced threat detection, endpoint security, and real-time monitoring tools is becoming a strategic priority. Growing board-level attention to cybersecurity is reinforcing investments in digital risk management solutions.
- For instance, IBM's advanced threat detection and response capabilities are built on monitoring over 150 billion security events each day.
Evolving Regulatory Frameworks Influencing Market Growth
Tightening global regulations on data privacy, cybersecurity, and financial compliance are accelerating the need for robust digital risk management practices. The market benefits from initiatives such as GDPR in Europe, CCPA in the U.S., and various national cybersecurity mandates in Asia-Pacific. It compels organizations to implement structured compliance monitoring and reporting mechanisms to avoid legal penalties and reputational damage. This regulatory pressure is expanding the adoption of automated risk assessment and governance platforms. Businesses are increasingly aligning their compliance programs with digital risk strategies to meet evolving requirements efficiently.
Expansion of Cloud Computing and Connected Ecosystems
The widespread adoption of cloud computing, IoT devices, and digital platforms is amplifying the complexity of enterprise risk environments. The Digital Risk Management Market is responding with solutions that provide unified visibility across distributed infrastructures. It is crucial for enterprises to manage third-party and supply chain risks arising from interconnected systems. Scalable, cloud-based risk management platforms are enabling organizations to detect vulnerabilities and enforce consistent security policies. The growing dependency on connected technologies is elevating the role of digital risk management in strategic planning.
- For example, to manage third-party vulnerabilities, Bitsight’s risk management solution provides access to a network of over 40,000 vendor security profiles, enabling organizations to continuously monitor their digital supply chain.
Integration of Advanced Technologies to Enhance Risk Intelligence
Artificial intelligence, machine learning, and predictive analytics are transforming how organizations manage digital risks. The market is seeing increased adoption of tools that deliver proactive risk intelligence, automated threat detection, and incident response capabilities. It is enabling businesses to move from reactive measures to preventive strategies. Enhanced data analytics capabilities are providing actionable insights to prioritize critical risks and allocate resources effectively. This technological integration is strengthening the overall value proposition of digital risk management solutions.
Market Trends:
Growing Shift Toward Proactive and Predictive Risk Management Approaches
The Digital Risk Management Market is experiencing a clear transition from reactive defense measures to proactive and predictive risk mitigation strategies. Organizations are deploying advanced analytics and AI-powered models to identify potential threats before they impact operations. It enables enterprises to prioritize risks based on severity and probability, ensuring efficient resource allocation. Predictive capabilities are allowing decision-makers to anticipate vulnerabilities across IT networks, cloud platforms, and third-party environments. The emphasis on continuous monitoring and early warning systems is gaining traction, particularly in highly regulated sectors such as finance, healthcare, and critical infrastructure. This trend is reinforcing the importance of integrated platforms that combine risk assessment, compliance tracking, and incident response in a single ecosystem.
- For instance, CrowdStrike strengthens proactive defense by building its AI Security Services on threat intelligence from tracking more than 265 active adversary groups, which informs its platform's ability to protect customers.
Increased Emphasis on Integrated and Cloud-Native Risk Platforms
Demand is rising for unified, cloud-native risk management platforms that deliver comprehensive visibility across complex, distributed IT infrastructures. The market is responding with solutions that integrate governance, compliance, and security functions into centralized dashboards. It allows organizations to streamline risk reporting, enforce consistent policies, and reduce operational silos. The shift toward hybrid and multi-cloud architectures is further driving adoption of solutions that provide scalable protection and real-time threat intelligence. Vendors are focusing on user-centric designs and interoperability to support diverse enterprise environments. This development is strengthening the competitive differentiation of providers that can deliver agile, adaptable, and cost-effective digital risk management capabilities.
- For instance, OneTrust’s cloud platform includes compliance automation software that is integrated with more than 50 compliance frameworks, standards, and regulations.
Market Challenges Analysis:
High Complexity and Cost of Implementation Limiting Adoption
The Digital Risk Management Market faces challenges related to the high complexity and cost of deploying comprehensive solutions. Many organizations struggle to integrate digital risk management frameworks with existing IT infrastructures and legacy systems. It requires significant investment in technology, skilled personnel, and continuous updates to address evolving threats. Smaller enterprises often find these costs prohibitive, leading to slower adoption rates. The need for customization across different industries further increases implementation timelines and expenses. This complexity can hinder the ability of businesses to achieve rapid returns on investment.
Shortage of Skilled Professionals and Evolving Threat Landscape
A global shortage of cybersecurity and risk management professionals is impacting the market’s growth potential. The Digital Risk Management Market demands expertise in AI-driven analytics, regulatory compliance, and threat intelligence, yet the talent pool remains limited. It creates reliance on external service providers, which can raise costs and pose data security concerns. The constantly evolving nature of cyber threats requires organizations to adapt strategies quickly, often stretching internal resources. Limited awareness in some regions also slows the adoption of advanced solutions. This talent gap and dynamic threat environment remain critical challenges for sustained market expansion.
Market Opportunities:
Rising Demand for Cloud-Based and AI-Driven Risk Solutions
The Digital Risk Management Market presents strong growth potential through the adoption of cloud-based and AI-powered platforms. Enterprises are seeking scalable solutions that deliver real-time visibility, predictive analytics, and automated response capabilities. It enables organizations to manage risks across hybrid and multi-cloud environments with greater efficiency. The increasing reliance on digital ecosystems and remote operations is driving the need for integrated platforms that consolidate governance, compliance, and security functions. Vendors offering AI-enhanced tools that detect threats earlier and reduce manual intervention are positioned to capture a larger market share. Expanding capabilities in automation and advanced analytics will continue to open new revenue streams.
Expanding Opportunities in Emerging Economies and Regulated Sectors
Rapid digital transformation in emerging economies offers significant opportunities for market expansion. The Digital Risk Management Market can benefit from rising investments in cybersecurity infrastructure across Asia-Pacific, Latin America, and the Middle East. It creates demand for tailored solutions that address local compliance requirements and sector-specific risks. Highly regulated industries such as healthcare, banking, and critical infrastructure are increasingly prioritizing advanced risk management frameworks. Vendors that deliver industry-specific, compliance-ready solutions can gain a competitive edge. Growing awareness of digital risk in previously underserved markets further strengthens the long-term growth outlook.
Market Segmentation Analysis:
By Solution Type
The Digital Risk Management Market is segmented into risk and compliance management, threat intelligence and detection, third-party risk management, and incident response. Risk and compliance management holds a significant share due to increasing regulatory requirements across industries. Threat intelligence and detection is gaining traction as enterprises focus on identifying vulnerabilities before they escalate. Third-party risk management is expanding with the growing complexity of supply chains, while incident response solutions are critical for minimizing the impact of breaches.
- For instance, CrowdStrike's Falcon platform tracks 257 adversaries, using this intelligence to enhance detection and reduce false positives.
By Deployment Mode
The market is divided into on-premise and cloud-based solutions. Cloud-based deployment is witnessing strong demand due to scalability, cost efficiency, and the ability to provide real-time risk visibility across distributed environments. On-premise solutions maintain relevance in highly regulated sectors that require strict control over data. It is expected that hybrid approaches will see rising adoption as organizations balance security needs with operational flexibility.
- For instance, IBM's Hybrid Cloud Build Team has already completed over 75 engagements, helping partners create and migrate to open hybrid cloud environments, a process that typically takes between 5 and 20 weeks to develop a working prototype.
By Industry Vertical
The market covers BFSI, healthcare, IT and telecom, manufacturing, government, and others. BFSI leads the segment due to its high exposure to financial crimes and regulatory compliance obligations. Healthcare is increasing adoption to safeguard sensitive patient data and meet privacy mandates. IT and telecom benefit from digital risk solutions to protect extensive networks, while manufacturing focuses on securing connected production systems. Government agencies invest heavily in these solutions to protect national security and public data assets.
Segmentations:
By Solution Type
- Risk and Compliance Management
- Threat Intelligence and Detection
- Third-Party Risk Management
- Incident Response
By Deployment Mode
- On-Premise
- Cloud-Based
By Industry Vertical
- BFSI
- Healthcare
- IT and Telecom
- Manufacturing
- Government
- Others
By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
By Service Type
- Professional Services
- Managed Services
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Maintaining Market Leadership Through Advanced Adoption
North America accounted for 39% of the Digital Risk Management Market, supported by its mature cybersecurity infrastructure, strong regulatory enforcement, and high digital adoption rates. The presence of leading technology providers and early integration of AI-driven risk management tools contribute to its dominance. It benefits from a robust ecosystem of service providers, research institutions, and government initiatives aimed at strengthening cybersecurity resilience. Industries such as banking, healthcare, and government are investing heavily in unified risk platforms to address sophisticated threats. Ongoing innovations and substantial R&D investments continue to reinforce the region’s competitive position.
Asia-Pacific Emerging as the Fastest-Growing Region
Asia-Pacific held 28% of the Digital Risk Management Market, driven by large-scale digital transformation, expanding e-commerce markets, and increasing regulatory focus on data protection. The market in this region benefits from rising cybersecurity budgets across enterprises in China, India, Japan, and Southeast Asia. It is witnessing strong demand for cloud-native platforms that can scale with growing digital infrastructures. Government-led initiatives to secure national digital assets are encouraging adoption across both public and private sectors. Rising awareness of third-party and supply chain risks is further propelling the need for comprehensive digital risk strategies.
Europe Strengthening Position with Stringent Data Protection Laws
Europe accounted for 23% of the Digital Risk Management Market, supported by strict compliance requirements such as the General Data Protection Regulation (GDPR). The market in the region is shaped by high awareness of privacy and data security among enterprises and consumers. It benefits from steady investment in advanced governance and compliance solutions across sectors like finance, manufacturing, and healthcare. Regional companies are focusing on integrating digital risk management into enterprise-wide strategies to meet evolving regulatory demands. Strong collaboration between industry bodies and technology vendors is fostering innovation and improving market penetration.
Key Player Analysis:
- SAP
- Oracle Corporation
- IBM Corporation
- SAS Institute Inc.
- NAVEX Global
- ServiceNow
- RSA Security LLC
- Broadcom
- LogicManager
- Metricstream Inc.
Competitive Analysis:
The Digital Risk Management Market features a competitive landscape driven by innovation, strategic partnerships, and expanding service portfolios. Leading players focus on integrating AI, machine learning, and predictive analytics to enhance threat detection and compliance capabilities. It is characterized by a mix of established cybersecurity vendors, specialized risk management providers, and emerging technology firms. Companies are investing in cloud-native platforms, automation, and unified dashboards to meet growing demand for scalable and efficient solutions. Vendors compete on technology differentiation, regulatory expertise, and the ability to deliver tailored industry-specific offerings. The market is also witnessing increased mergers and acquisitions aimed at broadening geographic reach and strengthening product capabilities. Strong emphasis on customer-centric services and continuous product upgrades is enabling leading companies to maintain a competitive edge while attracting new clients in high-growth sectors such as BFSI, healthcare, and government.
Recent Developments:
- In August 2025, IBM partnered with the United States Tennis Association (USTA) to introduce new AI-powered fan experiences for the 2025 US Open, including a 'Match Chat' AI assistant.
- In May 2025, IBM launched new enterprise AI technologies, including the IBM LinuxONE 5 platform, and announced advancements to its watsonx platform and Turbonomic application resource management at its Think 2025 conference.
- In July 2025, Oracle announced a cloud services agreement valued at over $30 billion annually, reportedly with OpenAI, to provide substantial cloud infrastructure for the Stargate AI project.
- In May 2025, Broadcom launched its third-generation co-packaged optics (CPO) product line, designed to support the high-radix networks required for large-scale artificial intelligence deployments.
Market Concentration & Characteristics:
The Digital Risk Management Market demonstrates moderate to high concentration, with a limited number of established global vendors holding a significant share alongside a growing base of niche providers. It is characterized by strong technological innovation, frequent product enhancements, and the integration of advanced analytics to address evolving cyber threats and compliance demands. Vendors differentiate through domain expertise, scalable cloud-based solutions, and industry-specific offerings. The market reflects high entry barriers due to the need for advanced technical capabilities, regulatory knowledge, and substantial investment in R&D. Strategic alliances, mergers, and acquisitions are common, aimed at expanding geographic presence and strengthening service portfolios. Demand from sectors such as BFSI, healthcare, and government drives consistent growth, while competition remains intense in delivering real-time risk intelligence and comprehensive governance frameworks.
Report Coverage:
The research report offers an in-depth analysis based on Solution Type, Deployment Mode, Industry Vertical, Organization Size, Service Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Adoption of AI-driven risk assessment tools will expand, enabling faster detection and prioritization of emerging threats.
- Cloud-native digital risk management platforms will gain wider acceptance, supporting scalability and integration across hybrid environments.
- Predictive analytics will play a larger role in anticipating vulnerabilities and improving decision-making processes.
- Industry-specific solutions will increase in demand, particularly in regulated sectors such as healthcare, BFSI, and government.
- Partnerships between technology vendors and regulatory bodies will strengthen to align solutions with evolving compliance standards.
- The rise in third-party and supply chain risks will drive greater focus on vendor risk management capabilities.
- Integration of digital risk management with enterprise-wide governance frameworks will become standard practice for large organizations.
- Growth in remote and distributed workforces will accelerate the need for enhanced endpoint and identity risk controls.
- Emerging economies will offer new opportunities as digital transformation and cybersecurity awareness expand.
- Continuous innovation in automation and orchestration will streamline response times and reduce operational costs for enterprises.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Cybersecurity Threat Landscape
The increasing frequency and sophistication of cyber-attacks, including ransomware, phishing, and data breaches, are compelling organizations to invest in advanced digital risk management solutions to protect sensitive data and ensure business continuity.
Evolving Regulatory Frameworks
Stringent data privacy and cybersecurity regulations such as GDPR, CCPA, and national mandates in Asia-Pacific are driving organizations to adopt robust risk management frameworks to maintain compliance and avoid legal penalties.
Expansion of Cloud Computing and Connected Ecosystems
The proliferation of cloud computing, IoT devices, and interconnected digital platforms is increasing the complexity of enterprise risk environments, necessitating scalable, unified risk management solutions that provide real-time visibility and control.
Integration of Advanced Technologies
The adoption of artificial intelligence, machine learning, and predictive analytics is enabling organizations to shift from reactive to proactive risk management, allowing for earlier threat detection, automated response, and improved resource allocation.
Growth in Third-Party and Supply Chain Risks
As enterprises increasingly rely on third-party vendors and complex supply chains, the need for continuous monitoring and management of external risks is fueling demand for specialized digital risk management platforms.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Digital Risk Management, and what is its projected size in 2032?
Which Digital Risk Management market segment held the largest share in 2024
What are the primary factors fueling the growth of the Digital Risk Management market?
Which region commanded the largest share of the Digital Risk Management market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution Type
- 1.2.1 Risk and Compliance Management
- 1.2.2 Threat Intelligence and Detection
- 1.2.3 Third-Party Risk Management
- 1.2.4 Incident Response
- 1.3 By Deployment Mode
- 1.3.1 On-Premise
- 1.3.2 Cloud-Based
- 1.4 By Industry Vertical
- 1.4.1 BFSI
- 1.4.2 Healthcare
- 1.4.3 IT and Telecom
- 1.4.4 Manufacturing
- 1.4.5 Government
- 1.4.6 Others
- 1.5 By Organization Size
- 1.5.1 Large Enterprises
- 1.5.2 Small and Medium Enterprises (SMEs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7213.4 million → 2032: USD 19312.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Digital Risk Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Digital Risk Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Digital Risk Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Digital Risk Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Digital Risk Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Digital Risk Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Digital Risk Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Digital Risk Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7213.4 million → 2032: USD 19312.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Digital Risk Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Risk and Compliance Management
- 12.3.7.2 Threat Intelligence and Detection
- 12.3.7.3 Third-Party Risk Management
- 12.3.7.4 Incident Response
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-Premise
- 12.4.7.2 Cloud-Based
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 BFSI
- 12.5.7.2 Healthcare
- 12.5.7.3 IT and Telecom
- 12.5.7.4 Manufacturing
- 12.5.7.5 Government
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Large Enterprises
- 12.6.7.2 Small and Medium Enterprises (SMEs)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Digital Risk Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Digital Risk Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Digital Risk Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Digital Risk Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SAP
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oracle Corporation
- 18.4 IBM Corporation
- 18.5 SAS Institute Inc.
- 18.6 NAVEX Global
- 18.7 ServiceNow
- 18.8 RSA Security LLC
- 18.9 Broadcom
- 18.10 LogicManager
- 18.11 Metricstream Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

