
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Digital Intraoral Sensor and Consumable Market Size 2023 | USD 1,010.79 million |
| Digital Intraoral Sensor and Consumable Market, CAGR | 5.24% |
| Digital Intraoral Sensor and Consumable Market Size 2032 | USD 1,644.05 million |
Market Overview
The digital intraoral sensor and consumable market is poised for notable growth, with its value projected to surge from USD 1,010.79 million in 2023 to USD 1,644.05 million by 2032, reflecting a substantial compound annual growth rate of 5.24%. The global dental diagnostics landscape is undergoing a transformative shift, marked by the rising significance of digital intraoral sensors and consumables.
The escalating demand for digital intraoral sensors and consumables can be attributed to a paradigm shift from traditional film-based radiography to digital imaging systems in dentistry. Dental practitioners are increasingly recognizing the diagnostic precision and efficiency afforded by digital intraoral sensors, contributing significantly to the market's sustained growth.
The digital intraoral sensor segment, a cornerstone of this market, includes devices that capture high-resolution intraoral images, facilitating detailed examination of the teeth and surrounding structures. These sensors enable real-time imaging, allowing for immediate chairside evaluation and enhancing overall diagnostic capabilities. As technological advancements continue to refine these sensors, practitioners benefit from improved imaging accuracy, streamlined workflows, and enhanced patient experiences.
The rapid evolution of digital intraoral sensors and consumables is driven by several key dynamics within the dental industry. The escalating demand for efficient and patient-friendly diagnostic solutions is a primary driver, leading dental practitioners to adopt digital intraoral sensors to expedite the diagnostic process and improve treatment planning accuracy. Research and development initiatives are surging, fostering technological innovations in digital intraoral sensors, including increased sensor sensitivity, enhanced image resolution, and the integration of artificial intelligence for image analysis.
The adoption of digital intraoral sensors and consumables varies across regions, influenced by factors such as healthcare infrastructure, technological awareness, and regulatory landscapes. North America and Europe are key players, driven by well-established dental practices and robust research and development activities. The Asia-Pacific region is emerging as a focal point for market growth, propelled by increasing healthcare expenditures and rising awareness of advanced dental technologies. Countries like China and India, with expanding middle-class populations and a rising focus on oral health, present lucrative opportunities for market players. Latin America and the Middle East and Africa regions are also experiencing a gradual uptake of digital dental imaging technologies, influenced by efforts to improve healthcare infrastructure, enhance dental education, and increase awareness among dental practitioners about the benefits of digital intraoral sensors. The integration of artificial intelligence and machine learning into digital intraoral sensors holds the potential to revolutionize dental diagnostics, assisting in automated image analysis and facilitating more precise treatment planning.
Market Drivers
Rising Demand for Advanced Dental Imaging:
Traditional film-based X-rays are gradually making way for the adoption of digital intraoral sensors, marking a significant shift in the landscape of dental diagnostics. This transition is propelled by the growing recognition of the superior benefits offered by digital imaging technologies. Digital intraoral sensors stand out as a key driver due to their ability to provide superior image quality, reduce radiation exposure for patients, and significantly enhance diagnostic capabilities for dentists. The escalating demand for advanced dental imaging techniques represents a pivotal force steering the market toward a future where digital sensors are at the forefront of diagnostic procedures.
Increased Focus on Oral Health Awareness
A notable driver influencing the digital intraoral sensor and consumable market is the heightened focus on oral health awareness among the general public. Patients are becoming increasingly proactive in seeking dental care, emphasizing the importance of preventive measures and timely diagnosis. For instance, World Oral Health Day is celebrated every year on March 20th to raise awareness about the importance of good oral health. This surge in awareness contributes directly to a higher demand for diagnostic procedures utilizing digital intraoral sensors. As oral health gains prominence in public consciousness, the market experiences a surge in patients seeking more sophisticated and patient-friendly diagnostic solutions, driving the widespread adoption of digital intraoral sensors.
Technological Advancements
Continuous advancements in sensor technology form a cornerstone for the robust growth of the digital intraoral sensor and consumable market. These advancements encompass various facets that collectively contribute to the efficiency and effectiveness of dental diagnostics. For instance, recent advances include optical coherence tomography, an occlusal stabilization splint with a stress-sensor system for bruxism, a periodontal probe based on a fluorescent fiber position sensor, and a dental implantable temperature sensor for real-time diagnosis of infectious periodontal disease. Improved sensor design, featuring smaller, lighter, and more ergonomic sensors, enhances patient comfort during procedures. Furthermore, the integration of wireless connectivity in sensors streamlines workflows in dental practices and facilitates real-time image sharing with specialists. The evolution also includes enhanced image resolution, allowing dentists to detect dental issues with greater accuracy. The seamless integration of digital intraoral sensors with dental practice management software and CAD/CAM systems further augments the efficiency of storing, analyzing, and manipulating digital dental images, thereby enhancing overall diagnostics and treatment planning.
Growing Geriatric Population
The demographic shift toward an aging population plays a crucial role in driving the market growth of digital intraoral sensors and consumables. As individuals age, they become more susceptible to dental problems, necessitating regular dental checkups and diagnostic procedures. For instance, the World Health Organization reports that by 2050, over 20% of the world’s population will be 60 years of age or older. This demographic segment’s unique dental needs contribute significantly to the sustained growth of the market. Dental conditions associated with aging include dry mouth (xerostomia), root and coronal caries, and periodontitis. Patients may show increased sensitivity to drugs used in dentistry, including local anesthetics and analgesics. The market responds to the evolving requirements of the geriatric population, offering advanced diagnostic solutions tailored to their specific oral health challenges. 10. The intersection of an aging demographic and dental health requirements establishes a compelling driver for the market’s expansion.
Cost-Effectiveness in the Long Run
While the initial investment in digital intraoral sensors may appear higher compared to traditional film-based X-rays, the undeniable cost-effectiveness of digital sensors becomes apparent over the long term. The elimination of film processing costs, coupled with the increased durability of digital sensors, translates into improved workflow efficiency for dental practices. This, in turn, leads to substantial cost savings. The long-term financial viability of digital intraoral sensors contributes significantly to their widespread adoption, making them an economically sound investment for dental practices aiming for enhanced diagnostic capabilities and streamlined workflows. As the market continues to evolve, the cost-effectiveness of digital intraoral sensors becomes a compelling factor influencing the decision-making process of dental practitioners worldwide.
Market Trends
Artificial Intelligence (AI) Integration
The integration of digital intraoral sensors with AI-powered software marks a transformative leap in dental diagnostics. For instance, Diagnocat, the first AI dental software tool offering both 2D and 3D data visualization of dental x-ray images, has significantly reduced the error margin in decision-making, leading to a novel patient and clinical practice experience. AI applications bring an unprecedented level of sophistication to image analysis, allowing these sensors not only to capture high-resolution images but also to autonomously identify potential dental problems. This includes the ability to suggest accurate diagnoses and recommend tailored treatment plans. The incorporation of AI in digital intraoral sensors significantly enhances diagnostic accuracy, streamlines workflows for dentists, and contributes to more precise and efficient patient care.
Teledentistry and Cloud-Based Solutions
With the advent of teledentistry, the role of digital intraoral sensors has expanded beyond traditional dental practices. These sensors are now equipped with cloud-based storage capabilities, enabling dentists to conduct remote consultations and access patient images from anywhere in the world. This shift aligns with broader trends in healthcare digitization, providing unparalleled flexibility in dental diagnostics. The ability to remotely acquire and analyze images enhances accessibility for both dental professionals and patients, fostering a new era of virtual dental care.
Focus on patient experience
Manufacturers are placing a heightened emphasis on patient-centric approaches to dental diagnostics. In addition to clinical efficiency, the development of flexible and disposable sensor covers minimizes patient discomfort during procedures. Single-use sensors not only enhance hygiene practices but also contribute to an overall positive patient experience. This trend underscores a holistic approach to dental care, recognizing the importance of patient comfort alongside clinical precision in the adoption of digital intraoral sensors. Based on 67 individual patient interviews, researchers explored patient perspectives about the impact of dental diagnostic errors. Participants identified several categories of contributing factors, including clinician issues (e.g., poor communication), patient issues (e.g., lack of self-advocacy), and system factors (e.g., insurance challenges, workload).
Ergonomic Design and User-Friendliness
Continuous advancements in sensor design prioritize ergonomic considerations, aiming to reduce hand fatigue for dental professionals during prolonged use. The focus on ergonomic design not only enhances the efficiency of dental procedures but also improves the well-being of practitioners. Simultaneously, intuitive software interfaces are being developed to ensure that digital intraoral sensors are user-friendly for dentists with varying levels of technical expertise. This dual focus on usability and design is pivotal in promoting widespread adoption and maximizing the benefits of digital technologies in dental practices.
Material Advancements
Sensor manufacturers are exploring innovative materials to enhance the safety and comfort of patients. The use of biocompatible and antimicrobial materials in digital intraoral sensors addresses concerns related to infection control in dental settings. These material advancements reflect a commitment to not only clinical efficacy but also the overall well-being of patients, positioning digital intraoral sensors as technologically advanced yet patient-friendly tools in modern dental practices.
Focus on Sustainability
Environmental considerations are gaining prominence in the development of digital intraoral sensors. Initiatives such as the development of biodegradable sensor covers and sensor recycling programs exemplify a commitment to minimizing the environmental impact of sensor usage. This sustainability focus aligns with broader trends in healthcare toward eco-friendly solutions, reflecting a conscientious approach to technology development and usage in the dental industry.
Expansion into Emerging Markets
Developing regions with a growing dental infrastructure present a unique opportunity for manufacturers to expand their market reach. The demand for affordable and user-friendly digital intraoral sensors in these emerging markets is driving the development of cost-effective options tailored to the specific needs and constraints of these regions. This expansion reflects a commitment to democratizing access to advanced dental diagnostics and improving oral healthcare on a global scale, aligning with the broader goals of accessible and equitable healthcare delivery.
Market Restraints and Challenges
High Initial Costs
The adoption of digital intraoral sensors and associated software entails a significant initial investment, posing a potential barrier for dental practices, especially smaller establishments or those in developing regions. The financial commitment required can be a restraint, limiting the widespread adoption of advanced dental imaging technologies. Manufacturers and industry stakeholders are actively addressing this challenge by exploring flexible financing options and emphasizing the long-term cost-effectiveness of digital solutions. However, the upfront expenses remain a noteworthy consideration for dental practices considering the transition from traditional X-ray methods.
Reimbursement Challenges
One of the hurdles in the broader adoption of digital intraoral sensors and consumables lies in reimbursement challenges. Existing reimbursement policies from insurance companies might not fully cover the costs associated with these advanced technologies, potentially discouraging dental practices from investing in them. Collaborative efforts between industry players and policymakers are essential to address reimbursement gaps and ensure that dental practitioners receive fair compensation for adopting state-of-the-art diagnostic tools. Overcoming these challenges is crucial to promoting the equitable integration of digital intraoral sensors across diverse dental practices.
Technical Expertise and Training
The effective utilization of digital intraoral sensors requires a certain level of technical expertise and training for dental professionals. Without adequate training, practitioners may face challenges in operating these advanced tools and interpreting dental images accurately. To overcome this obstacle, manufacturers and educational institutions are working in tandem to develop comprehensive training programs. These programs aim to equip dental professionals with the necessary skills to seamlessly integrate digital intraoral sensors into their workflows, ensuring optimal usage and enhancing overall workflow efficiency.
Data Security and Privacy Concerns
The integration of digital technology in dental practices raises legitimate concerns regarding data security and patient privacy. Dental practices must implement robust cybersecurity measures to safeguard patient data, ensuring compliance with privacy regulations. Industry stakeholders are actively involved in developing and promoting secure data storage protocols, encryption methods, and cybersecurity best practices. Addressing these concerns is paramount to fostering trust among dental practitioners and patients alike, establishing digital intraoral sensors as reliable and secure diagnostic tools in modern dentistry.
Integration Challenges
Integrating digital intraoral sensors with existing dental practice management software can be a complex and time-consuming process, posing a challenge for some practices. The transition from traditional X-ray methods to digital technologies requires careful planning and technical expertise. Industry efforts are directed towards developing seamless integration solutions and providing comprehensive support to dental practices during the transition phase. Simplifying the integration process is essential for encouraging more dental practitioners to embrace the benefits of digital intraoral sensors, thereby advancing the overall standard of dental diagnostics.
Limited Internet Connectivity in Remote Areas
The cloud-based features and teledentistry applications associated with digital intraoral sensors may face limitations in remote areas with limited internet connectivity. This poses a challenge to the widespread implementation of these technologies in certain regions. Efforts to improve internet infrastructure and develop offline functionalities for digital intraoral sensors are underway to address this challenge. Bridging the connectivity gap is crucial to ensuring that even remote and underserved areas can benefit from the diagnostic capabilities offered by digital intraoral sensors, contributing to improved oral healthcare on a global scale.
Acceptance by Older Dentists
Resistance to change among some older dentists accustomed to traditional X-ray methods presents a unique challenge to the adoption of digital intraoral sensors. Overcoming this resistance requires targeted training programs and comprehensive demonstrations showcasing the benefits of digital technologies. Industry initiatives aim to educate older dentists about the advantages of digital intraoral sensors, emphasizing improved diagnostic precision, enhanced workflow efficiency, and patient-centric care. Fostering a culture of continuous learning and adaptation is key to ensuring that dentists of all generations can confidently embrace the advancements in dental diagnostics facilitated by digital intraoral sensors.
Segmentation Analysis
By Product type:
The cornerstone of this market, dental digital intraoral sensors, represents a pivotal category in advanced dental imaging technologies. These sensors capture high-resolution intraoral images, offering detailed examinations of teeth and surrounding structures. With real-time imaging capabilities, they facilitate immediate chairside evaluations, contributing to enhanced diagnostic precision and overall efficiency. This category includes indispensable components used in conjunction with imaging devices, such as protective barriers, positioning devices, and calibration tools. Dental image plate scanners complement the intraoral phosphor storage plates by facilitating the conversion of captured X-ray images into digital formats. These scanners play a vital role in the digitization of dental radiography, contributing to the overall transition from traditional to digital imaging systems. Continuous advancements in scanner technology aim to improve efficiency, speed, and image quality, further driving their adoption across dental practices. Intraoral cameras represent a valuable addition to the product portfolio, allowing for visual documentation of oral conditions.
By End-User:
Dental laboratories constitute a significant end-user segment, leveraging digital intraoral sensors and associated products for various applications, including prosthetics, restoration, and laboratory diagnostics. The precision offered by digital imaging technologies enhances the quality and accuracy of dental laboratory work, driving their adoption. Digital intraoral sensors find extensive use in dental hospitals for a wide range of diagnostic and treatment purposes. The immediate imaging capabilities and enhanced diagnostic precision contribute to efficient patient care and treatment planning. The demand for these technologies in dental hospitals is fueled by the growing emphasis on advanced dental care services. Dental clinics, catering to a diverse range of patients, benefit significantly from the adoption of digital intraoral sensors and consumables. The efficiency, reduced radiation exposure, and enhanced diagnostic capabilities contribute to streamlined workflows in busy clinic settings. Digital imaging technologies align with the commitment of dental clinics to provide comprehensive and patient-friendly care.
Segments:
By Product type:
- Dental Digital Intraoral Sensors
- Consumables
- Intraoral Phosphor Storage Plates
- Dental Image Plate Scanners
- Intraoral Cameras
By End-Users:
- Dental Laboratories
- Dental Hospitals
- Dental Clinics
- Others
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Key Players
- Dentsply Sirona
- Carestream Dental
- Planmeca
- Vatech
- DEXIS (Kavo Kerr)
- Schick (Meditron)
- Acteon Group
- Gendex (KaVo Kerr)
- FONA Dental
- Air Techniques
- Midmark Corporation
- Danaher Corporation
- LED Medical Diagnostics (Vista Dental)
- XDR Radiology
- Owandy Radiology
Recent Developments
In November 2023, DEXIS, a leading provider of cutting-edge dental imaging technology, including sensors, intraoral scanning, and CBCT systems, made a significant announcement regarding its participation at the prestigious Greater New York Dental Meeting (GNYDM). During this notable event, DEXIS showcased its latest innovations, the DEXIS OP 3D LX and the DEXassist Solution. Attendees had the unique opportunity to engage in hands-on testing of these anticipated new products, further solidifying DEXIS's commitment to advancing dental diagnostics and imaging technologies.
In October 2023 witnessed key product releases from PreXion, Inc., a prominent player in the industry. PreXion introduced two noteworthy additions to its extensive dental imaging product line. First, the Evolve Sensor intraoral dental digital imaging sensor, designed to deliver high-quality intraoral images. Second, the 3-in-1 PreXion3D Evolve CBCT, PAN, and CEPH emerged as a comprehensive dental imaging solution encapsulated within a single device. These product releases underscore PreXion's dedication to providing state-of-the-art imaging solutions, addressing the evolving needs of dental professionals and contributing to the ongoing transformation of dental diagnostic practices.
Regional Analysis
North America: The North American region, comprising the United States and Canada, holds a significant share of the global digital intraoral sensor and consumable market. This region is characterized by a well-established dental healthcare infrastructure, advanced technological adoption, and a strong emphasis on cutting-edge dental practices. The market in North America is driven by factors such as the increasing demand for digital imaging solutions, the presence of major dental equipment manufacturers, and supportive reimbursement policies. According to recent market reports, North America accounts for approximately 38% of the global digital intraoral sensor and consumable market.
Europe: Europe is a key player in the digital intraoral sensor and consumable market, with countries like Germany, France, the United Kingdom, and Italy leading the way. The region's focus on dental health innovation, favorable reimbursement policies, and the presence of renowned dental research institutions have contributed to its substantial market share. The growing adoption of digital imaging technologies in dental practices and the increasing awareness about the benefits of early detection have further fueled the demand for digital intraoral sensors and consumables in Europe. The region holds a market share of around 28%.
Asia-Pacific: The Asia-Pacific region, encompassing countries like China, Japan, India, and South Korea, is witnessing a surge in the demand for digital intraoral sensors and consumables. Factors such as the rapidly growing population, increasing disposable income, and the rising awareness about dental health have propelled the market growth in this region. Additionally, the expanding medical tourism industry and the improving dental healthcare infrastructure in several Asian countries have created lucrative opportunities for market players. The Asia-Pacific region currently accounts for 20% of the global digital intraoral sensor and consumable market.
Latin America: The Latin American region, including countries such as Brazil, Mexico, and Argentina, represents a promising market for digital intraoral sensors and consumables. The increasing focus on dental health, the growing adoption of digital imaging technologies, and the region's efforts to improve healthcare access and quality have driven the demand for these products. However, challenges such as limited healthcare budgets and uneven distribution of resources across the region have hindered its full potential. Latin America currently holds a market share of 8%.
Middle East and Africa: The Middle East and Africa region is considered an emerging market for digital intraoral sensors and consumables. Countries in the Gulf Cooperation Council (GCC) have witnessed significant investments in dental healthcare infrastructure, contributing to the growth of the digital intraoral sensor and consumable market. However, the region faces challenges such as limited access to advanced dental facilities and the high cost of dental equipment, particularly in some African countries. The Middle East and Africa region currently accounts for 6% of the global digital intraoral sensor and consumable market.
Future Outlook
- Anticipated Technological Advancements: The digital intraoral sensor and consumable market are poised to witness continuous technological innovations, enhancing imaging precision and diagnostic capabilities.
- Integration of Artificial Intelligence: The integration of artificial intelligence (AI) is expected to revolutionize dental diagnostics, enabling automated image analysis for more precise treatment planning.
- Growing Embrace of Teledentistry: The market is likely to experience increased adoption of teledentistry, with digital intraoral sensors facilitating remote consultations and diagnostics.
- Expansion into Emerging Markets: Manufacturers are exploring opportunities in emerging markets, developing cost-effective solutions tailored to the specific needs of regions with growing dental infrastructure.
- Sustainability Initiatives: Environmental considerations will drive the development of sustainable practices, including biodegradable sensor covers and sensor recycling programs.
- Enhanced Ergonomics and User-Friendliness: Ongoing improvements in sensor design will focus on reducing hand fatigue for dental professionals and providing intuitive software interfaces for ease of use.
- Continued Focus on Patient Comfort: Manufacturers will prioritize patient comfort with the development of flexible and disposable sensor covers, contributing to a positive patient experience.
- Increased Connectivity: Digital intraoral sensors are expected to become more integrated with dental practice management software and CAD/CAM systems, enhancing efficiency in storage, analysis, and manipulation of digital dental images.
- Addressing Initial Cost Barriers: Efforts to overcome the initial investment challenges will include flexible financing options, emphasizing the long-term cost-effectiveness of digital solutions.
- Evolving Regulatory Landscape: The market's future will be influenced by regulatory developments, with ongoing efforts to establish standards for data security and privacy in digital dental imaging technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the digital intraoral sensor and consumable market?
How are technological advancements influencing the market dynamics?
What challenges does the market face, especially for smaller dental practices?
What role does patient comfort and safety play in the adoption of digital intraoral sensors?
How is the market addressing data security and privacy concerns associated with digital technology?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Digital Intraoral Sensor and Consumable Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Digital Intraoral Sensor and Consumable Market Snapshot
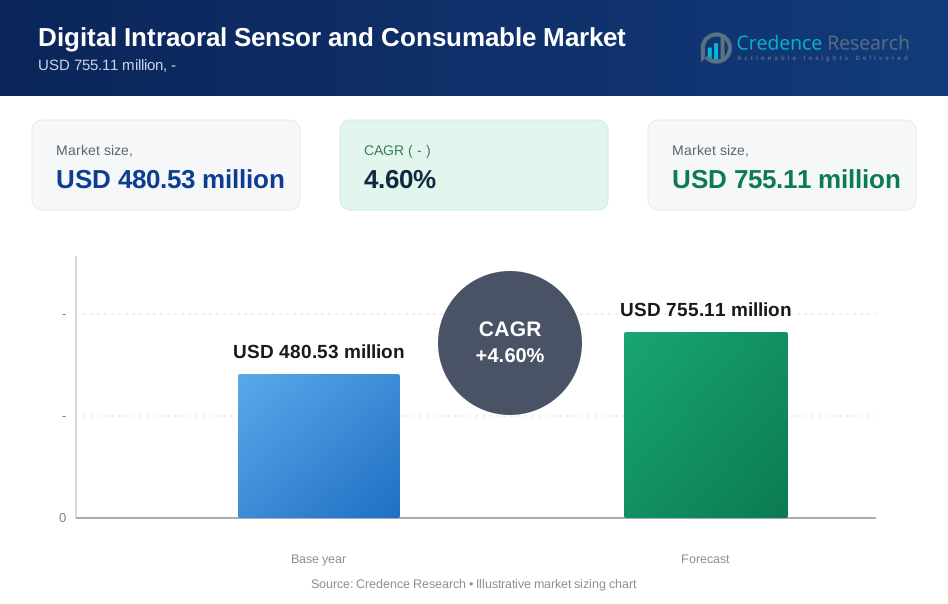
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 480.53 million → forecast year: USD 755.11 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Digital Intraoral Sensor and Consumable Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Digital Intraoral Sensor and Consumable Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Digital Intraoral Sensor and Consumable Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Digital Intraoral Sensor and Consumable Market Drivers
- 3.3 Digital Intraoral Sensor and Consumable Market Restraints & Challenges
- 3.4 Digital Intraoral Sensor and Consumable Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Digital Intraoral Sensor and Consumable Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Digital Intraoral Sensor and Consumable Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Digital Intraoral Sensor and Consumable category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Digital Intraoral Sensor and Consumable Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Digital Intraoral Sensor and Consumable Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Digital Intraoral Sensor and Consumable market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Digital Intraoral Sensor and Consumable Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Digital Intraoral Sensor and Consumable Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Digital Intraoral Sensor and Consumable Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Digital Intraoral Sensor and Consumable (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Digital Intraoral Sensor and Consumable Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Digital Intraoral Sensor and Consumable Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Digital Intraoral Sensor and Consumable Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Digital Intraoral Sensor and Consumable Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Digital Intraoral Sensor and Consumable Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Digital Intraoral Sensor and Consumable Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Digital Intraoral Sensor and Consumable Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Digital Intraoral Sensor and Consumable Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Digital Intraoral Sensor and Consumable Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
