
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Drilling Tools Market Size 2023 | USD 7023.15 Million |
| Drilling Tools Market, CAGR | 5.11% |
| Drilling Tools Market Size 2032 | USD 10998.37 Million |
Market Overview:
Global Drilling Tools Market size was valued at USD 7023.15 million in 2023 and is anticipated to reach USD 10998.37 million by 2032, at a CAGR of 5.11% during the forecast period (2023-2032).
Several factors are propelling the growth of the drilling tools market. The surge in global energy consumption has intensified exploration and production activities, necessitating advanced drilling tools capable of operating in challenging environments. Technological innovations, including the integration of artificial intelligence and automation, have improved drilling precision and efficiency, reducing downtime and operational expenses. Additionally, the resurgence of offshore drilling projects, particularly in deepwater regions, has increased the demand for specialized drilling equipment. However, the market faces challenges such as high maintenance costs and the need for continuous technological upgrades to meet evolving industry standards
Regionally, North America holds a significant share of the drilling tools market, driven by extensive shale gas production and supportive energy policies in the United States. The Asia-Pacific region is experiencing rapid growth, with countries like China and India investing heavily in infrastructure and energy projects, leading to increased drilling activities. In the Middle East and Africa, abundant oil and gas reserves continue to attract investments in drilling operations, further boosting the demand for advanced drilling tools. Europe and Latin America also contribute to market growth, albeit at a steadier pace, with ongoing exploration and production activities in regions like the North Sea and offshore Brazil. Growing regional partnerships and government-backed energy initiatives are further accelerating regional market development.
Market Insights:
- The global drilling tools market is valued at USD 7,023.15 million in 2023 and is projected to reach USD 10,998.37 million by 2032, growing at a CAGR of 5.11% during the forecast period.
- Rising global energy demand, driven by industrialization and urbanization, is fueling the growth of exploration and production activities, increasing the need for advanced drilling tools.
- Technological advancements, including AI, automation, and real-time data analytics, are improving drilling precision, reducing downtime, and lowering operational expenses.
- Offshore drilling, particularly in deepwater and ultra-deepwater regions, is driving demand for specialized drilling equipment as conventional oil fields mature.
- The exploration of unconventional resources such as shale gas and tight oil is further increasing the need for high-performance drilling tools designed for complex geological conditions.
- Environmental regulations and sustainability concerns are leading to the development of more efficient, low-impact drilling technologies to comply with safety and environmental standards.
- Regionally, North America dominates the market, driven by extensive shale gas production and energy policies in the United States, with rapid growth observed in the Asia-Pacific and Middle East regions.
Market Drivers:
Rising Global Energy Demand
The escalating global energy demand remains a pivotal force driving the growth of the drilling tools market. As industrialization and urbanization accelerate across developing regions, the need for oil and gas continues to rise, prompting increased exploration and production activities. Emerging economies are significantly contributing to this demand spike, as they experience rapid infrastructure development and higher energy consumption across sectors such as transportation, manufacturing, and power generation. To meet this demand, oil and gas companies are ramping up drilling operations, thereby driving the adoption of advanced and efficient drilling tools.
Technological Advancements in Drilling Systems
Technological innovation has become a critical enabler of market growth, enhancing the performance, reliability, and cost-effectiveness of drilling tools. The integration of digital technologies such as automation, artificial intelligence, and real-time data analytics into drilling operations is transforming traditional methods and improving operational efficiency. These advancements are helping companies reduce non-productive time, optimize drilling performance, and enhance safety in harsh environments. Additionally, the development of high-performance drilling bits, downhole tools, and rotary steerable systems has expanded the market potential by enabling deeper, more accurate, and cost-efficient drilling.
Increased Offshore and Unconventional Resource Exploration
A renewed focus on offshore and unconventional hydrocarbon reserves is fueling the demand for specialized drilling tools. Deepwater and ultra-deepwater projects are gaining traction as conventional oil fields mature and their output declines. Countries with substantial offshore reserves, such as Brazil, Norway, and those in the Gulf of Mexico, are investing heavily in new exploration initiatives, thereby stimulating demand for robust and technologically advanced drilling equipment. For instance, in 2023, Oceaneering International, Inc. secured a five-year contract worth $75 million from Petrobras for the operation of drill pipe riser systems in Brazil, reflecting the growing investment in deepwater and ultra-deepwater drilling infrastructure. Similarly, the exploration of shale gas, tight oil, and other unconventional resources in regions like North America requires horizontal drilling and hydraulic fracturing technologies, further boosting the need for customized drilling tools designed to perform in complex geological conditions.
Focus on Safety, Efficiency, and Environmental Compliance
Increasing regulatory scrutiny and heightened focus on environmental sustainability are influencing the adoption of high-quality drilling tools. Governments and international bodies are implementing stringent safety and environmental regulations to mitigate the risks associated with drilling operations. In response, oilfield service providers are developing tools that not only enhance operational efficiency but also comply with environmental standards. For example, R&D Solutions offers real-time data monitoring systems that detect pressure fluctuations, monitor gas levels, and identify mechanical issues, ensuring both safety and regulatory compliance in drilling operations. Innovations aimed at minimizing waste, reducing emissions, and improving wellbore stability are being prioritized to meet regulatory benchmarks and reduce the environmental footprint. As sustainability becomes a central theme in the energy sector, the demand for efficient, low-impact, and technologically advanced drilling tools is expected to rise steadily.
Market Trends:
Adoption of Digital Twin Technology
A prominent trend in the global drilling tools market is the growing adoption of digital twin technology to enhance drilling accuracy and reduce operational risks. Digital twins virtual replicas of physical systems are increasingly being integrated into drilling operations to simulate and optimize performance in real time. For example, Shell uses digital twins to optimize offshore platform operations, employing advanced analytics and machine learning for predictive maintenance and operational efficiency. This approach allows operators to predict equipment behavior, identify potential faults before they occur, and streamline maintenance schedules. As a result, companies are improving operational uptime and significantly lowering costs. The demand for digital twin technology is growing in offshore drilling, where operational environments are complex and downtime is particularly costly.
Increased Investment in Remote and Automated Drilling Operations
Another significant trend is the shift toward remote and automated drilling operations. The global industry is witnessing an increase in investment in autonomous drilling rigs and remote operations centers, driven by the need to enhance productivity and reduce human error. Remote drilling systems are especially valuable in inaccessible or hazardous environments, such as Arctic regions and ultra-deepwater reserves. For instance, Nabors, for instance, has collaborated with ProDirectional to deliver automated steering technologies, such as the SmartNAV® directional guidance system and SmartSLIDE® automated slide drilling, enabling remote steering services and improving operational visibility and worker safety. This transition toward automation aligns with the broader movement toward digital oilfields and is transforming how drilling tools are utilized and maintained.
Sustainability-Driven Tool Innovation
Sustainability is becoming a core focus in the design and application of drilling tools. With mounting pressure from governments, investors, and stakeholders to reduce environmental impact, oilfield service providers are developing tools that improve fuel efficiency, minimize waste, and enable more precise drilling. For instance, the use of water-based and biodegradable drilling fluids is gaining traction as an eco-friendly alternative to conventional fluids. Additionally, companies are focusing on the recyclability of drill bits and tool components to align with circular economy principles. This trend reflects a broader industry shift toward environmentally responsible operations, especially in regions with strict emissions regulations such as Europe and Canada.
Rise of Integrated Drilling Services
The demand for integrated drilling services is gaining momentum as oil and gas operators seek comprehensive solutions to improve project efficiency and coordination. Instead of sourcing tools and services from multiple vendors, companies are increasingly opting for bundled offerings that include drilling tools, engineering services, data analytics, and field support. This approach not only reduces procurement complexities but also enhances operational continuity and real-time decision-making. Major players such as Schlumberger, Halliburton, and Weatherford are expanding their integrated services portfolios to cater to this demand, aiming to provide end-to-end solutions that improve performance across the drilling lifecycle.
Market Challenges Analysis:
High Capital and Operational Costs
One of the primary restraints facing the global drilling tools market is the high capital investment required for advanced equipment and technologies. Procuring, deploying, and maintaining drilling tools especially those used in offshore or high-pressure environments demands substantial financial resources. Additionally, operational expenses such as workforce training, regular maintenance, and safety compliance increase the overall cost burden on companies. Smaller and mid-sized operators often face difficulties in adopting state-of-the-art tools, limiting their participation in large-scale exploration projects and thereby restraining market growth.
Volatility in Oil and Gas Prices
Fluctuating crude oil and natural gas prices continue to pose a significant challenge to the drilling tools market. Market uncertainty often leads to delays or cancellations of exploration and production activities, particularly in capital-intensive offshore ventures. During periods of low prices, operators reduce drilling expenditures to preserve margins, which directly impacts the demand for new drilling tools. This cyclical nature of the oil and gas industry introduces instability into the market, affecting both short-term revenues and long-term investment planning for drilling tool manufacturers and service providers.
Environmental Regulations and Public Scrutiny
Stringent environmental regulations and growing public scrutiny over drilling operations present another key challenge. Governments across the globe are enforcing strict policies related to emissions, water usage, and waste management in response to climate change and ecological concerns. Complying with these regulations requires the continuous development of environmentally sustainable tools and processes, which can be both time-consuming and costly. For instance, Shell’s exit from Arctic drilling was driven by a combination of stringent regulatory requirements, ongoing legal challenges from environmental groups and indigenous communities, and widespread public opposition, all of which created substantial operational risks and financial burdens for the company. Furthermore, resistance from local communities and environmental groups often results in project delays or legal complications, adding to operational risks and market uncertainties.
Market Opportunities:
The global drilling tools market presents substantial growth opportunities driven by the increasing focus on untapped and emerging energy reserves. As mature oil fields reach production decline, exploration is shifting toward frontier regions such as the Arctic, deepwater basins, and ultra-deep offshore reserves. These environments demand highly specialized and robust drilling tools capable of withstanding extreme conditions, opening new avenues for innovation and product development. Additionally, advancements in directional and horizontal drilling techniques are expanding the scope of unconventional resource extraction, particularly in shale-rich regions across North America, China, and Argentina. Companies investing in advanced tool designs and material science to enhance durability, precision, and efficiency are well-positioned to capitalize on these complex exploration activities.
Another promising opportunity lies in the global transition toward energy security and diversification. National governments are prioritizing domestic oil and gas production to reduce dependency on imports, which is driving upstream investment and boosting demand for drilling equipment. Furthermore, the expansion of digital oilfields and data-driven drilling operations presents a strong growth avenue for companies offering smart, connected tools integrated with real-time monitoring and predictive maintenance capabilities. These solutions not only optimize performance but also help operators comply with evolving environmental and safety regulations. As energy demand continues to rise alongside global development and infrastructure expansion, the drilling tools market has the potential to grow significantly by meeting the dual objectives of resource efficiency and sustainable operations.
Market Segmentation Analysis:
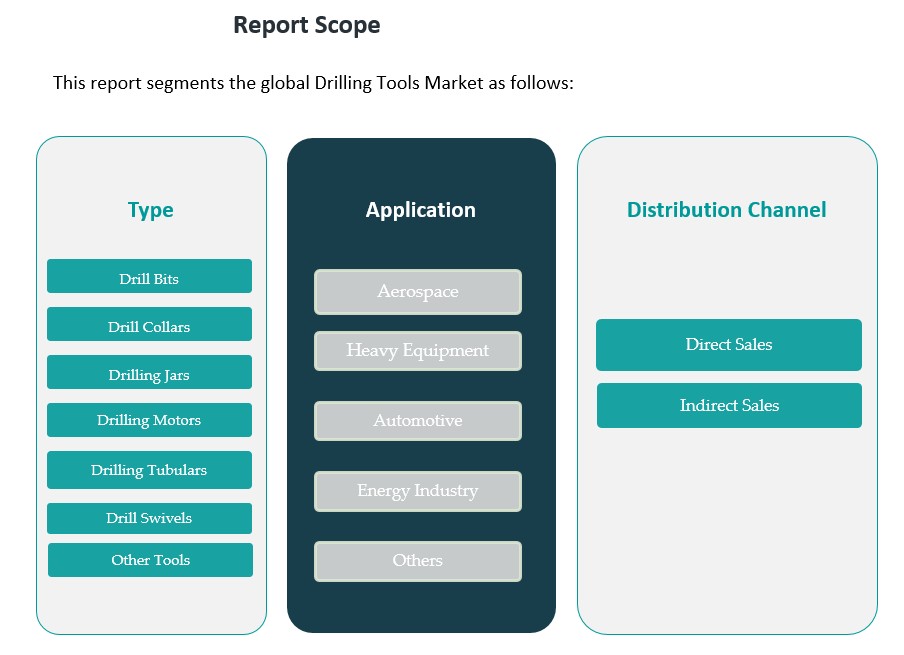
The global drilling tools market is segmented into three major categories: type, application, and distribution channel, each playing a vital role in shaping market dynamics.
By type, the market includes drill bits, drill collars, drilling jars, drilling motors, drilling tubulars, drill swivels, and other tools. Among these, drill bits hold a dominant share due to their critical role in cutting and penetrating geological formations. Drilling motors and tubulars are also gaining traction, especially in complex horizontal and directional drilling applications where performance and reliability are crucial.
By application, the market spans aerospace, heavy equipment, automotive, energy, and others. The energy segment remains the leading contributor, driven by expanding oil and gas exploration and production activities globally. The heavy equipment and automotive segments are also witnessing steady growth due to rising demand for durable and precise drilling components in manufacturing and infrastructure projects.
By distribution channel, the market is divided into direct and indirect sales. Direct sales dominate, as major oilfield service providers and end-users prefer purchasing directly from manufacturers to ensure product authenticity, technical support, and cost efficiency. However, indirect sales channels continue to play a role in reaching smaller players and emerging markets.
Segmentation:
By Type Segment
- Drill Bits
- Drill Collars
- Drilling Jars
- Drilling Motors
- Drilling Tubulars
- Drill Swivels
- Other Tools
By Application Segment
- Aerospace
- Heavy Equipment
- Automotive
- Energy
- Others
By Distribution Channel Segment
- Direct Sales
- Indirect Sales
Regional Analysis:
The global drilling tools market exhibits diverse regional dynamics, with each area contributing uniquely to the industry's growth.
North America
North America holds a significant share of the global drilling tools market, driven by extensive shale gas production and supportive energy policies in the United States. The region's advanced infrastructure and substantial investments in research and development have fostered the adoption of cutting-edge drilling technologies. Canada also contributes to the market through its robust oil sands exploration activities.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the drilling tools market, fueled by increasing energy demand and industrialization in countries like China and India. China's focus on expanding its shale gas reserves and India's investments in onshore drilling projects have significantly boosted the demand for advanced drilling equipment. Additionally, Australia's offshore exploration activities contribute to the region's market expansion.
Middle East & Africa
The Middle East & Africa region maintains a strong presence in the drilling tools market due to its abundant oil and gas reserves. Countries like Saudi Arabia, the United Arab Emirates, and Nigeria continue to invest heavily in exploration and production activities, necessitating the use of sophisticated drilling tools. The region's focus on enhancing production capacities to meet global energy demands further propels market growth.
Europe
Europe's drilling tools market is influenced by ongoing exploration activities in the North Sea and increasing investments in renewable energy projects. Countries such as Norway and the United Kingdom are actively engaged in offshore drilling operations, requiring advanced tools to navigate complex geological formations. The region's commitment to environmental sustainability also drives the development of eco-friendly drilling technologies.
Latin America
Latin America presents growth opportunities in the drilling tools market, particularly in countries like Brazil and Mexico. Brazil's offshore pre-salt oil fields and Mexico's energy reforms have attracted foreign investments, leading to increased drilling activities. The region's untapped hydrocarbon reserves and favorable regulatory frameworks contribute to its market potential.
Key Player Analysis:
- National Oilwell Varco
- Weatherford
- Schlumberger
- Baker Hughes
- Halliburton
- Rubicon Oilfield International
- Cougar Drilling Solutions
- Drilling Tools International
- Dynomax Drilling Tools
- Bico Drilling Tools
- Gyrodata
- Scientific Drilling
- Pacesetter Directional Drilling
- Tianhe Oil Group
- Wenzel Downhole Tools
Competitive Analysis:
The global drilling tools market is highly competitive, with leading players focusing on technological innovation, strategic partnerships, and global expansion to strengthen their market positions. Major companies such as Schlumberger, Halliburton, Baker Hughes, and National Oilwell Varco dominate the landscape through comprehensive product portfolios and integrated service offerings. These firms invest heavily in research and development to deliver advanced tools that enhance drilling efficiency and reduce operational risks. Emerging players are also gaining traction by offering cost-effective and specialized solutions tailored to regional needs. The competitive environment is further shaped by mergers and acquisitions, enabling companies to expand their capabilities and enter new markets. Additionally, the increasing emphasis on digitalization and sustainable drilling practices is compelling industry participants to innovate continuously. As competition intensifies, differentiation through technological advancements, service quality, and environmental compliance remains central to maintaining a competitive edge.
Recent Developments:
- In January 2025, Drilling Tools International Corp. (DTI) completed the acquisition of Titan Tools Services Ltd., a UK-based downhole tool rental company. This transaction, finalized on January 2, 2025, marks a significant milestone in DTI's global growth strategy. By integrating Titan, DTI has expanded its technological capabilities and service offerings, especially in the UK North Sea, Europe, and Africa.
- In August 2023, Boart Longyear launched its new IMPAKT rock tools bit, designed to improve drilling efficiency and durability. This product aims to address the growing demand for more robust and efficient drilling solutions in the mining, construction, and oil & gas exploration sectors. The IMPAKT bit is engineered to deliver superior performance in challenging rock formations, supporting the ongoing expansion of global infrastructure and resource development projects.
Market Concentration & Characteristics:
The global drilling tools market exhibits a moderately concentrated structure, with a handful of multinational corporations holding a substantial share of the overall market. Leading players such as Schlumberger, Halliburton, Baker Hughes, and National Oilwell Varco collectively command a significant portion due to their strong global presence, extensive product portfolios, and technological leadership. Despite this dominance, regional and niche manufacturers continue to serve localized markets with specialized offerings, fostering a balance between global influence and regional agility. The market is characterized by high capital intensity, a strong reliance on technological innovation, and cyclical demand patterns tied closely to oil and gas prices. Furthermore, the industry places strong emphasis on operational efficiency, safety standards, and environmental compliance, which influence product development and purchasing decisions. The increasing integration of digital technologies, including automation and real-time analytics, is reshaping operational dynamics, while the growing demand for sustainable solutions is redefining market competitiveness.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased exploration in deepwater and ultra-deepwater regions will drive demand for high-performance drilling tools.
- Continued advancement in automation and digitalization will enhance drilling accuracy and operational efficiency.
- Growing investment in unconventional resources, such as shale and tight oil, will expand market opportunities.
- Rising energy consumption in emerging economies will boost upstream drilling activities.
- Integration of AI and predictive analytics will optimize tool performance and reduce non-productive time.
- Environmental regulations will accelerate the development of low-impact, sustainable drilling technologies.
- Expansion of integrated service offerings will streamline procurement and improve cost efficiency for operators.
- Greater emphasis on remote and autonomous drilling solutions will reshape field operations.
- Strategic partnerships and mergers will continue to consolidate market positions and broaden portfolios.
- Increased focus on workforce training and upskilling will support the adoption of advanced tool technologies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Offshore and Unconventional Resource Exploration
The shift toward deepwater, ultra-deepwater, and unconventional resource projects is increasing demand for advanced and specialized drilling tools capable of operating in harsh and complex environments, particularly as mature oil fields decline.
Technological Advancements in Drilling Systems
Integration of automation, artificial intelligence, and real-time data analytics is enhancing drilling precision, reducing downtime, and lowering operational costs, making advanced drilling tools more attractive to operators.
Stringent Environmental and Safety Regulations
Tighter regulations are pushing oilfield service providers to develop more efficient, low-impact, and compliant drilling tools, driving innovation and adoption of new technologies in the market.
Growing Energy Infrastructure in Emerging Markets
Rapid industrialization and infrastructure development in regions like Asia-Pacific and Latin America are boosting upstream drilling activities, increasing the need for high-performance drilling tools.
Integrated Service Offerings and Digitalization
Operators are increasingly seeking bundled solutions that combine drilling tools with engineering, analytics, and field support, streamlining procurement and improving operational efficiency, which accelerates market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Drilling Tools Market?
What factors are driving the growth of the Global Drilling Tools Market?
What are the key segments within the Global Drilling Tools Market?
What are some challenges faced by the Global Drilling Tools Market?
Who are the major players in the Global Drilling Tools Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Drill Bits
- 1.2.2 Drill Collars
- 1.2.3 Drilling Jars
- 1.2.4 Drilling Motors
- 1.2.5 Drilling Tubulars
- 1.2.6 Drill Swivels
- 1.2.7 Other Tools
- 1.3 By Application
- 1.3.1 Energy
- 1.3.2 Aerospace
- 1.3.3 Heavy Equipment
- 1.3.4 Automotive
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 7,023.15 million → 2032: USD 10,998.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drilling Tools Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drilling Tools Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drilling Tools Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drilling Tools Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drilling Tools Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drilling Tools Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drilling Tools Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drilling Tools Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 7,023.15 million → 2032: USD 10,998.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drilling Tools Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Drill Bits
- 12.3.7.2 Drill Collars
- 12.3.7.3 Drilling Jars
- 12.3.7.4 Drilling Motors
- 12.3.7.5 Drilling Tubulars
- 12.3.7.6 Drill Swivels
- 12.3.7.7 Other Tools
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Energy
- 12.4.7.2 Aerospace
- 12.4.7.3 Heavy Equipment
- 12.4.7.4 Automotive
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drilling Tools End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Drilling Tools Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Drilling Tools Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Drilling Tools Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Schlumberger
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Halliburton
- 18.4 Baker Hughes
- 18.5 National Oilwell Varco
- 18.6 Weatherford
- 18.7 Drilling Tools International
- 18.8 Rubicon Oilfield International
- 18.9 Cougar Drilling Solutions
- 18.10 Dynomax Drilling Tools
- 18.11 Wenzel Downhole Tools
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

