
Dysphagia Supplement Market Overview:
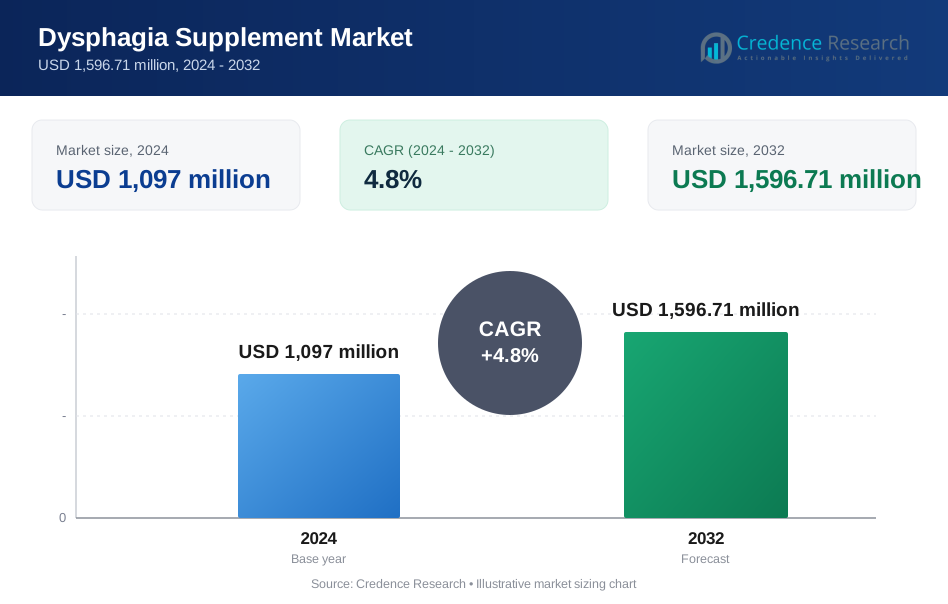
The global dysphagia supplements market was valued at USD 1,097 million in 2024 and is projected to reach USD 1,596.71 million by 2032, expanding at a compound annual growth rate (CAGR) of 4.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dysphagia Supplement Market Size 2024 | USD 1,097 million |
| Dysphagia Supplement Market, CAGR | 4.8% |
| Dysphagia Supplement Market Size 2032 | USD 1,596.71 million |
Dysphagia Supplement Market Insights
- Market growth is primarily driven by the rising geriatric population, increasing prevalence of stroke and neurological disorders, and stronger emphasis on preventing malnutrition and aspiration risks through standardized dysphagia management in hospitals and nursing homes.
- Key market trends include growing adoption of IDDSI-compliant formulations, improved palatability and viscosity stability, and rising demand for powder thickeners, which dominate the product segment with an estimated 38-42% market share, followed by oral nutritional supplements.
- The competitive landscape is moderately consolidated, with leading players focusing on clinical validation, institutional contracts, and portfolio expansion across powder thickeners, ready-to-drink beverages, and nutrient-dense supplements to strengthen long-term care penetration.
- Regionally, North America leads with around 38-40% market share, followed by Europe at 28-30%, while Asia Pacific holds 18-20% and represents the fastest-growing region due to aging demographics and expanding healthcare access.

Dysphagia Supplement Market Segmentation Analysis:
By Product:
By product, powder thickeners represent the dominant sub-segment in the dysphagia supplements market, accounting for approximately 38-42% of total market share. Their leadership is driven by dosage flexibility, cost efficiency, long shelf life, and strong clinical acceptance across hospitals and long-term care facilities. Powder thickeners allow caregivers to precisely tailor liquid viscosity to IDDSI standards, supporting safer swallowing outcomes. Ready-to-drink thickened beverages are the fastest-growing sub-segment due to convenience and consistency, while instant foods and oral nutritional supplements gain traction for addressing energy, protein, and micronutrient deficiencies among dysphagia patients.
- For instance, Nestlé Health Science’s ThickenUp® Clear is validated for use across IDDSI levels 1 through 4 (Slightly Thick to Extremely Thick) and maintains stable viscosity for at least 24 hours in hot and cold liquids once prepared, a performance benchmark widely adopted in clinical protocols."
By End User:
By end user, hospital pharmacies dominate the market with an estimated 35-40% share, supported by high inpatient dysphagia diagnosis rates and standardized clinical nutrition protocols. Hospitals drive demand for clinically validated, IDDSI-compliant products prescribed by speech-language pathologists and dietitians. Nursing homes follow closely due to chronic dysphagia prevalence among elderly residents. Retail pharmacies and drug stores are expanding steadily as home-care management rises, while supermarkets remain an emerging channel, primarily for ready-to-consume thickened beverages and instant dysphagia-friendly foods targeting caregivers and outpatient consumers.
- For instance, Fresenius Kabi integrates thickener and oral nutrition products into hospital nutrition pathways that support daily intake plans of 1,500-2,000 kcal, aligned with multidisciplinary clinical nutrition protocols.
Key Growth Drivers
Rising Geriatric Population and Neurological Disorders
The dysphagia supplements market is strongly driven by the rapid growth of the global elderly population and the increasing prevalence of neurological conditions such as stroke, Parkinson’s disease, Alzheimer’s disease, and amyotrophic lateral sclerosis. Aging significantly elevates the risk of swallowing disorders due to muscle weakness, reduced coordination, and cognitive decline. Post-stroke dysphagia alone affects a substantial proportion of hospitalized patients, creating sustained demand for thickened liquids and nutrition-modified supplements. Healthcare systems increasingly emphasize early diagnosis and nutritional intervention to prevent aspiration pneumonia, malnutrition, and dehydration. As longevity improves worldwide, long-term dysphagia management becomes essential, positioning specialized supplements as a standard component of geriatric and neurological care pathways across hospitals, nursing homes, and home-care environments.
- For instance, Danone Nutricia’s Nutilis® portfolio is routinely used in Parkinson’s and dementia units to maintain stable IDDSI-aligned viscosities for liquids administered 3-5 times daily, supporting safe hydration as disease progression limits oral motor control.
Growing Focus on Clinical Nutrition and Patient Safety
Heightened awareness of clinical nutrition’s role in patient recovery and safety is another major growth driver. Dysphagia supplements directly address critical risks such as choking, aspiration, and inadequate nutrient intake, which can prolong hospital stays and increase healthcare costs. Clinicians, speech-language pathologists, and dietitians increasingly prescribe standardized thickening agents and oral nutritional supplements as part of multidisciplinary care protocols. Regulatory alignment with frameworks such as the International Dysphagia Diet Standardisation Initiative (IDDSI) further reinforces adoption by providing clear viscosity classifications. This structured approach improves treatment consistency and boosts confidence among healthcare professionals, accelerating routine use of dysphagia supplements across acute, post-acute, and long-term care settings.
- For instance, Hormel Health Labs has developed pre-thickened beverages and instant foods that maintain viscosity stability for up to 3 hours after preparation, reducing bedside preparation errors in acute-care wards.
Expansion of Home Healthcare and Caregiver-Led Management
The shift toward home healthcare and outpatient management significantly contributes to market growth. Shorter hospital stays and cost-containment strategies encourage earlier discharge of dysphagia patients, transferring care responsibility to families and caregivers. Easy-to-use powder thickeners, ready-to-drink thickened beverages, and nutritionally complete supplements support safe swallowing outside institutional environments. Growing caregiver education, physician recommendations, and retail availability further strengthen adoption. As healthcare systems prioritize community-based care models, dysphagia supplements increasingly serve as essential tools to maintain nutritional adequacy, reduce hospital readmissions, and improve quality of life for patients managed at home.
Key Trends & Opportunities
Innovation in Palatability and Texture Stability
Product innovation focused on taste, mouthfeel, and texture stability is a major trend shaping the dysphagia supplements market. Traditional starch-based thickeners often altered flavor and lost viscosity over time, limiting patient adherence. New-generation formulations using advanced gum blends provide stable thickness, clearer appearance, and improved sensory experience. Manufacturers are also expanding flavor varieties and food-like textures to reduce consumption fatigue. These improvements significantly enhance patient compliance, especially among elderly and neurologically impaired users, creating strong opportunities for premium and differentiated product offerings within both institutional and consumer channels.
- For instance, SimplyThick uses a xanthan-gum–based formulation that maintains IDDSI-aligned viscosity for up to 12 hours after preparation in hot and cold beverages, enabling batch preparation in hospital and long-term care settings without texture degradation.
Rising Demand for Nutrient-Dense and Condition-Specific Formulations
Another key opportunity lies in the development of nutrient-dense and condition-specific dysphagia supplements. Patients with swallowing disorders often suffer from protein-energy malnutrition, sarcopenia, and micronutrient deficiencies. In response, manufacturers are formulating high-protein, calorie-dense, vitamin- and mineral-fortified supplements in swallow-safe consistencies. Products tailored for oncology, post-stroke recovery, and chronic neurological conditions are gaining traction. This trend aligns dysphagia management with broader clinical nutrition goals, allowing companies to expand their portfolios beyond thickening agents into comprehensive therapeutic nutrition solutions.
- For instance, Medtrition Inc. offers texture-modified oral nutritional supplements, such as Gelatein Plus, designed for dysphagia patients that deliver 160 kcal and 20 g of protein per 118 mL (4 oz) serving, supporting muscle maintenance and energy intake in post-acute and rehabilitation settings."
Key Challenges
High Product Costs and Limited Reimbursement Coverage
Cost remains a significant challenge for the dysphagia supplements market, particularly in price-sensitive regions. Specialized formulations, clinical validation, and compliance with viscosity standards increase production costs, which are often passed on to patients or caregivers. In many countries, dysphagia supplements receive limited or inconsistent reimbursement, restricting access for long-term users. Nursing homes and hospitals operating under tight budgets may also limit product variety. These financial constraints can delay adoption, reduce treatment adherence, and create disparities in dysphagia care, especially among elderly populations requiring prolonged nutritional support.
Low Awareness and Underdiagnosis in Non-Clinical Settings
Despite medical advances, dysphagia remains underdiagnosed outside hospital environments, presenting a key barrier to market expansion. Mild to moderate swallowing difficulties often go unreported, particularly among aging individuals living independently. Lack of awareness among caregivers and limited access to speech-language pathology services delay intervention. As a result, patients may rely on inappropriate food modifications rather than clinically validated supplements, increasing health risks. Overcoming this challenge requires sustained education initiatives, improved screening practices, and stronger collaboration between healthcare providers and community-based care networks to ensure timely and effective dysphagia management.
Regional Analysis
North America:
North America leads the dysphagia supplements market, accounting for approximately 38-40% of global market share. Market dominance is supported by advanced healthcare infrastructure, high diagnosis rates of dysphagia, and strong adoption of clinical nutrition protocols in hospitals and long-term care facilities. The region benefits from a large aging population and a high prevalence of stroke and neurodegenerative disorders. Strict adherence to IDDSI standards, strong reimbursement coverage in institutional settings, and the presence of established clinical nutrition manufacturers further reinforce demand. Home healthcare expansion and caregiver awareness continue to support steady market growth.
Europe:
Europe represents around 28-30% of the global dysphagia supplements market, driven by a rapidly aging population and strong public healthcare systems. Countries such as Germany, the UK, France, and Italy show high utilization of thickened liquids and oral nutritional supplements in hospitals and nursing homes. Widespread implementation of standardized dysphagia diets and strong involvement of speech-language therapists support consistent demand. Government-backed elderly care programs and rising focus on malnutrition prevention further strengthen adoption. Growth remains stable as healthcare providers increasingly integrate dysphagia supplements into routine geriatric and neurological care pathways.
Asia Pacific:
Asia Pacific accounts for approximately 18-20% of the global market and is the fastest-growing regional segment. Rising life expectancy, increasing incidence of stroke, and expanding healthcare access in countries such as Japan, China, South Korea, and Australia drive market expansion. Japan represents a key market due to its advanced elderly care ecosystem and early adoption of texture-modified foods. Improving awareness of clinical nutrition, growth in long-term care facilities, and expanding retail availability of dysphagia supplements support uptake. However, market penetration varies significantly across developing economies within the region.
Latin America:
Latin America holds an estimated 6-7% share of the global dysphagia supplements market, with growth driven by gradual improvements in healthcare infrastructure and increasing recognition of dysphagia-related complications. Brazil and Mexico lead regional demand due to larger elderly populations and expanding hospital networks. Adoption remains strongest in urban hospitals and private healthcare settings, while limited reimbursement and lower awareness constrain broader usage. Rising investment in clinical nutrition education and expansion of retail and pharmacy distribution channels are expected to support steady, albeit moderate, market growth across the region.
Middle East & Africa:
The Middle East & Africa region accounts for approximately 4-5% of the global market, reflecting early-stage adoption of dysphagia supplements. Demand is concentrated in developed healthcare markets such as the GCC countries and South Africa, where hospitals and long-term care facilities increasingly adopt standardized dysphagia management protocols. Growing incidence of chronic diseases and improving access to clinical nutrition products support gradual growth. However, limited awareness, uneven healthcare access, and cost sensitivity continue to restrict widespread adoption, particularly across low-income and rural areas within the region.
Dysphagia Supplement Market Segmentations:
By Product
- Powder Thickener
- Ready-to-drink Thickened Beverages
- Instant Food
- Oral Nutritional Supplements
By End User
- Hospital Pharmacies
- Nursing Homes
- Retail Pharmacies
- Drug Stores
- Supermarket
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The dysphagia supplements market features a moderately consolidated competitive landscape characterized by the presence of global clinical nutrition companies and specialized dysphagia-focused manufacturers. Leading players compete through strong medical nutrition portfolios, extensive hospital and long-term care distribution networks, and adherence to IDDSI-compliant formulations. Companies emphasize powder thickeners and oral nutritional supplements as core offerings, while expanding ready-to-drink thickened beverages to address convenience-driven demand. Product innovation centers on improving palatability, viscosity stability, and nutritional density to enhance patient compliance. Strategic initiatives include portfolio expansion, clinical education programs for healthcare professionals, and partnerships with hospitals and nursing homes. Established brands benefit from strong physician trust and long-term supply agreements, while smaller players focus on niche formulations and regional penetration. Overall, competition intensifies around quality, clinical validation, and the ability to offer comprehensive dysphagia nutrition solutions across care settings.
Key Player Analysis
- Nestlé Health Science
- Danone S.A.
- Fresenius Kabi
- Hormel Health Labs
- Kent Precision Foods Group, Inc.
- Medtrition Inc.
- Saraya Co. Ltd.
- SimplyThick
- Flavor Creations
Recent Developments
- In October 2024, Hormel Health Labs’ dysphagia and other specialty nutrition product lines were acquired by Lyons Magnus, enabling potential portfolio acceleration through expanded foodservice and clinical nutrition distribution (impacting broader availability of Thick & Easy® and related items).
- In June 2024, Kent Precision Foods Group expanded its clinical and dysphagia nutrition manufacturing capabilities in the U.S. by scaling production of texture-modified beverages and instant nutrition powders used in medical and long-term care settings. The expansion supported higher output of ready-to-mix and ready-to-consume dysphagia-appropriate formulations designed to maintain consistent viscosity during extended holding times, strengthening supply reliability for hospital and senior-care foodservice customers.
Report Coverage
The research report offers an in-depth analysis based on Product, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for dysphagia supplements will rise steadily with the global increase in the elderly population and age-related swallowing disorders.
- Clinical nutrition will become more integrated into standard dysphagia care protocols across hospitals and long-term care facilities.
- Powder thickeners will continue to dominate product demand due to flexibility, cost efficiency, and clinical acceptance.
- Ready-to-drink thickened beverages will gain faster adoption driven by convenience and reduced preparation errors.
- Manufacturers will focus on improving taste, texture stability, and patient compliance to enhance long-term usage.
- Nutrient-dense and protein-enriched formulations will see stronger uptake to address malnutrition and sarcopenia risks.
- Home healthcare and caregiver-led dysphagia management will increasingly influence product design and distribution.
- Compliance with standardized dysphagia diet frameworks will remain critical for market participation and trust.
- Retail and pharmacy-based distribution will expand as awareness of dysphagia management improves.
- Emerging markets will offer growth opportunities as healthcare access, diagnosis rates, and elderly care infrastructure strengthen.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Dysphagia supplement market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dysphagia supplement market projected to grow between 2024 and 2032?
Which Dysphagia supplement segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dysphagia supplement market?
Who are the leading companies in the Dysphagia supplement market?
Which region commanded the largest share of the Dysphagia supplement market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dysphagia Supplement Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dysphagia Supplement Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,097 million → 2032: USD 1,596.71 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dysphagia Supplement Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dysphagia Supplement Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dysphagia Supplement Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dysphagia Supplement Market Drivers
- 3.3 Dysphagia Supplement Market Restraints & Challenges
- 3.4 Dysphagia Supplement Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dysphagia Supplement Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dysphagia Supplement Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dysphagia Supplement category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dysphagia Supplement Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Dysphagia Supplement Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Dysphagia Supplement market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dysphagia Supplement Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dysphagia Supplement Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Dysphagia Supplement Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dysphagia Supplement (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Dysphagia Supplement Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dysphagia Supplement Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Dysphagia Supplement Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dysphagia Supplement Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dysphagia Supplement Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dysphagia Supplement Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dysphagia Supplement Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dysphagia Supplement Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dysphagia Supplement Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
