
Market Overview:
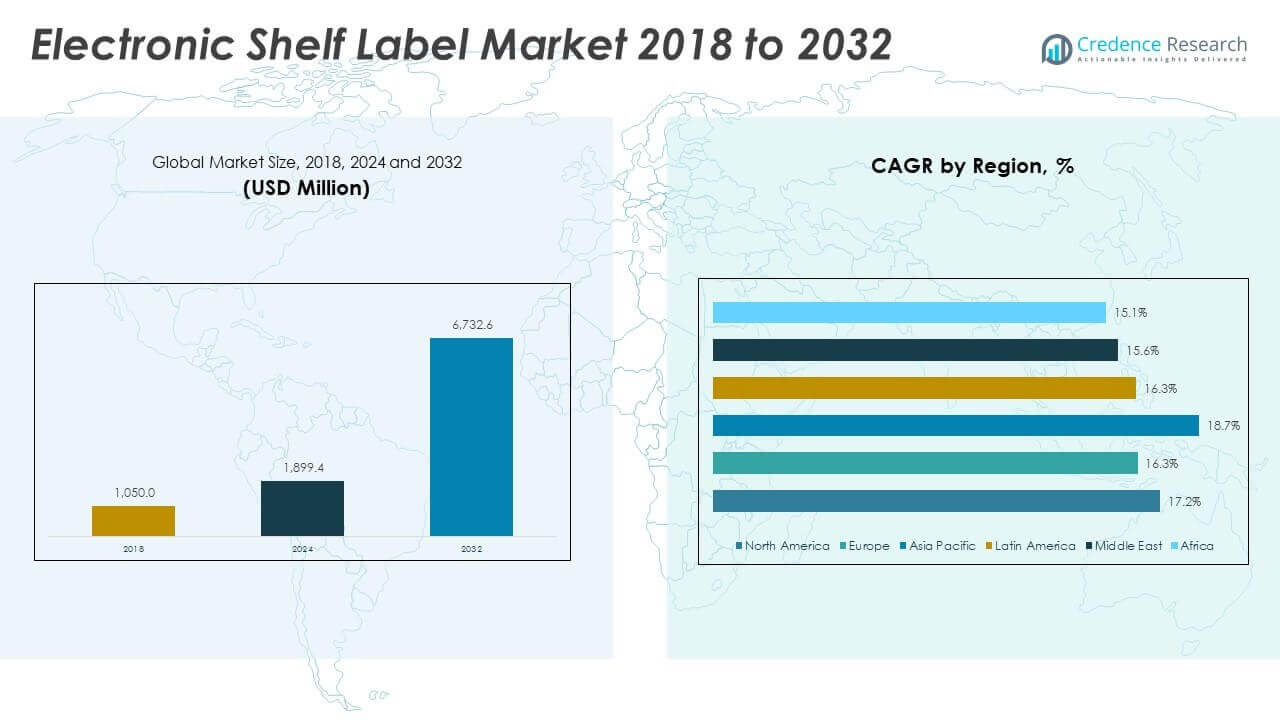
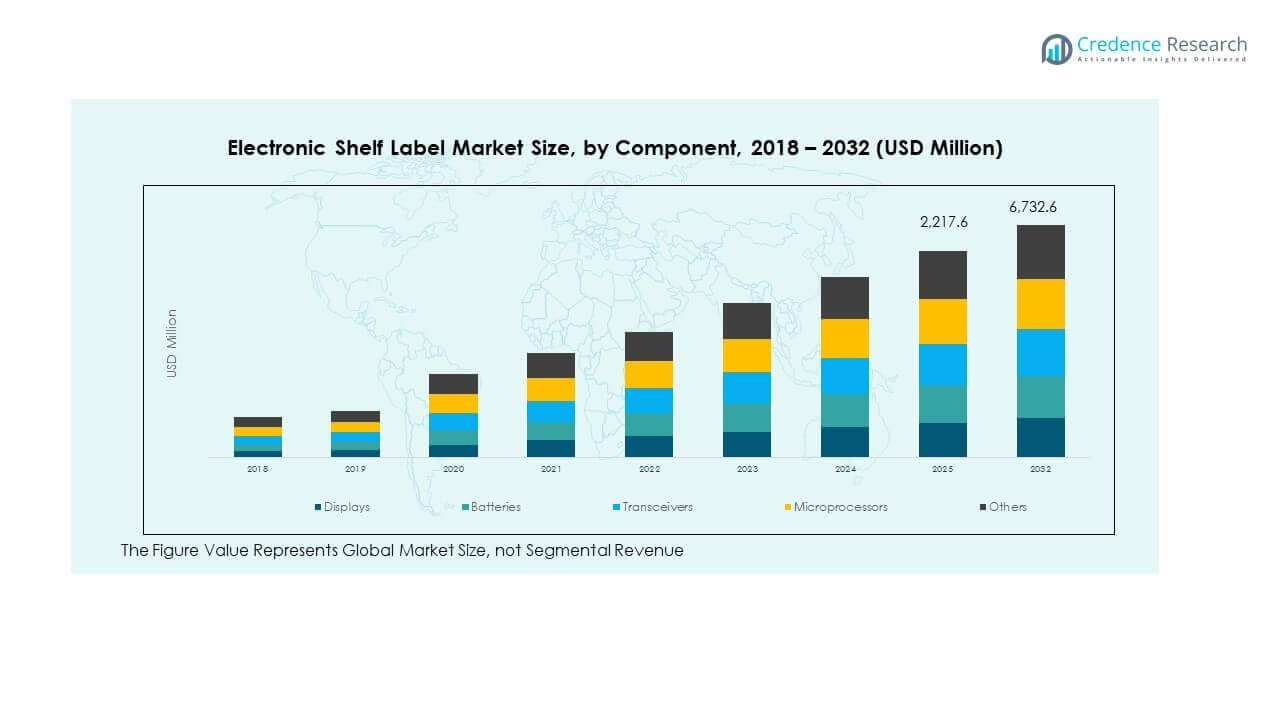
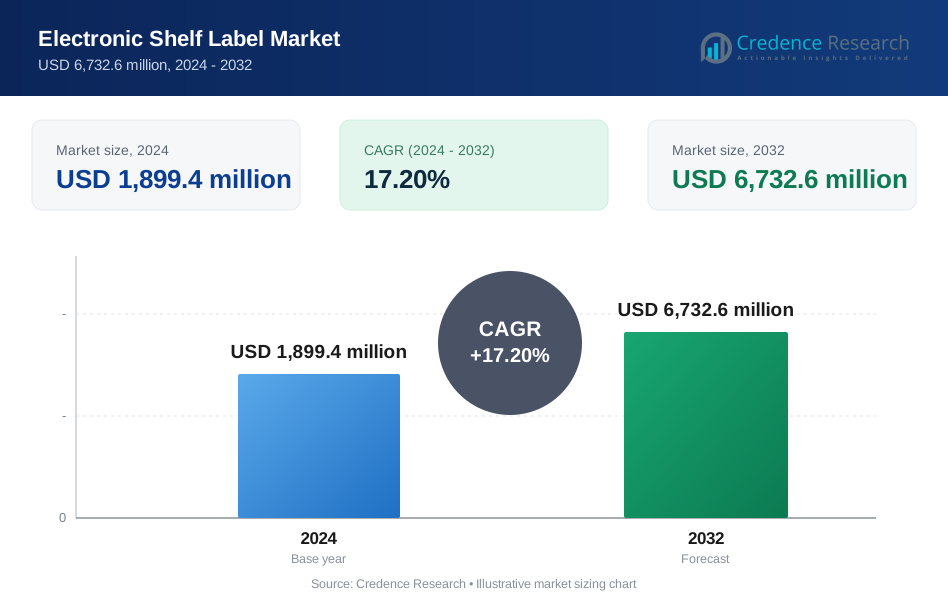
The Electronic Shelf Label Market size was valued at USD 1,050.0 million in 2018 to USD 1,899.4 million in 2024 and is anticipated to reach USD 6,732.6 million by 2032, at a CAGR of 17.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Shelf Label Market Size 2024 | USD 1,899.4 million |
| Electronic Shelf Label Market, CAGR | 17.2% |
| Electronic Shelf Label Market Size 2032 | USD 6,732.6 million |
The market is driven by the rising adoption of automation and digitalization across retail environments, as retailers seek efficient solutions for dynamic pricing and inventory management. The growing demand for cost reduction, improved operational efficiency, and enhanced customer experience supports the deployment of electronic shelf labels. Advancements in wireless communication technologies and integration with IoT platforms further strengthen the adoption of these systems, making them a key component in modern retail strategies.
Geographically, Europe leads the market due to strong penetration of digital retail technologies and stringent pricing regulations, followed by North America, where large-scale retailers invest in automation to stay competitive. The Asia-Pacific region is emerging rapidly as countries such as China, Japan, and South Korea expand smart retail infrastructure and adopt electronic shelf labels to improve store efficiency. Meanwhile, regions like Latin America and the Middle East show promising growth, driven by modernizing retail chains and increasing interest in digital transformation.
Market Insights:
- The Electronic Shelf Label Market size was valued at USD 1,050.0 million in 2018, USD 1,899.4 million in 2024, and is projected to reach USD 6,732.6 million by 2032, growing at a CAGR of 17.2%.
- North America leads with 39.1% share in 2024, driven by advanced IT infrastructure and large-scale adoption by supermarkets and retail chains.
- Europe holds 24.3% share, supported by strict pricing regulations and early digital retail adoption, while Asia Pacific follows with 23.4% share, reflecting rapid smart retail growth.
- Asia Pacific is the fastest-growing region, expanding at 18.7% CAGR, supported by strong investments in China, Japan, and India’s retail modernization.
- By component, batteries hold ~22% share and transceivers ~21% share in 2024, reflecting their critical role in extending operational life and enabling seamless connectivity.
Market Drivers:
Rising Retail Digitalization and Pricing Optimization Needs
The Electronic Shelf Label Market is driven by the growing digital transformation across retail chains worldwide. Retailers seek to replace manual price tags with automated systems that ensure accuracy and reduce operational costs. The demand for dynamic pricing strategies has increased with changing consumer preferences and competitive markets. It creates opportunities for retailers to instantly update shelf prices, improving responsiveness to demand and promotions. Retailers also aim to enhance customer trust by displaying consistent and accurate prices. Automation of shelf management saves labor costs and minimizes human errors. Rising investments in smart retail infrastructure support this adoption. The shift toward operational efficiency and enhanced store performance strengthens its growth trajectory.
- For example, in April 2023, SES-imagotag announced the rollout of its new VUSION platform with Walmart, deploying 60 million digital shelf labels across 500 U.S. stores in the first phase.
Integration with IoT Platforms and Enhanced Store Efficiency
Integration of ESLs with IoT platforms is another strong growth driver in the Electronic Shelf Label Market. It enables retailers to create intelligent and connected store ecosystems that offer real-time insights. Retailers utilize connected devices for monitoring inventory, tracking customer preferences, and analyzing sales data. This integration provides better synchronization between shelf pricing, back-end inventory, and promotional activities. It supports retailers in executing advanced strategies to maximize revenue and reduce waste. ESL systems also contribute to sustainability by reducing paper and material consumption. Companies view this as an essential step in aligning with green initiatives. It reinforces the role of ESLs as central to smart and future-ready retail operations.
Increasing Demand for Automation and Labor Cost Reduction
The Electronic Shelf Label Market benefits significantly from the increasing need for automation in retail operations. Retailers face rising labor costs and require technology to streamline repetitive tasks. ESL systems allow faster price updates across thousands of SKUs with minimal staff involvement. This improves accuracy and frees employees to focus on customer service. Automation also addresses operational challenges during peak shopping seasons. Retailers in highly competitive markets adopt ESLs to gain agility and efficiency. It ensures consistent execution of pricing and promotional strategies across multiple stores. Demand for solutions that reduce costs and optimize performance continues to rise steadily.
Enhanced Customer Experience and Real-Time Retail Communication
Enhancing customer experience remains a critical growth factor in the Electronic Shelf Label Market. Consumers expect accurate, transparent, and easily accessible product information in stores. ESLs provide real-time updates on discounts, product availability, and promotions directly on shelves. Retailers use this to build trust and encourage repeat purchases. Advanced ESLs offer features such as QR codes, enabling customers to access detailed product information. This integration strengthens engagement and supports omnichannel retail strategies. Retailers prioritize delivering seamless shopping journeys by leveraging ESL technologies. It positions ESLs as tools for strengthening both operational efficiency and customer satisfaction.
- For example, Leroy Merlin, a global DIY retailer, partnered with Hanshow to integrate ESLs across over 50,000 products in France, pairing ESLs with the Leroy Merlin mobile app. This provides in-store geolocation, real-time access to product details and reviews, and interactive features directly at the shelf, enhancing both customer experience and operational transparency.
Market Trends:
Expansion of Omnichannel Retail and Smart Store Adoption
A prominent trend shaping the Electronic Shelf Label Market is the adoption of omnichannel strategies. Retailers aim to integrate online and offline operations for seamless customer experiences. ESL systems play a key role in enabling synchronized pricing and promotions across multiple sales channels. This ensures customers encounter uniform offers whether shopping in-store or online. Smart store adoption further expands with retailers deploying advanced ESL solutions to align with digital ecosystems. Features such as real-time promotions and automated markdowns enhance customer satisfaction. Retailers view ESL technology as a bridge between e-commerce and physical retail. It strengthens competitiveness in the evolving retail landscape.
- Carrefour became the first major grocer in Europe to pilot the VusionGroup EdgeSense solution in its Villabé hypermarket in 2024. The installation included approximately 70,000 electronic shelf labels, 500 shelf-monitoring cameras, and 7,000 EdgeSense rails, supporting advanced in-store analytics and seamless omnichannel operations for real-time inventory and pricing alignment.
Growing Use of Advanced Display Technologies and Energy Efficiency
The Electronic Shelf Label Market witnesses growing adoption of advanced display technologies. Companies focus on enhancing visibility, resolution, and energy efficiency of ESL displays. E-ink and similar low-power technologies dominate the segment due to reduced energy consumption. ESLs with clearer displays attract attention and improve customer decision-making. Retailers adopt energy-efficient systems to align with sustainability goals and reduce operational expenses. Longer battery life reduces maintenance needs and boosts adoption rates. Vendors invest in R&D to improve product aesthetics and readability. It reinforces the market’s shift toward high-quality, eco-friendly, and durable ESL solutions.
- For example, Pricer’s electronic shelf labels, using optical wireless infrared technology, enable batteries to last up to 10 years and up to 15 years with the SmartTAG Power+ ESL while supporting real-time price automation and lower environmental impact for large-scale retail deployments.
Rising Adoption of AI-Driven Analytics and Data-Enabled Retailing
The Electronic Shelf Label Market increasingly embraces AI-driven analytics for smarter retail operations. ESL systems now collect and analyze in-store data to guide business strategies. Retailers use insights from ESL systems to optimize pricing and stock management. AI integration also enhances personalization by linking shelf displays with consumer purchase patterns. It enables predictive pricing models that help retailers respond quickly to demand shifts. Smart ESL systems strengthen decision-making with real-time data visibility. Retailers benefit from advanced tools that ensure accuracy and profitability. It reflects the growing role of ESLs in data-enabled retail transformation.
Partnerships and Expanding Global Deployments in Retail Chains
A key trend in the Electronic Shelf Label Market is the expansion of global partnerships and deployments. Vendors collaborate with large retailers to roll out ESLs across multiple geographies. Such partnerships accelerate adoption and ensure scalability of technology. Global retailers prioritize standardization, driving large-scale procurement of ESL solutions. This trend encourages ESL manufacturers to expand their footprints internationally. Retail chains in emerging economies also begin adopting ESLs to stay competitive. Vendors focus on offering scalable and customizable solutions to meet diverse needs. It highlights the growing momentum of ESL adoption across developed and developing markets alike.
Market Challenges Analysis:
High Initial Investment and Infrastructure Barriers
The Electronic Shelf Label Market faces challenges due to high initial implementation costs. Small and medium-sized retailers hesitate to adopt ESLs because of significant capital requirements. Infrastructure upgrades, including wireless communication systems, add to the financial burden. Integration with existing IT and inventory systems requires technical expertise. Retailers in developing economies often lack resources for full-scale adoption. Vendors must address these barriers with affordable and scalable solutions. Competition from traditional labeling methods also slows adoption. It creates a gap between interest in digital transformation and actual investment capabilities.
Technical Complexities and Security Concerns
Technical complexities present another challenge in the Electronic Shelf Label Market. ESLs require robust connectivity, making them dependent on reliable wireless networks. Any disruptions impact the efficiency of real-time pricing updates. Security concerns also arise with connected ESL systems, as data breaches or unauthorized access pose risks. Maintenance and battery replacement for large-scale deployments demand additional resources. Integration difficulties with legacy retail systems further complicate adoption. Retailers must ensure that ESL solutions align with compliance and security standards. Vendors are under pressure to address these concerns while delivering reliable solutions. It limits adoption speed in some regions and industries.
Market Opportunities:
Expanding Smart Retail Ecosystems and Integration with AI
The Electronic Shelf Label Market holds strong opportunities through expansion of smart retail ecosystems. ESL systems increasingly integrate with AI-driven platforms for advanced retail operations. Retailers benefit from predictive analytics, demand forecasting, and consumer behavior insights. Integration supports personalized promotions, enhancing customer loyalty and engagement. Retailers can link ESLs with mobile applications for improved shopping experiences. Companies in this space focus on offering value-added services to drive adoption. It positions ESLs as integral components of connected and intelligent retail infrastructures.
Growth Potential in Emerging Economies and Retail Modernization
The Electronic Shelf Label Market also benefits from rising modernization of retail in emerging economies. Countries in Asia-Pacific, Latin America, and the Middle East witness rapid digital transformation in retail. Growing investments in infrastructure and smart technologies support ESL deployment. Expanding supermarkets, hypermarkets, and convenience store chains adopt ESLs to improve efficiency. Emerging markets provide untapped growth potential for global vendors. Retailers in these regions prioritize cost-effective and scalable solutions to meet diverse consumer needs. It highlights significant opportunities for vendors to expand footprints and gain competitive advantage.
Market Segmentation Analysis:
The Electronic Shelf Label Market is segmented
By product type into e-paper displays, graphic e-paper displays, and LCDs. E-paper displays dominate due to their energy efficiency and high readability, making them preferred in large-scale retail environments. Graphic e-paper displays gain traction with advanced visual capabilities that support branding and promotions. LCDs remain relevant for applications requiring dynamic visuals, though their adoption is more limited compared to e-paper solutions. Each product type addresses unique requirements, allowing retailers to align technology with store format and consumer engagement goals.
- For example, Opticon’s ESL platform, incorporating radio-optimized e-paper labels and LCD displays, supports retailers including Tenda Atacado. The LCD labels enable dynamic visual applications in select store formats, while e-paper solutions are deployed broadly due to lower energy consumption and extended battery life.
By component, the market includes displays, batteries, transceivers, microprocessors, and others. Displays form the core of ESL systems, supported by batteries that determine operational lifespan and maintenance cycles. Transceivers and microprocessors enhance connectivity and data processing, ensuring real-time synchronization with inventory systems. Other components contribute to customization and integration across diverse retail networks. The strength of this segment lies in continuous innovations that improve reliability, performance, and efficiency.
By communication technology, the market is segmented into radio frequency, infrared, near-field communications (NFC), and others. Radio frequency leads due to its superior range and scalability in large store environments. Infrared finds niche applications in controlled settings, while NFC supports interactive retail strategies and mobile connectivity. Other emerging technologies expand the possibilities for data transfer, making communication a vital enabler of ESL adoption.
- For example, SES-imagotag (now VusionGroup) has deployed its VUSION platform with Walmart in the U.S., rolling out 60 million electronic shelf labels across 500 stores in the first phase, with plans to expand to thousands more locations by 2026
By size, the market covers ≤3 inches, 3 to 7 inches, 7 to 10 inches, and ≥10 inches. Smaller labels are widely used in supermarkets for price accuracy, while mid-range sizes dominate convenience and specialty stores. Larger formats support product promotions and detailed information in premium segments.
By application, retail holds the largest share, followed by industrial use where ESLs enhance warehouse and logistics operations. Other applications continue to evolve, reflecting the adaptability of the technology across sectors.
Segmentation:
By Product Type
- E-paper Displays
- Graphic E-paper Displays
- LCDs
By Component
- Displays
- Batteries
- Transceivers
- Microprocessors
- Others
By Communication Technology
- Radio Frequency
- Infrared
- Near-field Communications (NFC)
- Others
By Size
- ≤ 3 inches
- 3 to 7 inches
- 7 to 10 inches
- ≥ 10 inches
By Application
- Retail
- Industrial
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Electronic Shelf Label Market size was valued at USD 415.4 million in 2018 to USD 743.0 million in 2024 and is anticipated to reach USD 2,630.0 million by 2032, at a CAGR of 17.2% during the forecast period. North America accounts for 39.1% share of the global market in 2024. The Electronic Shelf Label Market in the region benefits from strong adoption by large retail chains and supermarkets that prioritize digital transformation. It is driven by growing investments in automation and demand for dynamic pricing across e-commerce-integrated retail networks. Retailers in the U.S. lead adoption with large-scale deployments supported by advanced IT infrastructure. Canada follows with increased interest in modernizing store operations, while Mexico witnesses rising penetration in urban retail formats. The presence of leading technology providers accelerates innovation and supports customized solutions. It is further supported by regulatory emphasis on accurate pricing and operational efficiency. Strong competition among retailers pushes adoption of ESLs as a differentiating factor in customer engagement.
Europe
The Europe Electronic Shelf Label Market size was valued at USD 265.7 million in 2018 to USD 461.1 million in 2024 and is anticipated to reach USD 1,540.1 million by 2032, at a CAGR of 16.3% during the forecast period. Europe contributes 24.3% share of the global market in 2024. The Electronic Shelf Label Market in this region is supported by early adoption of digital technologies in retail. Countries such as Germany, France, and the UK dominate with advanced smart store ecosystems. It is driven by stringent regulations on pricing transparency and operational efficiency in supermarkets and hypermarkets. Retailers deploy ESLs to align with sustainability goals by reducing paper-based operations. Southern and Eastern Europe are emerging markets, with growing demand from mid-sized retailers. Companies in the region actively collaborate with technology vendors to launch scalable ESL solutions. It is further supported by the presence of global leaders such as VusionGroup and Displaydata. Retail modernization across urban centers ensures continued growth in adoption.
Asia Pacific
The Asia Pacific Electronic Shelf Label Market size was valued at USD 234.2 million in 2018 to USD 444.2 million in 2024 and is anticipated to reach USD 1,746.7 million by 2032, at a CAGR of 18.7% during the forecast period. Asia Pacific represents 23.4% share of the global market in 2024. The Electronic Shelf Label Market in this region is fueled by rapid expansion of retail infrastructure in China, Japan, South Korea, and India. Retailers adopt ESLs to manage high-volume transactions and growing consumer expectations for accurate pricing. It is also driven by the strong growth of convenience stores and supermarkets in urban areas. Countries such as Japan and South Korea lead in early adoption due to high digital readiness. China contributes significantly with large-scale retail modernization and smart retail investments. India and Southeast Asia represent emerging opportunities with rising focus on automated retail management. Strong manufacturing capabilities in the region also lower deployment costs. It positions Asia Pacific as one of the fastest-growing ESL markets globally.
Latin America
The Latin America Electronic Shelf Label Market size was valued at USD 75.9 million in 2018 to USD 136.2 million in 2024 and is anticipated to reach USD 452.3 million by 2032, at a CAGR of 16.3% during the forecast period. Latin America captures 7.2% share of the global market in 2024. The Electronic Shelf Label Market in the region grows steadily with rising modernization of retail chains. Brazil dominates adoption, supported by its large supermarket and hypermarket base. Mexico and Argentina show promising demand as retailers invest in automation to improve efficiency. It is driven by growing competition in consumer goods and the need for dynamic pricing models. Retailers explore ESLs to cut operational costs and ensure pricing accuracy across distributed store networks. Regional vendors partner with international suppliers to expand availability. It is further supported by increasing government focus on digital infrastructure. Adoption is expected to accelerate as mid-sized retailers embrace scalable ESL solutions.
Middle East
The Middle East Electronic Shelf Label Market size was valued at USD 37.0 million in 2018 to USD 62.3 million in 2024 and is anticipated to reach USD 197.3 million by 2032, at a CAGR of 15.6% during the forecast period. The region accounts for 3.3% share of the global market in 2024. The Electronic Shelf Label Market in the Middle East benefits from investments in smart retail and luxury shopping destinations. GCC countries, including the UAE and Saudi Arabia, lead adoption with advanced retail infrastructure. It is driven by demand for high-end customer experiences and accurate pricing in premium retail outlets. Israel shows growth potential due to its strong technology ecosystem. Turkey emerges as an expanding market supported by urban retail developments. Retailers integrate ESLs to align with international retail standards and digital transformation strategies. Vendors collaborate with large shopping mall operators to deploy scalable solutions. It reflects the region’s commitment to adopting modern retail technologies for competitive advantage.
Africa
The Africa Electronic Shelf Label Market size was valued at USD 21.9 million in 2018 to USD 52.6 million in 2024 and is anticipated to reach USD 166.3 million by 2032, at a CAGR of 15.1% during the forecast period. Africa contributes 2.8% share of the global market in 2024. The Electronic Shelf Label Market in this region remains at an early adoption stage. South Africa leads growth with expanding modern retail networks. Egypt shows rising demand, supported by the development of large shopping centers. Other parts of Africa face challenges due to limited infrastructure and high deployment costs. Retailers adopt ESLs selectively in urban areas to improve pricing accuracy and inventory control. International vendors explore partnerships to expand availability in key markets. It is also driven by growing interest in digitalization among leading regional retailers. Rising investments in retail modernization signal long-term growth potential for ESL adoption in Africa.
Key Player Analysis:
- Panasonic Connect Co., Ltd.
- SOLUM
- VusionGroup
- Hangzhou Zkong Networks Co., Ltd.
- Teraoka (Pty) Ltd
- Displaydata Ltd
- M2COMM
- Opticon
- Shanghai SUNMI Technology Co., Ltd.
- ComQi
- Hanshow Technology
- SUNLUX IOT Technology (Guangdong) Inc.
- Delfi Technologies A/S
- Infotek Software & Systems (P) Ltd
- Guangzhou Mengbian Information Technology Co., Ltd.
Competitive Analysis:
The Electronic Shelf Label Market is highly competitive, with global and regional players focusing on innovation, partnerships, and large-scale deployments. Key companies such as SOLUM, VusionGroup, Panasonic Connect, Hanshow, and Displaydata dominate with strong product portfolios and international reach. It is shaped by continuous advancements in display technology, wireless communication, and energy efficiency, which differentiate offerings and drive adoption. Smaller players and regional vendors strengthen competition by delivering cost-effective and customized solutions. Strategic moves such as mergers, acquisitions, and collaborations enable companies to expand geographic presence and scale. Leading firms invest in R&D to integrate IoT and AI capabilities, positioning ESLs as critical tools in smart retail transformation. Market share is concentrated among a few global leaders, but emerging vendors gain traction in niche applications and developing economies. The industry maintains a balance between consolidation by top players and innovation from new entrants.
Recent Developments:
- In August 2025, SOLUM introduced two new Electronic Shelf Label solutions, Newton A and Newton Core Plus, setting a new benchmark for affordable and premium ESL technology. Newton A features a four-color EPD display, seven-color LED indicator, and a seven-year battery life, while Newton Core Plus boasts a ten-year battery life and ten times faster update speeds, providing scalability for retailers of every size.
- In June 2025, VusionGroup successfully deployed its electronic shelf label solution at the IGA French's Forest grocery store in Australia, installing over 8,500 ESL units to automate pricing and promotions across all categories.
- In March 2025, Company Shop, a surplus food retailer in the UK, implemented electronic shelf labels across all its stores in partnership with Pricer and Renovotec. This deployment optimized real-time pricing updates and digital transformation, streamlining operations for all 13 locations within the month.
Market Concentration & Characteristics:
The Electronic Shelf Label Market demonstrates medium-to-high concentration, with a few multinational players holding significant revenue share. It is defined by rapid technological innovation, strong focus on energy-efficient e-paper displays, and increasing integration with digital retail platforms. The market shows characteristics of scalability, as ESL solutions are deployed across supermarkets, hypermarkets, and convenience stores. It emphasizes price accuracy, operational efficiency, and enhanced customer engagement, creating strong demand in both mature and emerging markets. Vendors compete on product quality, connectivity features, and service support. The industry reflects characteristics of both consolidations among leaders and opportunities for new entrants in specific regional markets. It continues to evolve as retailers prioritize smart store strategies and omnichannel integration.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Component, Communication Technology, Size and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Electronic Shelf Label Market will expand with growing demand for real-time price management across global retail chains.
- It will see accelerated adoption through integration with IoT and AI platforms to enhance predictive analytics and personalization.
- Sustainability goals will drive preference for energy-efficient e-paper displays and low-maintenance solutions.
- Smart store initiatives will push ESL deployment beyond retail into logistics, warehousing, and industrial applications.
- Advancements in NFC and mobile connectivity will strengthen customer engagement through interactive shelf communication.
- Regional players will capture opportunities in emerging economies with cost-effective and scalable offerings.
- Global vendors will focus on mergers, acquisitions, and strategic alliances to consolidate market presence.
- Increased emphasis on cybersecurity will shape product development and compliance standards.
- Expansion of omnichannel strategies will ensure synchronized pricing across physical and digital platforms.
- Continued innovation in display technologies will improve readability, durability, and design flexibility for diverse store formats.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Electronic Shelf Label (ESL) market?
What are the primary drivers of the ESL market?
Which regions are leading the ESL market?
How do ESLs benefit retailers?
Which regions are expected to see significant ESL market growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,899.4 million → 2032: USD 6,732.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Shelf Label Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Shelf Label Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Shelf Label Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Shelf Label Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Shelf Label Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Shelf Label Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Shelf Label Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Shelf Label Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,899.4 million → 2032: USD 6,732.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Shelf Label Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Shelf Label Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electronic Shelf Label Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electronic Shelf Label Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
