
Automotive Electronics Market Overview:
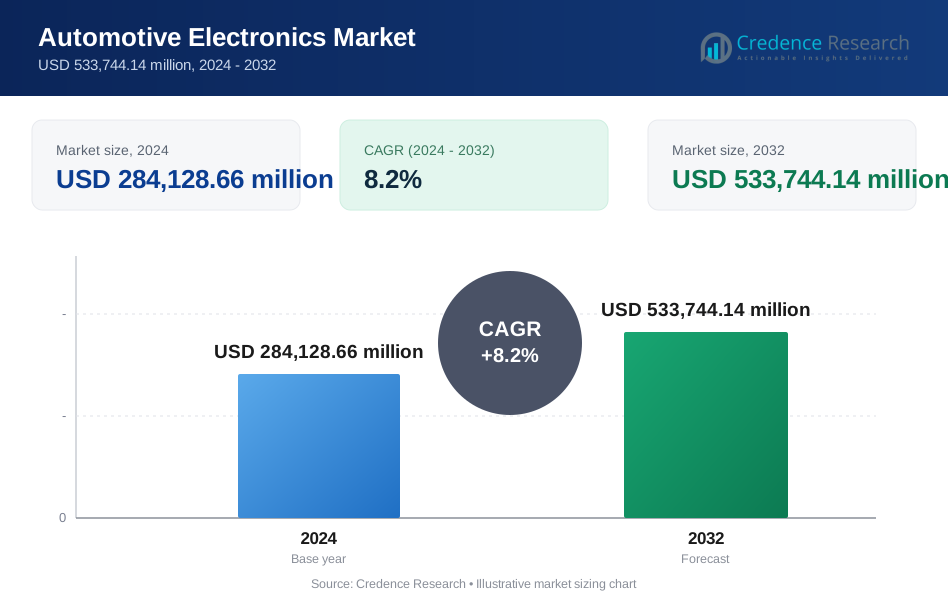
Automotive Electronics Market size was valued USD 284128.66 million in 2024 and is anticipated to reach USD 533744.14 million by 2032, at a CAGR of 8.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Electronics Market Size 2024 | USD 284128.66 million |
| Automotive Electronics Market, CAGR | 8.2% |
| Automotive Electronics Market Size 2032 | USD 533744.14 million |
Automotive Electronics Market Insights
- Market growth is primarily driven by increasing adoption of ADAS, electric powertrains, and software-defined vehicle architectures, with power electronics and ADAS together accounting for over 45% of total segment share due to safety mandates and EV penetration.
- Key market trends include the shift toward centralized and zonal E/E architectures, growing use of high-performance semiconductors, and deeper integration of embedded software, AI, and cybersecurity frameworks across vehicle platforms.
- Competitive dynamics remain intense, with leading Tier-1 suppliers and semiconductor companies focusing on R&D investments, platform standardization, and strategic collaborations to strengthen system integration and OEM alignment.
- Regionally, Asia-Pacific leads with an exact 44% market share, supported by high vehicle production, strong semiconductor manufacturing ecosystems, and rapid adoption of connected and electric vehicles across major automotive hubs.

Automotive Electronics Market Segmentation Analysis:
By Vehicle Type
The Automotive Electronics Market, by vehicle type, is dominated by passenger cars, which account for an estimated around 55% market share. This dominance is driven by high global production volumes, rapid integration of safety and comfort electronics, and increasing penetration of connected and semi-autonomous features. Passenger cars lead adoption of infotainment systems, electronic control units, body electronics, and advanced safety modules due to stringent safety regulations and rising consumer expectations. Growing electrification, premium feature penetration in mid-range models, and strong demand from urban mobility further accelerate electronics content per vehicle, reinforcing passenger cars as the leading sub-segment.
- For instance, ZF Friedrichshafen AG has advanced passenger-car electronics through its ProAI automotive supercomputer, which delivers computing performance exceeding 150 tera operations per second and supports centralized control of driver assistance, chassis, and infotainment functions within a single vehicle architecture.
By Point of Sale
By point of sale, Original Equipment Manufacturer (OEM) channels represent the dominant sub-segment, holding approximately 70% market share in automotive electronics. OEM dominance is supported by factory-level integration of complex electronic systems such as powertrain control units, advanced safety modules, and vehicle networking architectures. Increasing software-defined vehicle platforms, tighter system integration requirements, and regulatory mandates for safety features favor OEM-installed electronics over aftermarket solutions. Automakers also prioritize long-term supplier partnerships to ensure reliability, cybersecurity compliance, and seamless integration, driving consistent demand through OEM sales channels across both conventional and electric vehicles.
- For instance, Xilinx, Inc. has enabled OEM-grade integration through its Zynq UltraScale+ MPSoC platform, built on a 16-nanometer process and integrating a quad-core ARM Cortex-A53 CPU alongside programmable logic, while supporting 4K video processing at 60 frames per second and meeting ISO 26262 ASIL-D functional safety requirements for advanced driver assistance and centralized vehicle computing systems.
By Application
Among applications, Advanced Driver Assistance Systems (ADAS) emerge as the dominant segment, accounting for nearly 45% market share within automotive electronics applications. Growth is fueled by mandatory safety regulations, rising awareness of accident prevention, and rapid technological advancements in sensors, cameras, radar, and processing units. Features such as adaptive cruise control, automated emergency braking, and lane departure warning are increasingly standard across vehicle categories. The shift toward higher levels of vehicle autonomy, coupled with falling sensor costs and improved AI-based perception systems, continues to accelerate ADAS adoption and strengthen its leadership within application-based segmentation.
Key Growth Drivers
Rising Vehicle Electrification and Powertrain Transformation
The rapid shift toward electric and hybrid vehicles is a primary growth driver for automotive electronics. Electrified powertrains require advanced electronic components such as battery management systems, power semiconductors, inverters, onboard chargers, and thermal control units. Automakers increasingly rely on high-voltage electronics to improve energy efficiency, extend driving range, and ensure operational safety. In parallel, tightening emission regulations and government incentives accelerate electrification adoption, further increasing electronic content per vehicle. This structural transformation continues to elevate demand for reliable, high-performance automotive electronic systems across passenger and commercial vehicle segments.
- For instance, Valeo Inc. has developed an 800-volt silicon-carbide inverter rated for 300 kilowatts and a compact onboard charger delivering 22 kilowatts, while its 48-volt mild-hybrid systems integrate electric motors capable of providing 12 kilowatts of power, demonstrating measurable advancements in electrified powertrain electronics.
Increasing Integration of Advanced Driver Assistance Systems (ADAS)
The growing emphasis on vehicle safety and accident prevention strongly supports automotive electronics adoption. ADAS technologies such as adaptive cruise control, automatic emergency braking, lane departure warning, and blind-spot detection depend on sensors, cameras, radar, control units, and embedded software. Regulatory mandates and rising consumer awareness are pushing automakers to integrate ADAS as standard or optional features across vehicle categories. Continuous improvements in sensor accuracy, processing speed, and system redundancy further drive electronic complexity, reinforcing long-term demand for automotive-grade semiconductors and electronic control units.
- For instance, DENSO Corporation has developed a forward-looking millimeter-wave radar operating at 77 gigahertz with a detection range of 200 meters, combined with an image recognition ECU capable of processing 30 frames per second from high-definition cameras, enabling real-time object detection and collision avoidance in production vehicles.
Expansion of In-Vehicle Infotainment and Connectivity Solutions
Consumer demand for enhanced driving experiences is accelerating the deployment of infotainment, telematics, and connected vehicle solutions. Advanced displays, digital instrument clusters, voice recognition, navigation, and smartphone integration significantly increase electronic content within vehicles. Additionally, connectivity features supporting over-the-air updates, vehicle diagnostics, and cloud-based services are becoming essential. Automakers increasingly differentiate models through software-defined features, which depend on robust electronic architectures. This shift toward digitally integrated vehicles continues to fuel sustained growth in automotive electronics adoption.
Key Trends & Opportunities
Transition Toward Software-Defined and Centralized Vehicle Architectures
Automotive manufacturers are transitioning from distributed electronic control units to centralized and domain-based architectures. This trend reduces wiring complexity, lowers vehicle weight, and improves system scalability while enabling faster software updates. Centralized computing platforms support advanced functions such as autonomous driving, predictive maintenance, and real-time data processing. The growing focus on software-defined vehicles creates significant opportunities for suppliers offering high-performance processors, automotive operating systems, and cybersecurity solutions, reshaping the competitive landscape of automotive electronics.
- For instance, Visteon Corporation has developed its SmartCore domain controller built on Qualcomm Snapdragon automotive platforms, capable of supporting up to six high-resolution displays and processing graphics workloads exceeding 1.2 teraFLOPS, while consolidating cockpit, infotainment, and connectivity functions into a single centralized computing unit.
Growing Adoption of Autonomous and Semi-Autonomous Technologies
The gradual advancement toward autonomous driving presents long-term opportunities for automotive electronics providers. Autonomous systems require complex sensor fusion, artificial intelligence processing, high-speed data transmission, and redundant electronic architectures to ensure safety. Even partial automation levels significantly increase electronic content per vehicle. Investments in testing, validation, and functional safety compliance further strengthen demand for advanced electronic components. As regulatory frameworks mature, autonomous features are expected to expand beyond premium vehicles into broader market segments.
- For instance, Infineon Technologies AG has introduced its AURIX TC4x microcontroller family, featuring a tri-core lockstep architecture running at 500 megahertz, integrated hardware security modules, and support for up to 16 radar channels, enabling real-time sensor fusion and ASIL-D–compliant control for autonomous driving applications.
Rising Demand for Energy-Efficient and Lightweight Electronic Components
Vehicle manufacturers increasingly prioritize energy efficiency and lightweight design to improve fuel economy and extend electric vehicle range. This trend supports innovation in power electronics, wide-bandgap semiconductors, and compact electronic modules. Suppliers developing energy-efficient chips, advanced materials, and integrated systems gain competitive advantages. Lightweight electronics also contribute to improved vehicle performance and reduced emissions, creating sustained growth opportunities across both conventional and electric vehicle platforms.
Key Challenges
High Development Costs and Supply Chain Complexity
Automotive electronics development involves high research and engineering costs due to stringent reliability, safety, and performance requirements. Compliance with automotive standards increases testing cycles and extends time-to-market. Additionally, global supply chains for semiconductors and electronic components remain complex and vulnerable to disruptions. Fluctuations in raw material availability, geopolitical risks, and capacity constraints can impact production schedules and pricing, posing ongoing challenges for manufacturers and suppliers across the automotive electronics ecosystem.
Increasing System Complexity and Cybersecurity Risks
The growing integration of connected and software-driven electronics significantly increases vehicle system complexity. Managing interoperability between hardware, software, and communication networks presents technical challenges for automakers. At the same time, connected vehicles face rising cybersecurity risks, including data breaches and unauthorized system access. Ensuring secure communication, functional safety, and regulatory compliance requires continuous investment in cybersecurity frameworks and system validation, adding operational and cost pressures to automotive electronics development.
Regional Analysis
North America
North America dominates the Automotive Electronics Market with an estimated 38% market share, supported by advanced vehicle production, high adoption of ADAS, and strong electrification trends. Automakers and Tier-1 suppliers активно integrate electronic control units, infotainment systems, and power electronics to meet safety, emission, and connectivity standards. The U.S. leads regional demand due to large-scale EV deployment, software-defined vehicles, and autonomous driving pilots. Regulatory mandates for safety features such as electronic stability control and advanced braking systems further accelerate adoption. Strong R&D investment, semiconductor innovation, and collaborations between OEMs and technology firms continue to reinforce North America’s leadership position.
Europe
Europe accounts for approximately 30% of the global Automotive Electronics Market, driven by stringent emission regulations, rapid EV penetration, and strong demand for premium vehicles. Countries such as Germany, France, and the UK lead adoption of advanced powertrain electronics, battery management systems, and ADAS technologies. The region’s strong focus on vehicle electrification, lightweight platforms, and intelligent safety systems significantly boosts electronic content per vehicle. Regulatory frameworks supporting carbon neutrality and vehicle safety compliance encourage continuous innovation. Additionally, the presence of established automotive OEMs and electronics suppliers supports steady integration of advanced automotive semiconductor and sensor technologies.
Asia-Pacific
Asia-Pacific holds around 25% market share and represents the fastest-growing regional market for automotive electronics. China, Japan, South Korea, and India drive growth through high vehicle production volumes, expanding EV manufacturing, and increasing adoption of connected car technologies. Government incentives for electric mobility, local semiconductor manufacturing, and smart transportation infrastructure support market expansion. Rising consumer demand for infotainment, digital instrument clusters, and safety features in mid-range vehicles further accelerates penetration. Cost-efficient manufacturing, large-scale supply chains, and rapid technological adoption position Asia-Pacific as a key growth engine for automotive electronics globally.
Latin America
Latin America accounts for nearly 4% of the Automotive Electronics Market, supported by gradual modernization of vehicle platforms and improving safety regulations. Brazil and Mexico lead regional demand due to growing automotive manufacturing bases and increasing integration of basic electronic systems such as engine control units, infotainment, and driver assistance features. While adoption of advanced ADAS and electrification remains limited compared to developed regions, demand is steadily rising. OEMs focus on cost-optimized electronic solutions to address price-sensitive markets. Infrastructure development and regulatory alignment with global safety standards are expected to support long-term growth.
Middle East & Africa
The Middle East & Africa region holds about 3% market share, driven primarily by demand for passenger vehicles equipped with infotainment, climate control electronics, and safety systems. Gulf countries lead adoption due to higher disposable income and preference for technologically advanced vehicles, while Africa shows gradual uptake driven by urbanization and vehicle parc expansion. Electrification remains at an early stage; however, government initiatives promoting smart mobility and sustainability are emerging. Growth is supported by increasing imports of electronically equipped vehicles and gradual integration of automotive electronics in commercial and passenger fleets.
Automotive Electronics Market Size Segmentations:
By Vehicle Type:
- Two-wheeler
- Three-wheeler
By Point of Sale:
- Original Equipment Manufacturer (OEM)
- Aftermarket
By Application:
- Blind spot detection
- Parking assistance
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The automotive electronics market players such as ZF Friedrichshafen AG, Xilinx, Inc., Valeo Inc., DENSO Corporation, Visteon Corporation, Infineon Technologies AG, Hella GmbH & Co. KGaA, Robert Bosch GmbH, Continental AG, Hitachi Automotive. The automotive electronics market exhibits a highly competitive structure driven by rapid technological advancement, stringent safety regulations, and the accelerating shift toward electrification and software-defined vehicles. Market participants compete by strengthening in-house semiconductor design, embedded software capabilities, and system-level integration to deliver scalable electronic architectures. Innovation focuses on advanced driver assistance systems, power electronics for electric drivetrains, high-speed vehicle networking, and functional-safety-compliant control units. Strategic partnerships with automakers and technology providers support faster product validation and reduced development timelines, while modular platforms help manage cost pressures and customization demands. Companies also emphasize regional manufacturing expansion and supply-chain localization to mitigate component shortages and geopolitical risks. As vehicle intelligence, connectivity, and automation continue to increase, competitive intensity remains high, with differentiation increasingly defined by software expertise, reliability, and the ability to support long-term vehicle lifecycle requirements.
Key Player Analysis
- ZF Friedrichshafen AG
- Xilinx, Inc.
- Valeo Inc.
- DENSO Corporation
- Visteon Corporation
- Infineon Technologies AG
- Hella GmbH & Co. KGaA
- Robert Bosch GmbH
- Continental AG
- Hitachi Automotive Systems, Ltd.
Recent Developments
- In November 2025, Samsung Electronics, a global leader in technology, today announced that its latest lineup of products and services has been recognized by Consumer Technology Association, underscoring its dedication to enhancing consumer technology experiences through performance, design, and intelligence.
- In January 2025, VBOX Automotive unveiled its new testing solution for the purpose of validating the Speed Limit Information Function (SLIF) which is in accordance with the EU regulations. The test helps to configure the True Positive Distance metric which indicated the percentage of duration the vehicle’s display matches accurately with the real-world speed signs.
- In January 2025, HERE Technologies and the BMW Group today announced an extended partnership focused on improving the driving experience, road safety, and the delivery of mapping system. Here Technologies offers UniMap which aligns all standard and high definition, ADAS data in one single digital representation. This helps with a continuously updated map and improves the driving experience.
- In February 2024, Remsons Industries and Daiichi Infotainment established a joint venture aiming to provide innovative solutions which would help shaping the mobility sector. The venture goal revolves around developing automotive electronic solutions to cater to the next generation vehicles and focusing on advanced systems such as Acoustic Vehicle Alerting System (AVAS).
Report Coverage
The research report offers an in-depth analysis based on Vehicle Type, Point of Sale, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Vehicle architectures will continue shifting toward centralized and zonal electronic systems to reduce wiring complexity and improve scalability.
- Software-defined vehicles will drive sustained demand for high-performance processors, embedded software, and over-the-air update capabilities.
- Electrification will accelerate adoption of advanced power electronics, battery management systems, and high-voltage safety controls.
- Advanced driver assistance features will expand across mass-market vehicles, increasing integration of sensors, control units, and real-time data processing.
- Functional safety and cybersecurity requirements will intensify, driving investments in compliant hardware and secure software frameworks.
- In-vehicle connectivity will strengthen through higher-bandwidth networks to support infotainment, diagnostics, and vehicle-to-everything communication.
- Artificial intelligence will play a larger role in perception, predictive maintenance, and adaptive vehicle control systems.
- Modular and standardized electronic platforms will gain importance to shorten development cycles and control system costs.
- Regional manufacturing and supply-chain localization will increase to improve resilience and reduce dependency on single-source components.
- Collaboration between automakers, semiconductor firms, and software providers will deepen to accelerate innovation and commercialization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Automotive Electronics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automotive Electronics Market projected to grow between 2024 and 2032?
Which Automotive Electronics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Automotive Electronics Market?
Who are the leading companies in the Automotive Electronics Market?
Which region commanded the largest share of the Automotive Electronics Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Electronics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Electronics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 284,128.66 million → 2032: USD 533,744.14 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Electronics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Electronics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Electronics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Electronics Market Drivers
- 3.3 Automotive Electronics Market Restraints & Challenges
- 3.4 Automotive Electronics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Electronics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Electronics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Electronics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Electronics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Electronics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Electronics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Electronics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Electronics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Electronics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Electronics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Electronics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Electronics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Electronics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Electronics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Electronics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Electronics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Electronics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Electronics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Electronics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
