
Endoscopy Cameras Market Overview:
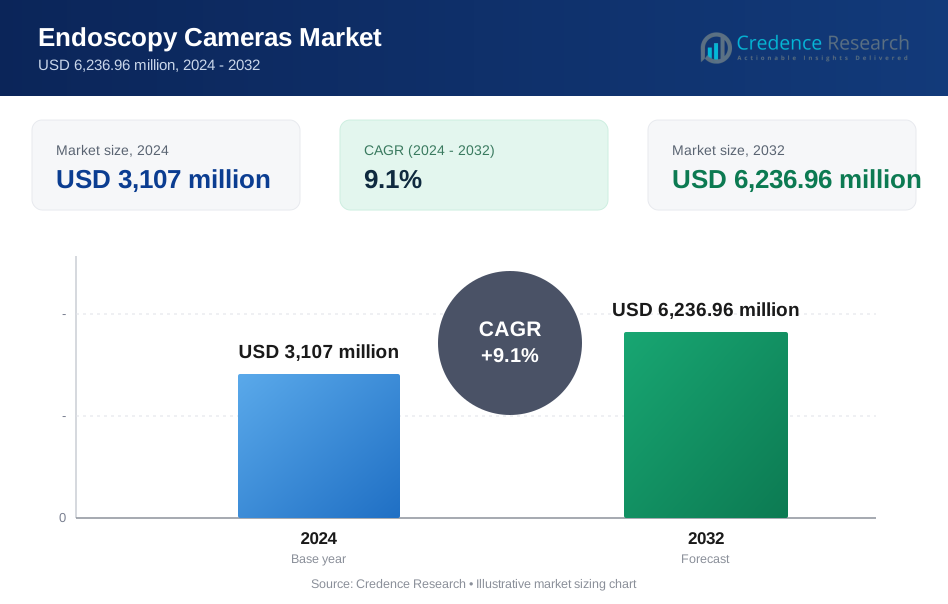
Endoscopy Cameras Market size was valued USD 3107 million in 2024 and is anticipated to reach USD 6236.96 million by 2032, at a CAGR of 9.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Endoscopy Cameras Market Size 2024 | USD 3107 million |
| Endoscopy Cameras Market, CAGR | 9.1% |
| Endoscopy Cameras Market Size 2032 | USD 6236.96 million |
Endoscopy Cameras Market Insights
- Market growth is strongly supported by increasing adoption of minimally invasive surgeries, where high-definition and ultra-high-definition endoscopy cameras improve visualization accuracy, clinical outcomes, and procedural efficiency across multiple specialties.
- Key market trends include rapid integration of advanced CMOS sensors, enhanced low-light imaging, digital signal processing, and compatibility with visualization systems, with HD and UHD camera segments collectively holding over 60% segment share due to widespread clinical preference.
- Competitive dynamics reflect a concentrated landscape, where leading manufacturers differentiate through optical innovation, system interoperability, robust after-sales support, and long-term partnerships with hospitals and ambulatory surgical centers.
- Regionally, North America leads with an exact 38% market share, supported by strong healthcare infrastructure and high capital spending, while Asia-Pacific shows the fastest expansion due to improving hospital capacity and procedural adoption.

Endoscopy Cameras Market Segmentation Analysis:
By Product
The endoscopy cameras market by product is dominated by flexible endoscopes, accounting for an estimated 41% market share, driven by their versatility across diagnostic and therapeutic procedures. Flexible systems enable high-definition imaging in complex anatomical pathways, supporting widespread adoption in GI and pulmonary endoscopy. Visualization systems follow as a critical supporting segment, benefiting from upgrades toward 4K and 3D imaging platforms that enhance procedural accuracy. Capsule endoscopes show steady uptake due to non-invasive diagnostics, while rigid endoscopes retain relevance in orthopedic and ENT procedures. Continuous innovation in CMOS sensors and light sources underpins product-level growth.
- For instance, OmniVision (an OMNIVISION Group Company) has developed compact CMOS imaging modules with pixel sizes down to 2.2 µm, paired with proprietary aspherical lens designs exceeding 150 line pairs per millimeter in resolving power, enabling sharper imaging in confined endoscopic environments without increasing device diameter.
By Application
By application, GI endoscopy represents the dominant sub-segment with approximately 46% market share, supported by high procedure volumes in gastroscopy and colonoscopy for cancer screening and chronic disease management. Laparoscopy remains a major contributor due to minimally invasive surgical adoption across general and gynecological procedures. Arthroscopy and ENT endoscopy maintain consistent demand from outpatient interventions, while pulmonary and OB/GYN endoscopy gain traction with improved visualization and patient safety standards. Rising screening programs, aging populations, and clinical preference for minimally invasive diagnostics continue to drive application-based expansion.
- For instance, Panasonic Corporation has developed medical imaging camera modules using MOS sensors with resolutions exceeding 8 million effective pixels, combined with real-time image signal processors capable of handling more than 60 frames per second.
By End User
Among end users, hospitals lead the market with an estimated 58% share, owing to high capital investment capacity, broad procedure portfolios, and availability of skilled endoscopists. Hospitals act as primary centers for complex diagnostic and therapeutic endoscopy, supporting sustained demand for advanced camera systems. Ambulatory surgical centers are the fastest-growing sub-segment, driven by shorter procedure times, lower costs, and increasing shift toward outpatient care models. Other end users, including specialty clinics, contribute steadily as compact and portable endoscopy systems improve accessibility beyond large hospital settings.
Key Growth Drivers
Rising Volume of Minimally Invasive Procedures
The growing preference for minimally invasive surgeries strongly drives demand for endoscopy cameras. These procedures reduce patient trauma, shorten hospital stays, and lower overall healthcare costs, prompting hospitals and surgical centers to expand endoscopic capabilities. Increased adoption in gastrointestinal, laparoscopic, urological, and gynecological procedures fuels consistent equipment upgrades. Advancements in camera resolution, color accuracy, and depth perception further enhance clinical confidence, encouraging surgeons to rely more heavily on endoscopic visualization across routine and complex interventions.
- For instance, Leica Microsystems (part of the Danaher Corporation, specializing in life science and medical technology) leverages high-performance apochromatic lens systems in its surgical microscopes, which are capable of resolving fine details. These systems are often paired with modern digital camera modules that support native 4K output at 60 frames per second for high-definition visualization in operating rooms.
Technological Advancements in Imaging Systems
Continuous innovation in imaging technologies significantly accelerates endoscopy camera adoption. High-definition and ultra-high-definition cameras deliver improved tissue differentiation, enabling more accurate diagnosis and precise surgical navigation. Integration of features such as enhanced contrast imaging, digital zoom, and real-time image processing improves clinical outcomes. Compatibility with visualization systems and data management platforms also supports seamless workflow integration, making advanced endoscopy cameras a strategic investment for healthcare providers seeking efficiency and diagnostic accuracy.
- For instance, Canon Inc. has developed medical CMOS sensors capable of delivering native 4K resolution at 60 frames per second, supported by on-chip noise reduction that achieves signal-to-noise ratios above 60 dB.
Growing Burden of Gastrointestinal and Chronic Diseases
The rising prevalence of gastrointestinal disorders, cancer, and age-related chronic conditions increases demand for diagnostic and therapeutic endoscopy. Early disease detection through routine screening programs expands the utilization of endoscopic procedures globally. As healthcare systems emphasize preventive care and early diagnosis, endoscopy cameras play a central role in screening, biopsy, and monitoring applications. This sustained clinical need supports long-term market growth across both developed and emerging healthcare economies.
Key Trends & Opportunities
Shift Toward 4K and Advanced Visualization Platforms
Healthcare providers increasingly adopt 4K and advanced visualization technologies to improve diagnostic precision and procedural safety. Enhanced image clarity, wider color gamut, and superior contrast support better identification of subtle lesions. This trend creates opportunities for manufacturers to differentiate products through superior optics, sensor technology, and software-driven image enhancement, particularly in high-volume surgical and diagnostic centers.
- For instance, Ricoh Imaging’s legacy APS-C-format CMOS sensors, featured in highly regarded products such as the original GR and GR II series cameras, delivered approximately 16.2 effective megapixels.
Integration with Digital and AI-Enabled Ecosystems
The integration of endoscopy cameras with digital platforms and emerging AI tools represents a key growth opportunity. Connectivity with hospital information systems enables image archiving, procedure documentation, and remote consultation. AI-assisted visualization supports real-time detection and classification of abnormalities, improving diagnostic confidence. These developments position endoscopy cameras as intelligent clinical tools rather than standalone imaging devices.
- For instance, Fujifilm launched its next-generation ELUXEO 8000 platform supports native 4K resolution (3840 × 2160 pixels) across compatible endoscopes and incorporates proprietary triple noise reduction (3NR) processing to suppress visual artifacts during dynamic procedures, as documented in the company’s October 2025 product release.
Expansion in Ambulatory and Outpatient Settings
The rapid growth of ambulatory surgical centers and outpatient clinics creates new demand for compact, cost-effective endoscopy camera systems. These facilities prioritize efficient workflows, portability, and fast turnaround times. Manufacturers offering modular, user-friendly camera solutions tailored to outpatient environments gain competitive advantage as care delivery increasingly shifts away from traditional hospital settings.
Key Challenges
High Capital Costs and Budget Constraints
Advanced endoscopy camera systems involve substantial upfront investment, limiting adoption among smaller healthcare facilities and cost-sensitive regions. Budget constraints can delay equipment upgrades, especially when existing systems remain functional. Additional costs related to maintenance, accessories, and integration with visualization platforms further increase total ownership expenses, posing a challenge to broader market penetration.
Complexity of Integration and User Training
Integrating new endoscopy cameras into existing clinical workflows can be complex, particularly in facilities with legacy systems. Compatibility issues, software integration, and staff training requirements may slow adoption. Ensuring consistent image quality and proper handling also demands skilled personnel, making training and standardization critical challenges for healthcare providers implementing advanced endoscopic imaging solutions.
Regional Analysis
North America
North America dominates the endoscopy cameras market, accounting for approximately 38% market share, supported by advanced healthcare infrastructure, high procedural volumes, and early adoption of minimally invasive surgeries. Strong demand from hospitals and ambulatory surgical centers drives continuous upgrades to high-definition and 4K endoscopy systems. Favorable reimbursement frameworks, widespread physician training, and rapid integration of digital imaging technologies further support market leadership. The region also benefits from high investment in R&D, faster regulatory approvals for advanced imaging platforms, and strong penetration of AI-enabled visualization tools that enhance diagnostic precision and workflow efficiency.
Europe
Europe holds an estimated 31% market share in the endoscopy cameras market, driven by strong adoption of minimally invasive procedures across gastrointestinal, urology, and gynecology applications. Countries such as Germany, France, and the UK lead demand due to well-established public healthcare systems and increasing surgical volumes linked to aging populations. Strict regulatory standards promote the adoption of high-quality, compliant imaging systems, while rising investments in hospital modernization support steady equipment replacement cycles. Growing focus on early disease detection and improved clinical outcomes further strengthens regional demand.
Asia-Pacific
Asia-Pacific accounts for around 23% market share and represents the fastest-growing regional market. Expansion is supported by rapidly improving healthcare infrastructure, rising healthcare expenditure, and increasing adoption of minimally invasive procedures in countries such as China, Japan, India, and South Korea. Large patient populations, growing awareness of early diagnosis, and government investments in hospital capacity drive demand for cost-effective yet high-performance endoscopy cameras. The region also benefits from expanding medical tourism and increasing installation of advanced visualization systems in both public and private healthcare facilities.
Latin America
Latin America holds nearly 5% market share, with growth supported by gradual improvements in healthcare infrastructure and increasing adoption of endoscopic procedures in Brazil, Mexico, and Argentina. Rising prevalence of gastrointestinal disorders and expanding access to diagnostic services contribute to steady demand. Private hospitals and specialty clinics play a key role in technology adoption, particularly for high-definition imaging systems. However, budget constraints and uneven access to advanced medical equipment across countries limit faster market expansion, keeping growth moderate compared to developed regions.
Middle East & Africa
The Middle East & Africa region accounts for approximately 3% market share, driven primarily by healthcare investments in the Gulf Cooperation Council countries. Expansion of advanced hospitals, rising medical tourism, and increasing focus on minimally invasive surgery support demand for endoscopy cameras. In contrast, limited healthcare funding and infrastructure challenges in parts of Africa restrain broader market penetration. Nonetheless, government-led healthcare modernization initiatives and growing private-sector participation are gradually improving access to advanced endoscopic imaging technologies across the region.
Endoscopy Cameras Market Segmentations:
By Product:
- Visualization systems
- Endoscopic ultrasound
By Application:
- Gastroscopy
- Colonoscopy
By End User:
- Hospitals
- Ambulatory surgical centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the endoscopy cameras market players such as SIGMA CORPORATION, Panasonic Corporation, Leica Camera AG, Canon Inc., RICOH IMAGING COMPANY, LTD., FUJIFILM Holdings Corporation, OM Digital Solutions Corporation, Nikon Corporation, Eastman Kodak Company, Olympus Corporation. the endoscopy cameras market is characterized by intense competition driven by rapid technological innovation, strict regulatory requirements, and increasing demand for high-precision minimally invasive procedures. Market participants compete primarily on image quality, optical accuracy, sensor sensitivity, and real-time visualization capabilities that support improved clinical outcomes. Continuous advancements in high-definition and ultra-high-definition imaging, enhanced color fidelity, and low-light performance strengthen product differentiation. Companies also focus on integrating endoscopy cameras with complete visualization platforms, digital image management systems, and AI-enabled enhancement tools to improve procedural efficiency and diagnostic confidence. Strong investments in research and development, compliance with international medical standards, and robust after-sales support services play a critical role in maintaining competitiveness. Additionally, global distribution reach, long-term relationships with healthcare providers, and the ability to deliver reliable, ergonomically designed solutions remain key factors shaping competitive positioning in the market.
Key Player Analysis
- SIGMA CORPORATION
- Panasonic Corporation
- Leica Camera AG
- Canon Inc.
- RICOH IMAGING COMPANY, LTD.
- FUJIFILM Holdings Corporation
- OM Digital Solutions Corporation
- Nikon Corporation
- Eastman Kodak Company
- Olympus Corporation
Recent Developments
- In July 2024, Leica Camera AG launched the Leica D-Lux 8 compact camera on emphasizing user-friendliness, intuitive controls, an optimized layout, and seamless Leica FOTOS app connectivity, featuring a 4/3" sensor, fast lens, and DNG/JPEG support, designed to be a stylish, accessible tool for photography.
- In April 2024, Ambu A/S confirmed receiving US Food and Drug Administration (FDA) 510(k) clearance for their next-generation sterile, single-use duodenoscopy system, the aScope Duodeno 2 and aBox 2, intended for use in complex Endoscopic Retrograde Cholangiopancreatography (ERCP) procedures, aiming to enhance safety, performance, and address reprocessing challenges.
- In November 2023, Olympus Corporation (Olympus), launched EVIS X1, its next-generation endoscopy system in China. This endoscopy system has been demonstrated at the 6th annual China International Import Expo that was held in Shanghai from November 5th -10th.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of 4K and ultra-high-definition endoscopy cameras will accelerate as healthcare providers prioritize enhanced visualization and diagnostic accuracy.
- Integration of artificial intelligence for real-time image enhancement and lesion detection will increasingly support clinical decision-making.
- Demand for minimally invasive procedures will continue to expand across gastrointestinal, urology, gynecology, and pulmonary applications.
- Hospitals and ambulatory surgical centers will invest in ergonomic and lightweight camera systems to improve surgeon comfort and workflow efficiency.
- Growing emphasis on early disease detection will drive replacement of legacy imaging systems with advanced digital platforms.
- Emerging economies will witness higher adoption due to expanding healthcare infrastructure and rising procedural volumes.
- Compatibility with integrated visualization and data management systems will become a key purchasing criterion.
- Manufacturers will focus on improving low-light performance and color accuracy to enhance clinical outcomes.
- Regulatory compliance and quality certifications will play an increasing role in purchasing decisions.
- Strategic collaborations between technology providers and healthcare institutions will strengthen innovation and market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Endoscopy Cameras Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Endoscopy Cameras Market projected to grow between 2024 and 2032?
Which Endoscopy Cameras Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Endoscopy Cameras Market?
Who are the leading companies in the Endoscopy Cameras Market?
Which region commanded the largest share of the Endoscopy Cameras Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Endoscopy Cameras Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Endoscopy Cameras Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,107 million → 2032: USD 6,236.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Endoscopy Cameras Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Endoscopy Cameras Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Endoscopy Cameras Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Endoscopy Cameras Market Drivers
- 3.3 Endoscopy Cameras Market Restraints & Challenges
- 3.4 Endoscopy Cameras Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Endoscopy Cameras Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Endoscopy Cameras Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Endoscopy Cameras category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Endoscopy Cameras Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Endoscopy Cameras Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Endoscopy Cameras market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Endoscopy Cameras Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Endoscopy Cameras Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Endoscopy Cameras Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Endoscopy Cameras (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Endoscopy Cameras Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Endoscopy Cameras Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Endoscopy Cameras Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Endoscopy Cameras Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Endoscopy Cameras Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Endoscopy Cameras Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Endoscopy Cameras Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Endoscopy Cameras Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Endoscopy Cameras Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
