
Market Overview
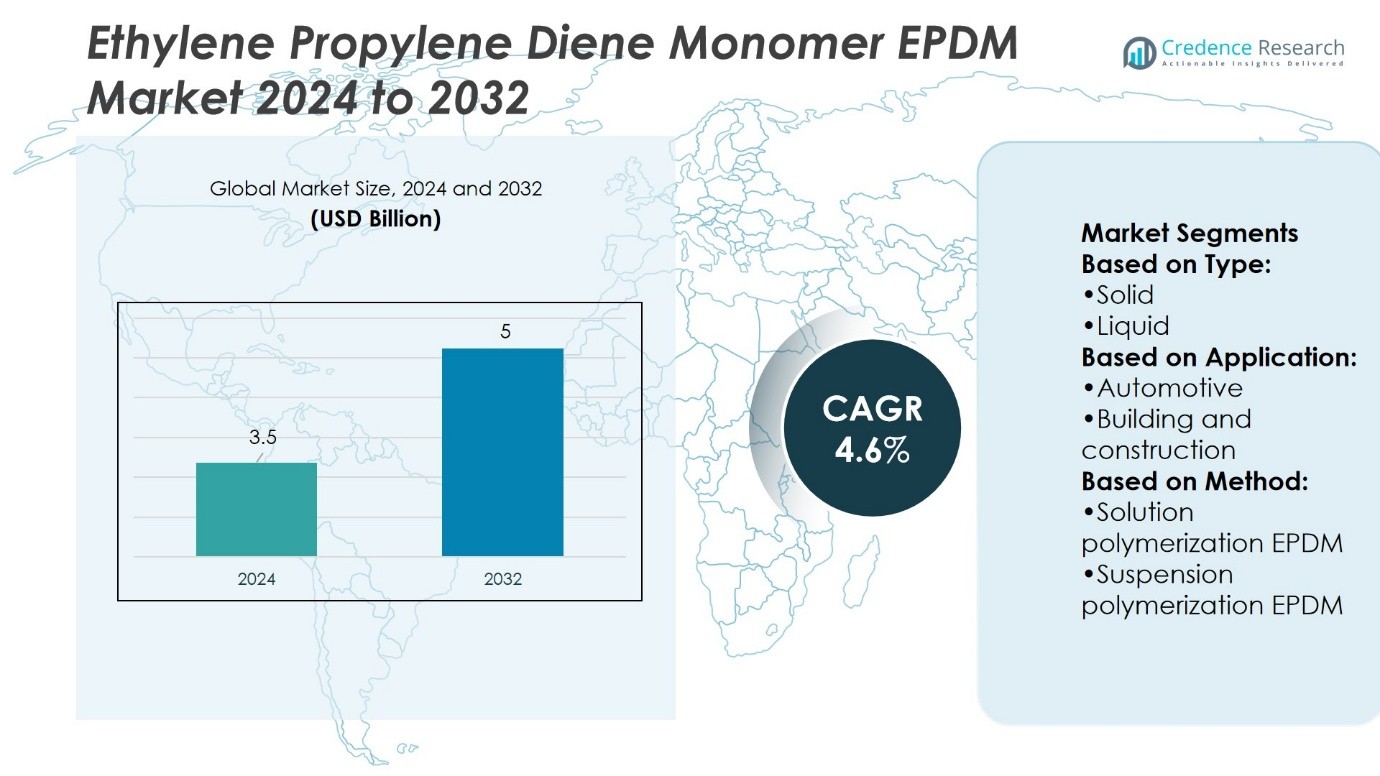
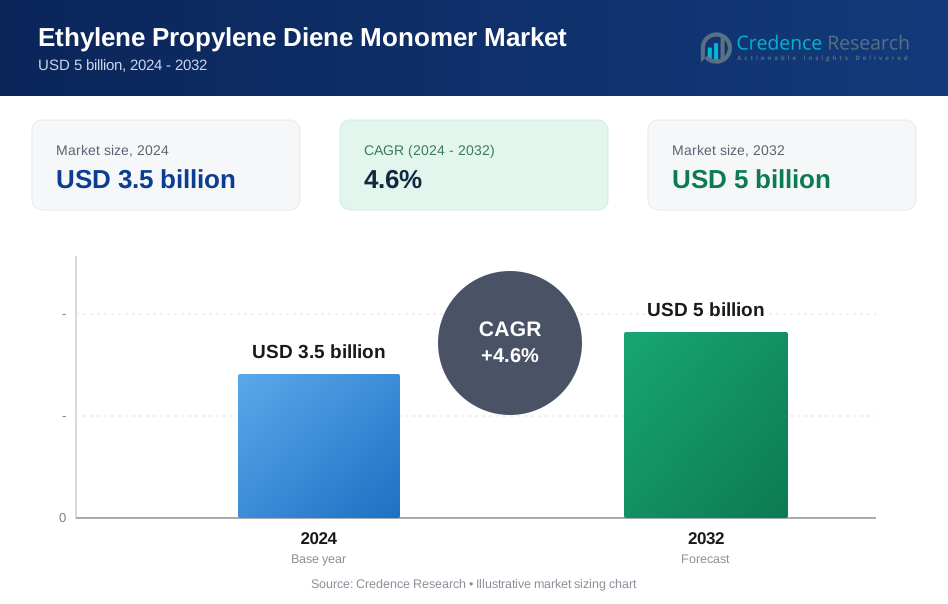
Ethylene Propylene Diene Monomer (EPDM) Market size was valued at USD 3.5 billion in 2024 and is anticipated to reach USD 5 billion by 2032, at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Ethylene Propylene Diene Monomer (EPDM) Market Size 2024 | USD 3.5 Billion |
| Ethylene Propylene Diene Monomer (EPDM) Market , CAGR | 4.6% |
| Ethylene Propylene Diene Monomer (EPDM) Market Size 2032 | USD 5 Billion |
The Ethylene Propylene Diene Monomer (EPDM) Market grows with strong demand from automotive, construction, and industrial sectors. It supports vehicle durability through heat- and ozone-resistant sealing systems and extends building lifespans with long-lasting roofing membranes. Rising investments in electric vehicles create opportunities for EPDM use in battery pack insulation and thermal management. Green construction initiatives strengthen adoption of recyclable and eco-friendly formulations. Innovation in polymerization methods enhances product consistency and performance. Industrial expansion in emerging economies fuels wider applications in hoses, gaskets, and molded goods. Sustainability and durability trends ensure continuous growth across global end-use industries.
North America holds a strong share of the Ethylene Propylene Diene Monomer EPDM Market driven by automotive and construction demand, while Europe advances with sustainability-focused applications in roofing and industrial systems. Asia-Pacific leads growth through rapid industrialization, infrastructure expansion, and rising EV production. Latin America and Middle East & Africa show steady adoption supported by construction and energy projects. Key players shaping the market include Exxon Mobil Corporation, ARLANXEO, Mitsui Chemicals, Lion Elastomers, and KUMHO POLYCHEM.
Market Insights
- Ethylene Propylene Diene Monomer EPDM Market size was valued at USD 3.5 billion in 2024 and is expected to reach USD 5 billion by 2032, at a CAGR of 4.6%.
- Demand is driven by automotive, construction, and industrial sectors seeking durable sealing and insulation solutions.
- Market trends highlight adoption in electric vehicles, roofing membranes, and recyclable eco-friendly formulations.
- Competition remains strong with leading producers focusing on innovation, polymerization methods, and sustainability-driven product development.
- Restraints include raw material price volatility and growing substitution threats from thermoplastic elastomers.
- North America and Europe show steady demand, while Asia-Pacific leads growth supported by industrialization and EV expansion.
- Latin America and Middle East & Africa contribute with construction, energy, and infrastructure projects reinforcing market stability.
Market Drivers
Growing Demand in Automotive Sealing Systems and Components
The Ethylene Propylene Diene Monomer EPDM Market grows with rising demand for advanced automotive sealing systems. Automakers rely on EPDM for weatherstrips, hoses, and gaskets due to its superior resistance to heat, ozone, and weathering. It enhances vehicle durability while supporting weight reduction strategies in lightweight designs. Strong growth in electric vehicles further expands opportunities for EPDM applications in high-performance insulation and cooling systems. Its ability to withstand temperatures up to 150°C supports long service life. Stringent safety and efficiency standards reinforce demand across global automotive production.
- For instance, Lion Elastomers supplies Royaltherm® 1411A, a silicone-modified EPDM elastomer with a Shore A hardness of 30–40 after curing. Royaltherm is utilized in automotive applications, such as under-hood hose insulation, due to its enhanced resistance to heat and ozone compared to standard EPDM.
Expansion in Construction and Roofing Applications
Construction activities across commercial and residential sectors drive steady use of EPDM in roofing and waterproofing solutions. The material’s durability and low maintenance requirements make it an attractive choice for sustainable building projects. It delivers flexibility and maintains performance under extreme weather cycles, including freezing and high solar radiation. Adoption strengthens through energy-efficient roofing systems that extend lifespans beyond 30 years. Increasing investments in urban infrastructure projects further boost consumption. The emphasis on long-lasting and eco-friendly materials positions EPDM strongly within modern construction practices.
- For instance, Kumho Polychem boosted EPDM production to 310,000 MT per year with its 2024 plant expansion using ultralow‑temperature polymerization, enhancing its ability to supply roofing membranes with long lifespans.
Rising Adoption in Industrial and Mechanical Applications
The industrial sector demonstrates strong uptake of EPDM for hoses, conveyor belts, and seals. Its resistance to water, acids, and alkalis ensures reliable performance across diverse operating conditions. EPDM supports machinery efficiency and reduces downtime in demanding environments such as chemical plants and power generation. It withstands repeated compression without cracking, enhancing safety and longevity in sealing systems. Industrial expansion in emerging economies contributes to wider use of the material. Continuous replacement of outdated materials with EPDM reinforces its role in critical operations.
Increased Focus on Sustainability and Eco-Friendly Materials
Sustainability trends strengthen EPDM adoption in industries aiming to lower environmental impact. It is recyclable and compatible with eco-friendly manufacturing practices, aligning with stricter environmental regulations. Green building initiatives support wider use of EPDM membranes in energy-efficient designs. In the automotive sector, it reduces reliance on non-durable polymers by extending part lifespans. Research advances highlight bio-based formulations, further positioning EPDM as a future-ready solution. Rising awareness of eco-compliance reinforces its adoption in both developed and developing regions.
Market Trends
Increasing Use in Energy-Efficient Building and Roofing Solutions
The Ethylene Propylene Diene Monomer EPDM Market shows a clear trend toward energy-efficient building practices. EPDM membranes are widely adopted in cool roofing systems designed to reduce urban heat effects. It provides long-term weather resistance, making it ideal for large commercial structures and sustainable housing projects. Demand strengthens in regions implementing green building codes and energy efficiency mandates. Adoption of prefabricated EPDM sheets supports faster installation while minimizing labor costs. This focus on durability and efficiency enhances its importance in construction markets.
- For instance, ExxonMobil's Vistalon™ 9301 EPDM, a rubber compound well-suited for sheeting goods like roofing membranes, features a Shore A hardness of 65 in a typical roofing formulation. Known for its weather resistance, it can be processed efficiently for high-speed extrusion.
Advancements in Automotive Lightweighting and Electrification
Automotive trends emphasize lighter materials and reliable thermal performance, boosting demand for EPDM components. It supports efficient sealing in battery systems and charging infrastructure within electric vehicles. EPDM’s flexibility at temperatures as low as -40°C secures consistent performance in harsh conditions. Automakers increasingly select EPDM for lightweight designs that extend driving range. Its durability reduces replacement frequency, aligning with cost and sustainability goals. Growth in global EV production reinforces long-term prospects for EPDM in transportation.
- For instance, ARLANXEO’s high‑Mooney EPDM grade Keltan 13951C DE features a Mooney viscosity of 92 MU (measured at 150 °C with ML (1+8)) and contains 44 wt % ethylene and 9 wt % ENB diene units, which are specifications used to determine processing.
Rising Demand in Renewable Energy and Industrial Expansion
EPDM demonstrates growing relevance in renewable energy applications, including sealing solutions for wind turbines and solar panels. It provides resistance against UV radiation and ozone, critical for outdoor equipment reliability. Industrial facilities adopt EPDM for hoses and gaskets exposed to aggressive chemicals. It supports operations in sectors requiring robust materials for high-stress environments. Emerging economies with expanding manufacturing bases contribute to wider adoption. This shift highlights EPDM’s adaptability across industrial and renewable energy domains.
Innovation in Bio-Based and Sustainable Formulations
Innovation trends show strong focus on bio-based EPDM to reduce dependence on petrochemicals. Research advances lead to formulations that maintain performance while lowering carbon impact. It strengthens adoption among manufacturers seeking compliance with international sustainability frameworks. Interest in closed-loop recycling initiatives is expanding within the polymer industry. Companies invest in new production technologies that improve efficiency and reduce emissions. These sustainability-driven innovations position EPDM as a material aligned with long-term environmental goals.
Market Challenges Analysis
Volatility in Raw Material Supply and Pricing Pressure
The Ethylene Propylene Diene Monomer EPDM Market faces challenges from fluctuations in raw material availability. EPDM production depends heavily on petroleum-based feedstocks, making it vulnerable to crude oil supply disruptions. It also contends with global trade uncertainties that impact the cost of ethylene, propylene, and diene. Price volatility often creates unpredictability for manufacturers and limits long-term planning. High energy costs in production further add to margin pressures. These conditions make supply chain management a critical concern for producers and end users.
Environmental Regulations and Substitution Threats
Stringent environmental regulations create barriers for EPDM manufacturers across global markets. Compliance with emission standards and disposal requirements often demands costly process upgrades. It faces growing competition from thermoplastic elastomers that provide recyclability and lower environmental impact. Shifts in customer preferences toward sustainable materials intensify this substitution risk. Limited awareness in developing markets also restricts the pace of adoption. Addressing regulatory compliance while competing with alternative materials remains a persistent challenge for the industry.
Market Opportunities
Expanding Role in Sustainable Construction and Green Infrastructure
The Ethylene Propylene Diene Monomer EPDM Market holds strong opportunities in sustainable building applications. EPDM membranes provide long-lasting waterproofing in energy-efficient roofing systems and green infrastructure projects. It supports reduced maintenance and extended service life, aligning with eco-friendly construction standards. Growing investment in smart cities creates demand for durable roofing and sealing materials. EPDM’s recyclability enhances its appeal in regions adopting circular economy principles. Rising focus on energy conservation reinforces its position as a preferred construction material.
Growing Use in Electric Vehicles and Renewable Energy Systems
Global electrification trends create new growth prospects for EPDM in automotive and energy sectors. It ensures performance in battery pack sealing, charging infrastructure, and thermal management systems. Its low-temperature flexibility and high heat resistance strengthen adoption in electric mobility solutions. Renewable energy projects also require EPDM for sealing wind turbines, solar panel frames, and protective cabling. Rising investments in EV production and clean energy expansion support wider use of EPDM. These opportunities highlight its relevance in next-generation transportation and power infrastructure.
Market Segmentation Analysis:
By Type
The Ethylene Propylene Diene Monomer EPDM Market is segmented into solid, liquid, and granules. Solid EPDM dominates use across sealing, roofing, and industrial components due to durability and flexibility. It supports large-scale applications requiring long service life under extreme weather. Liquid EPDM finds opportunities in coatings, adhesives, and waterproof membranes where direct application provides faster installation. Granules are increasingly adopted in flooring, playgrounds, and sports surfaces due to impact resistance and safety. The variation in types ensures tailored solutions across automotive, construction, and specialty industries.
- For instance, Elevate’s RubberGard EPDM single-ply membranes come in multiple thickness options: the internally‐reinforced MAX series is available in 45 mil (1.1 mm), 60 mil (1.5 mm), or 75 mil (1.9 mm) thicknesses.
By Application
EPDM serves critical roles in automotive, building and construction, molded goods, lubricant additives, and other industrial uses. Automotive applications lead with extensive demand for hoses, seals, and weatherstrips, where it provides ozone and heat resistance. Building and construction rely on EPDM membranes for roofing, window gaskets, and insulation that perform across decades of exposure. Molded goods such as gaskets, O-rings, and belts reinforce its importance in heavy machinery and consumer products. Lubricant additives use EPDM for viscosity improvement and stability in mechanical systems. It continues to expand in diverse industrial uses such as cable insulation and water systems.
- For instance, Sumitomo Chemical offers its Esprene 670F EPDM grade, which has a Mooney viscosity of 165 (ML 1+4 at 125 °C) and contains 66 wt% ethylene and 4.0 wt% diene. This high-viscosity grade is suitable for manufacturing high specific-gravity EPDM compositions used in various automotive and industrial molded products.
By Method
The market is also segmented by solution polymerization, suspension polymerization, and gas-phase polymerization EPDM. Solution polymerization remains widely adopted due to its ability to produce high-performance grades with uniform molecular distribution. It supports applications where precise properties are required, including automotive seals and roofing systems. Suspension polymerization offers cost-effective production and flexibility for multiple end uses. Gas-phase polymerization demonstrates efficiency in large-scale operations while reducing process complexity. It creates opportunities for tailored molecular structures that align with specialized applications. Advances in these methods ensure consistent quality and innovation across industries adopting EPDM.
Segments:
Based on Type:
- Solid
- Liquid
Based on Application:
- Automotive
- Building and construction
Based on Method:
- Solution polymerization EPDM
- Suspension polymerization EPDM
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America accounts for around 29% share of the Ethylene Propylene Diene Monomer EPDM Market. The region benefits from a mature automotive industry, with significant EPDM use in sealing systems, hoses, and weatherstrips. It also holds strong demand from the construction sector, where EPDM roofing membranes dominate sustainable and energy-efficient building designs. Investments in electric vehicles and charging infrastructure further support wider adoption. The United States leads the regional market with high production capabilities and a strong presence of multinational manufacturers. Canada contributes with demand from infrastructure and industrial projects that emphasize long-term material performance. Regulatory support for energy-efficient construction secures steady opportunities for EPDM expansion.
Europe
Europe holds a 27% share of the Ethylene Propylene Diene Monomer EPDM Market. The region shows strong growth through construction projects, automotive production, and renewable energy expansion. EPDM is widely used in roofing systems across Germany, the UK, and France, where strict environmental codes demand durable and recyclable materials. Automotive producers in Germany and Italy drive consistent demand for high-performance sealing applications. Europe also supports research into bio-based EPDM, aligning with sustainability goals and carbon reduction policies. The presence of large-scale producers ensures local supply and innovation in specialty EPDM grades. Market adoption is reinforced by government policies promoting green infrastructure and recycling initiatives.
Asia-Pacific
Asia-Pacific contributes the largest share at 32% of the Ethylene Propylene Diene Monomer EPDM Market. The region is supported by rapid industrialization, infrastructure development, and automotive expansion. China and India lead with strong demand for EPDM membranes in roofing and water systems used in smart city projects. Japan and South Korea drive innovation in automotive EPDM applications, particularly in electric vehicles. Construction growth across Southeast Asia creates further opportunities for roofing and insulation products. Availability of cost-effective manufacturing strengthens the regional supply chain, making Asia-Pacific a hub for exports. Government initiatives focused on renewable energy also boost EPDM demand in turbine and solar equipment applications.
Latin America
Latin America holds about 7% share of the Ethylene Propylene Diene Monomer EPDM Market. The region demonstrates growing adoption in construction projects, particularly in commercial roofing and insulation systems. Brazil and Mexico lead demand with strong automotive production and industrial activities. EPDM is increasingly applied in sealing systems for oil and gas operations, where durability under harsh conditions is required. Urban development programs expand opportunities for waterproofing and roofing materials. The region also benefits from gradual adoption of energy-efficient building standards. Limited local production capacity creates reliance on imports, though demand remains steady across diverse end-use sectors.
Middle East & Africa
The Middle East & Africa represent a 5% share of the Ethylene Propylene Diene Monomer EPDM Market. Infrastructure expansion, oil and gas projects, and industrial investments shape regional consumption. EPDM materials are adopted for sealing systems in pipelines, refineries, and construction under extreme heat conditions. The UAE and Saudi Arabia drive demand through large-scale infrastructure and smart city projects. South Africa contributes with adoption in automotive components and commercial roofing. Growing awareness of sustainable building practices supports wider use of EPDM boards and membranes. Although the region remains smaller compared to others, long-term opportunities are tied to ongoing industrialization and energy diversification strategies.
Key Player Analysis
- Lion Elastomers
- KUMHO POLYCHEM
- Exxon Mobil Corporation
- PetroChina Company Limited
- ARLANXEO
- Mitsui Chemicals, Inc.
- Elevate (HOLCIM)
- Rubber Engineering & Development Company (REDCO)
- Sumitomo Chemical Co., Ltd.
- Johns Manville
Competitive Analysis
The Ethylene Propylene Diene Monomer EPDM Market include Lion Elastomers, KUMHO POLYCHEM, Exxon Mobil Corporation, PetroChina Company Limited, ARLANXEO, Mitsui Chemicals, Inc., Elevate (HOLCIM), Rubber Engineering & Development Company (REDCO), Sumitomo Chemical Co., Ltd., and Johns Manville. The Ethylene Propylene Diene Monomer EPDM Market is defined by strong competition across global and regional manufacturers. Companies focus on expanding production capacity and developing high-performance grades tailored to automotive, construction, and industrial applications. Innovation plays a central role, with research emphasizing improved resistance to heat, ozone, and environmental stressors. Producers invest in bio-based and recyclable formulations to align with sustainability goals and meet tightening environmental regulations. Roofing membranes, automotive seals, and molded components remain priority segments, driving specialized product development and differentiation. Competitive advantage often depends on the ability to maintain reliable supply chains, manage raw material volatility, and deliver cost-effective solutions without compromising quality. Many producers strengthen their positions through partnerships, licensing agreements, and localized production strategies that reduce logistical challenges. The market also sees rising interest in advanced polymerization methods, ensuring flexibility in molecular design and consistency in performance.
Recent Developments
- In August 2025, ARLANXEO launched ISCC PLUS-certified Keltan Eco-B and Eco-BC grades in India, offering bio-based EPDM alternatives with identical performance to conventional rubbers.
- In May 2024, KRAIBURG TPE launched newly developed EPDM adhesion compounds, primarily designed for automotive sealing applications. Equipped with a formulation suitable for exterior automotive parts, UV resistance capabilities, and other key features, this portfolio is expected to strengthen KRAIBURG TPE’s market position in the automotive sealing and adhesion sector.
- In February 2024, Emulco NV collaborated with Lion Elastomers, liquid-EPDM (L-EPDM) polymers, and Ethylene Propylene Diene Monomer (EPDM) rubber provider. Two have signed a supply contract linked with the use of Trilene 65 L-EPDM, a component for Emulco's water-based EPDM dispersion product.
- In November 2023, Borealis AG closed a deal to acquire Rialti, a recycled polypropylene compound producer, to boost its portfolio of PP compounds based on mechanical recyclates by 50,000 tons annually.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Method and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for EPDM will expand with growth in electric vehicles and charging infrastructure.
- Roofing and waterproofing applications will remain central in sustainable construction projects.
- Bio-based EPDM grades will gain traction under stricter environmental regulations.
- Industrial growth in Asia-Pacific will drive higher adoption across multiple applications.
- Advanced polymerization methods will support production of consistent and high-performance grades.
- Recycling initiatives will shape product development and strengthen eco-friendly positioning.
- Renewable energy projects will increase use of EPDM in wind and solar equipment.
- Automotive lightweighting trends will boost demand for durable and flexible sealing systems.
- Regional players will focus on localized supply to reduce logistics and cost challenges.
- Research investments will create innovative formulations for niche industrial and aerospace uses.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automotive Sealing Systems and Electrification
Automakers increasingly use EPDM for weatherstrips, hoses, and gaskets due to its superior resistance to heat, ozone, and weathering, supporting both traditional and electric vehicle production. The material's durability and ability to withstand high temperatures make it essential for advanced automotive sealing and insulation, especially as EV adoption rises.
Expansion in Construction and Roofing Applications
EPDM's long lifespan, flexibility, and weather resistance drive its use in roofing membranes and waterproofing solutions for commercial and residential buildings. The push for sustainable and energy-efficient construction further boosts demand for EPDM in green building projects.
Industrial and Mechanical Application Growth
Industrial sectors adopt EPDM for hoses, conveyor belts, and seals due to its resistance to water, acids, and alkalis, ensuring reliable performance in harsh environments. Industrial expansion in emerging economies is widening the scope of EPDM applications in machinery and infrastructure.
Sustainability and Eco-Friendly Formulations
Growing environmental regulations and green building initiatives are increasing the adoption of recyclable and bio-based EPDM formulations. Manufacturers are innovating to offer eco-friendly products that align with global sustainability goals, enhancing EPDM's market position.
Innovation in Polymerization Methods
Advancements in solution, suspension, and gas-phase polymerization are enabling the production of EPDM grades with improved consistency, performance, and tailored properties. These innovations support the development of high-performance products for specialized automotive, construction, and industrial uses.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Ethylene Propylene Diene Monomer EPDM Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Ethylene Propylene Diene Monomer EPDM Market projected to grow between 2025 and 2032?
Which Ethylene Propylene Diene Monomer EPDM Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Ethylene Propylene Diene Monomer EPDM Market?
Who are the leading companies in the Ethylene Propylene Diene Monomer EPDM Market?
Which region commanded the largest share of the Ethylene Propylene Diene Monomer EPDM Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Solid
- 1.2.2 Liquid
- 1.2.3 Granules
- 1.3 By Method
- 1.3.1 Solution Polymerization EPDM
- 1.3.2 Suspension Polymerization EPDM
- 1.3.3 Gas-Phase Polymerization EPDM
- 1.4 By Application
- 1.4.1 Automotive
- 1.4.2 Building and Construction
- 1.4.3 Molded Goods
- 1.4.4 Lubricant Additives
- 1.4.5 Industrial Uses
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.5 billion → 2032: USD 5 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ethylene Propylene Diene Monomer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ethylene Propylene Diene Monomer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ethylene Propylene Diene Monomer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ethylene Propylene Diene Monomer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ethylene Propylene Diene Monomer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ethylene Propylene Diene Monomer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ethylene Propylene Diene Monomer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ethylene Propylene Diene Monomer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.5 billion → 2032: USD 5 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ethylene Propylene Diene Monomer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solid
- 12.3.7.2 Liquid
- 12.3.7.3 Granules
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Method - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solution Polymerization EPDM
- 12.4.7.2 Suspension Polymerization EPDM
- 12.4.7.3 Gas-Phase Polymerization EPDM
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Building and Construction
- 12.5.7.3 Molded Goods
- 12.5.7.4 Lubricant Additives
- 12.5.7.5 Industrial Uses
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ethylene Propylene Diene Monomer End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Ethylene Propylene Diene Monomer Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Ethylene Propylene Diene Monomer Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Ethylene Propylene Diene Monomer Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Exxon Mobil Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ARLANXEO
- 18.4 KUMHO POLYCHEM
- 18.5 Lion Elastomers
- 18.6 Mitsui Chemicals, Inc.
- 18.7 PetroChina Company Limited
- 18.8 Elevate (HOLCIM)
- 18.9 Sumitomo Chemical Co., Ltd.
- 18.10 Johns Manville
- 18.11 Rubber Engineering & Development Company (REDCO)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

