
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Europe Iron Supplements Market Size 2023 | USD 645.19 Million |
| Europe Iron Supplements Market, CAGR | 5.65% |
| Europe Iron Supplements Market Size 2032 | USD 1,058.07 Million |
Market Overview
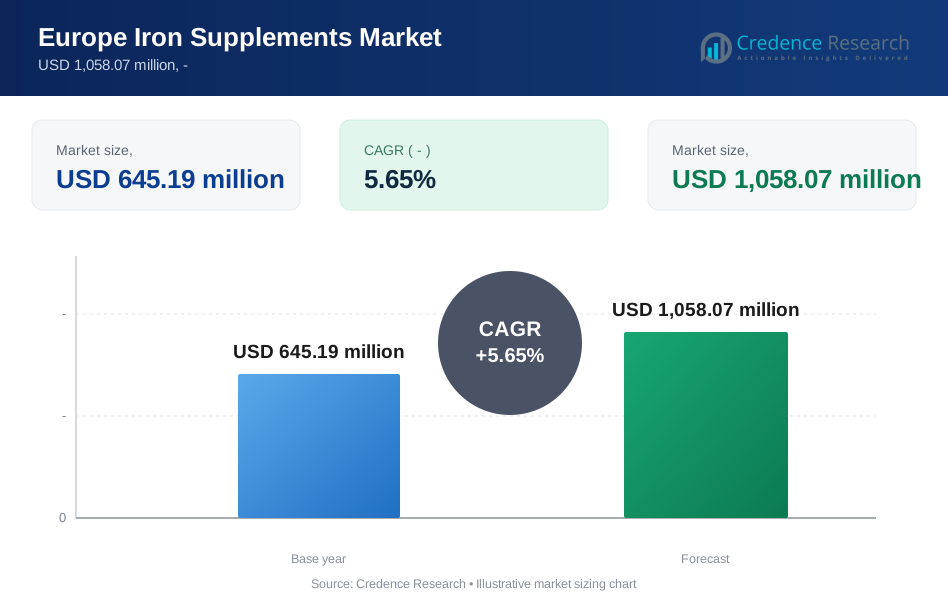
The Europe Iron Supplements market is projected to grow from USD 645.19 million in 2023 to USD 1,058.07 million by 2032, at a Compound Annual Growth Rate (CAGR) of 5.65%.
The Europe Iron Supplements market is a crucial segment within the broader nutritional supplement industry, addressing a widespread need for iron supplementation among various demographic groups. Iron is an essential mineral vital for producing hemoglobin, a protein in red blood cells that carries oxygen from the lungs to the rest of the body. Iron deficiency is a common nutritional shortfall, leading to anemia and associated health issues, making iron supplements a vital health intervention.
The market for iron supplements in Europe has been growing steadily, driven by increasing awareness of iron deficiency anemia, an aging population, and a rise in health and wellness trends. The market encompasses a range of products, including ferrous and ferric iron salts, heme iron, and polysaccharide-iron complexes, available in various forms such as tablets, capsules, and liquid.
The market's value is in the billions, with a consistent compound annual growth rate (CAGR) that reflects the increasing demand for dietary supplements and the specific focus on addressing iron deficiency. Countries such as Germany, the United Kingdom, France, and Italy are leading consumers within the region, attributed to their larger populations, higher healthcare spending, and greater prevalence of dietary supplements.
Key Market Drivers
Increased Prevalence of Iron Deficiency Anemia
One of the primary drivers of the iron supplements market in Europe is the increasing prevalence of iron deficiency anemia among the population. Factors contributing to this condition include poor diet, chronic illnesses, menstrual bleeding, and pregnancy. The rising awareness among the general public and healthcare providers about the consequences of iron deficiency and the importance of maintaining optimal iron levels has led to increased consumption of iron supplements.
Aging Population
Europe has one of the highest proportions of aging populations globally, a demographic more susceptible to nutritional deficiencies, including iron. The aging process can lead to a decrease in dietary iron intake and absorption, making supplementation necessary to prevent anemia and other iron-deficiency-related conditions. The growing number of older adults is thus a significant factor driving the demand for iron supplements.
Growing prevalence of iron-deficiency anemia
The increasing incidence of iron deficiency anemia across Europe, fueled by factors like dietary changes, aging population, and chronic diseases, is driving the demand for effective treatment options.
Growing Popularity of Vegan and Vegetarian Diets
The increasing adoption of vegan and vegetarian lifestyles in Europe, while beneficial in many respects, often results in diets that lack sufficient iron. This deficiency highlights the need for plant-based iron supplements designed for optimal absorption. The trend towards such diets is expected to further stimulate the demand for iron supplements tailored to these dietary preferences.
Government Initiatives and Healthcare Reforms
European governments are launching initiatives aimed at enhancing public health and curtailing chronic diseases. Part of these efforts involves promoting the use of dietary supplements to address nutrient deficiencies, including iron. Moreover, healthcare reforms in certain regions are improving access to medical services, facilitating early detection and management of iron deficiency, which, in turn, boosts the market for iron supplements.
Rising awareness and early diagnosis
Growing awareness and improved diagnostic methods for iron deficiency anemia are leading to earlier detection and treatment, further propelling market growth.
Technological advancements in treatment options
Innovations in technology are fostering the development of new and improved iron supplements. Emerging delivery systems aim to enhance iron absorption, while ongoing research seeks to create iron supplements that are both more palatable and tolerable for consumers. These advancements are instrumental in meeting the evolving needs and preferences of the market.
Key Market Restraints
Side Effects and Over-supplementation
While iron supplements are essential for preventing and treating iron deficiency anemia, they can also cause side effects such as stomach pain, constipation, and nausea. These adverse effects can deter individuals from taking iron supplements. Additionally, there is a risk of iron overload from over-supplementation, especially in individuals with conditions like hemochromatosis, where iron accumulates in the body, potentially leading to serious health issues.
Strict Regulatory Framework
The European Union (EU) maintains a stringent regulatory framework for dietary supplements, including iron supplements. This rigorous approval and marketing process can pose significant barriers to entry for new products, resulting in delays and increased costs for manufacturers. The strict regulatory environment ensures product safety and efficacy but also limits market expansion and innovation to some extent.
Potential for Adverse Effects
Iron supplements, though beneficial, carry the risk of adverse effects, especially when consumed in excessive doses or by individuals without an iron deficiency. Such potential side effects can foster consumer apprehension and reluctance towards using iron supplements. Managing and communicating the risks associated with improper use are crucial in mitigating consumer concerns.
Availability of Iron from Food Sources
The natural availability of iron in various food sources can also constrain the market for iron supplements. Foods rich in iron, including red meat, poultry, fish, beans, lentils, and leafy green vegetables, provide a natural alternative to supplementation. For individuals with a balanced diet, this may reduce the perceived necessity for iron supplements, affecting market demand.
Competition from Fortified Foods
The market faces additional competition from the availability of iron-fortified foods. Products such as cereals, breakfast bars, and other fortified foods offer an alternative source of iron, potentially detracting from the demand for supplements. The convenience and accessibility of these fortified foods can appeal to consumers looking for dietary sources of iron, presenting a challenge to the iron supplement market.
Market Opportunities
- Innovative Product Formulations: Developing new formulations that minimize side effects and improve iron absorption, such as liposomal iron or slow-release formulations, can address consumer concerns and drive market growth.
- Targeted Marketing Strategies: Marketing efforts focused on high-risk groups, including women of childbearing age, pregnant women, infants, and the elderly, can increase awareness and usage of iron supplements.
- E-commerce Expansion: Strengthening online sales channels can tap into the growing trend of online shopping for health and wellness products, making it easier for consumers to access iron supplements.
- Collaboration with Healthcare Providers: Partnerships with doctors, dietitians, and other healthcare professionals to recommend iron supplementation where necessary can increase market penetration.
- Educational Campaigns: Conducting educational campaigns to raise awareness about iron deficiency symptoms, risks, and the benefits of supplementation can drive demand.
- Product Diversification: Expanding product lines to include a variety of forms (e.g., gummies, liquids) and flavors can attract a broader consumer base, including children and those who have difficulty swallowing pills.
- Sustainable and Ethical Products: Offering iron supplements that are sustainably sourced and produced, with transparent labeling about origins and manufacturing processes, can appeal to environmentally conscious consumers.
Interesting Facts About the Market
- High Prevalence in Women: Women, especially those who are pregnant or menstruating, are at a higher risk for iron deficiency, making them a significant consumer segment for iron supplements.
- Vegetarian and Vegan Trends: The rising popularity of vegetarian and vegan diets in Europe has increased the demand for iron supplements, as plant-based diets may not provide sufficient iron.
- Regulatory Standards: Europe has strict regulatory standards for dietary supplements, ensuring product safety and efficacy, which positively influences consumer trust in iron supplements.
- Customized Supplements: The trend towards personalized nutrition is growing, with opportunities for custom-tailored iron supplementation based on individual dietary needs and health conditions.
- Innovative Packaging: The use of innovative packaging that improves the shelf life and convenience of iron supplements, such as single-dose packets and child-proof containers, enhances consumer appeal.
Top Leading Players
The Europe Iron Supplements market is competitive, with several key players dominating the landscape. These include:
- Cipla
- FoodState Inc.
- Glanbia PLC
- Keryx Biopharmaceuticals Inc.
- SALUS-Haus (Floradix)
- Mission Pharmacal Company
- Mylan NV
- NOW Foods
- Rexall Sundown Inc.
- Sanofi-Aventis
- Solgar
- Strides Shasun Ltd.
- Others
Competitive Landscape
The competitive landscape in the Europe Iron Supplements market is characterized by intense competition among established players and new entrants, all vying for market share. Companies compete on the basis of product quality, innovation, pricing, and brand reputation. Strategic partnerships, research and development investments, and marketing campaigns focused on educating consumers about the importance of iron supplementation are key strategies employed by leading companies to enhance their market presence.
Segmentations:
By Type
- Heme Iron
- Non-Heme Iron
By Application
- Anemia Management
- Energy and Vitality
- Bone Health
- Additional Supplements
- Sports Nutrition
- Medical Supplements
By End-user
- General Consumers
- Athletes and Fitness Enthusiasts
- Pregnant and Nursing Women
- Seniors
- Vegetarians and Vegans
By Age Group
- Children
- Adults
- Geriatric
By Distribution Channel
- Retail Pharmacies and Drugstores
- Online Retail and E-Commerce Platforms
- Specialty Health Stores
By Form
- Tablets/Capsules
- Liquid Supplements
- Gummies
- Powders
- Others
Regional Analysis
The European iron supplements market was valued at USD 645.19 million in 2023 and is expected to grow at a CAGR of 5.6% from 2023 to 2032. Germany represents the largest market share, accounting for approximately 22% of total European sales in 2022. This can be attributed to the country's aging population and initiatives by the government to combat anemia through iron supplementation. The UK holds the second largest share at 16%, aided by substantial marketing efforts by supplement manufacturers targeting women to maintain healthy iron levels.
France, Italy, and Spain capture market shares of 13%, 12%, and 11% respectively. Growth has remained positive in these mature markets due to continued education efforts promoting iron's role in areas such as muscle function, immunity, and energy metabolism. The market remains highly fragmented across Central-Eastern European countries, with Poland and Romania showing promising expansion in recent years due to EU funding for nutrition programs and rising disposable incomes. Going forward, industry analytics predicts the iron supplements market share will remain steady in Western Europe while additional share gains will likely occur in Eastern European nations as healthcare infrastructure and patient access continues improving.
Future Outlook
- Personalized Nutrition: Continued growth in personalized nutrition will drive the development of customized iron supplementation solutions.
- Innovative Delivery Systems: Advances in delivery systems, such as chewable, liquid, and dissolvable strips, will enhance consumer compliance and expand the market.
- Regulatory Evolution: Ongoing evolution of regulatory frameworks will ensure product safety and efficacy, fostering market growth.
- Global Health Initiatives: Collaborations with global health initiatives to combat iron deficiency will increase the reach and impact of iron supplements.
- Research and Development: Continued investment in R&D will lead to more effective and consumer-friendly iron supplement products.
- Market Education: Ongoing efforts to educate the market on the importance of iron and the benefits of supplementation will drive demand.
- Technological Advancements: Leveraging technology for product innovation, such as AI to predict individual iron needs, will tailor solutions more effectively to consumer needs.
- Sustainability Focus: Increased focus on sustainability in product sourcing and packaging will appeal to environmentally conscious consumers.
- Expansion into New Markets: Exploring new geographic markets within Europe, particularly in regions with underserved populations, will drive growth.
- Integration with Digital Health: The integration of iron supplements with digital health platforms for monitoring and personalized recommendations will enhance user engagement and compliance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate for the Europe Iron Supplements market?
What are some of the key factors driving growth in the Europe Iron Supplements market?
Which European countries represent the leading consumers in the Iron Supplements market?
Who are the target demographic groups for iron supplementation in Europe?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Iron Supplements Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Iron Supplements Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 645.19 million → forecast year: USD 1,058.07 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Iron Supplements Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Iron Supplements Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Iron Supplements Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Iron Supplements Market Drivers
- 3.3 Europe Iron Supplements Market Restraints & Challenges
- 3.4 Europe Iron Supplements Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Iron Supplements Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Iron Supplements Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Iron Supplements category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Iron Supplements Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Iron Supplements Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Iron Supplements market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Iron Supplements Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Iron Supplements Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Iron Supplements Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Iron Supplements (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Iron Supplements Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Iron Supplements Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Iron Supplements Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Iron Supplements Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Iron Supplements Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Iron Supplements Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Iron Supplements Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Iron Supplements Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Iron Supplements Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
