
Market Overview:
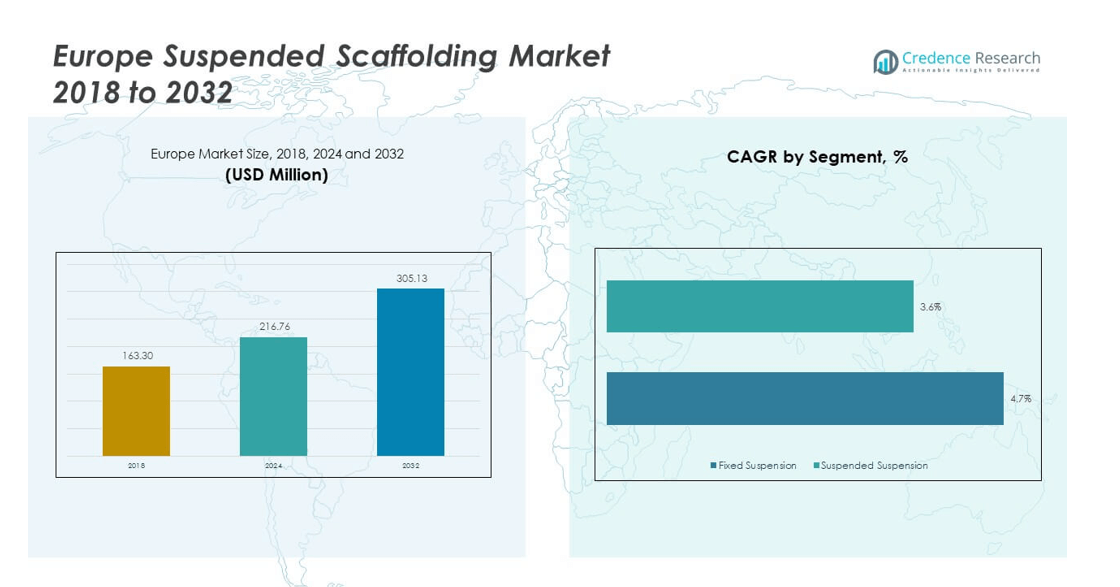
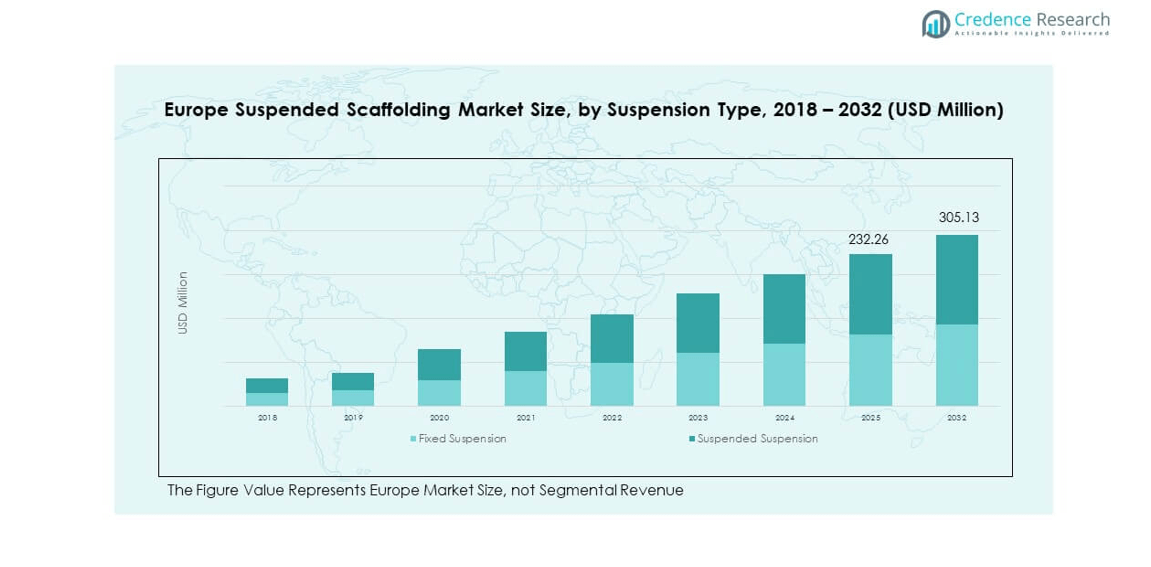
The Europe Suspended Scaffolding Market size was valued at USD 163.30 million in 2018 to USD 216.76 million in 2024 and is anticipated to reach USD 305.13 million by 2032, at a CAGR of 4.00% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Suspended Scaffolding Market Size 2024 | USD 216.76 million |
| Europe Suspended Scaffolding Market, CAGR | 4.00% |
| Europe Suspended Scaffolding Market Size 2032 | USD 305.13 million |
The Europe Suspended Scaffolding Market is primarily driven by rising construction activities across commercial and residential sectors, coupled with increasing investments in infrastructure modernization. The demand for safer and more efficient access systems in high-rise building maintenance, facade work, and restoration projects further fuels market growth. Additionally, strict regulatory frameworks emphasizing worker safety and the integration of advanced materials and automated scaffold control systems are pushing adoption. Growth in urban renovation projects and sustainability-focused retrofitting initiatives also contribute to the rising preference for suspended scaffolding solutions across the region.
In the regional context, Western Europe dominates the Europe Suspended Scaffolding Market, led by countries such as Germany, the United Kingdom, and France due to their well-established construction industries and high demand for maintenance and refurbishment of aging infrastructure. Northern and Southern Europe are witnessing steady growth with increased investments in urban development and tourism infrastructure. Meanwhile, Eastern Europe is emerging as a high-potential area, supported by EU infrastructure funding, growing industrialization, and rising awareness of construction safety practices. The market's geographic expansion is influenced by construction trends, safety standards, and economic development levels across regions.
Market Insights:
- The Europe Suspended Scaffolding Market was valued at USD 216.76 million in 2024 and is projected to reach USD 305.13 million by 2032, growing at a CAGR of 4.00%.
- The Global Suspended Scaffolding Market size was valued at USD 882.70 million in 2018 to USD 1,240.25 million in 2024 and is anticipated to reach USD 1,921.79 million by 2032, at a CAGR of 5.24% during the forecast period.
- Growth in high-rise construction and façade refurbishment projects is driving demand for suspended scaffolding across urban centers.
- Strict safety regulations across Europe are accelerating the adoption of advanced, certified scaffolding systems with integrated safety features.
- Rising labor shortages in the construction industry are encouraging the use of mechanized suspended platforms to improve efficiency.
- High initial investment and maintenance costs of modern scaffolding systems remain a barrier for small to mid-sized contractors.
- Western Europe leads the market with 42% share, driven by mature construction markets and consistent renovation demand.
- Eastern Europe is emerging as a high-growth region, supported by EU infrastructure funding and rising urban development.
Market Drivers:
Surge in Urban Infrastructure Development Across Major European Cities
Ongoing urbanization across Europe is driving a surge in infrastructure development projects, particularly in metropolitan regions. Governments and private stakeholders are heavily investing in commercial buildings, transportation networks, and mixed-use developments. The Europe Suspended Scaffolding Market benefits from these construction activities, as suspended platforms are essential for safe and efficient vertical access. High-rise construction projects in cities like London, Berlin, and Paris require adaptable scaffolding systems. The demand for modular and quick-to-install solutions is rising with stricter timelines. Market players are introducing advanced systems to support complex architecture. This driver will remain central to market momentum through the forecast period.
- For example, during construction at 2 Finsbury Avenue in London rising to approximately 170 m a cantilever‑suspended support structure was engineered to carry a Potain tower crane, mounted off the building’s core via a steel grillage.
Growth in Renovation and Restoration of Aging Building Stock
Europe holds a large base of old and historically significant buildings in need of regular upkeep and structural restoration. Governments offer financial incentives for heritage restoration, retrofitting, and façade improvements. The Europe Suspended Scaffolding Market is gaining traction in this segment due to its flexibility in difficult-to-reach and fragile building structures. Restoration contractors prefer lightweight, adjustable platforms that minimize damage risk. The market supports tailored configurations, ensuring safety and precision. Construction companies are actively integrating scaffolding into their restoration workflows. This application will continue to generate steady demand across the continent.
- For instance, during the restoration following the catastrophic 2019 fire at Notre‑Dame Cathedral, roughly 70,000 scaffold components, totaling an estimated 600 tons, were assembled around the damaged spire to stabilize and support the structure during reconstruction a pivotal element in the protective restoration process.
Stringent Safety Regulations Promoting Technologically Advanced Scaffolding
European Union regulations mandate strict compliance with worker safety norms in construction environments. These regulations are compelling contractors to adopt advanced suspended scaffolding systems with safety features. The Europe Suspended Scaffolding Market is influenced by compliance pressures, leading to the integration of fail-safe mechanisms, smart sensors, and anti-sway technology. System automation improves handling precision and minimizes risk of workplace injuries. Safety-focused designs are now a purchase criterion for both public and private sector tenders. The market responds by investing in product innovation. Regulatory stringency will continue to shape market evolution.
Rising Labor Shortages Boosting Demand for Mechanized Access Solutions
Europe faces a declining skilled labor force in the construction sector, increasing reliance on efficient mechanized systems. Suspended scaffolding reduces manual workload and enables faster, safer access to vertical surfaces. The Europe Suspended Scaffolding Market is growing in response to this need for labor-efficient solutions. Mechanized platforms offer height adjustability and reduced dependency on ground labor. Contractors adopt such systems to optimize timelines and labor costs. This shift in labor dynamics is prompting adoption of user-friendly scaffolding products. Market vendors are aligning offerings with these workforce realities. The driver remains pivotal for both new build and maintenance projects.
Market Trends:
Adoption of Lightweight Aluminum and Composite Scaffolding Materials
Manufacturers are shifting from traditional steel to lightweight materials such as aluminum and fiber-reinforced composites. These innovations reduce equipment weight, enhance portability, and lower installation times. The Europe Suspended Scaffolding Market is seeing an influx of such systems in both rental and purchase models. Lightweight structures improve safety during handling and transport, particularly in compact urban sites. The material trend aligns with sustainability goals through recyclability. Contractors benefit from quicker turnaround on projects. Vendors promote these products as cost-effective alternatives. This trend is expected to continue influencing product design.
- For example, PERI’s Alu UP Rosett Flex system features lightweight aluminum decking (~7.5 kg/m), enabling approximately 22% lower transport weight than comparable steel scaffolding, while maintaining Load Class 5 strength. Its modular grid design and tool-free connections support fast, flexible assembly in complex construction environments.
Increased Rental Adoption Among Small and Medium Contractors
Cost-conscious construction firms are moving toward renting rather than owning scaffolding equipment. This approach minimizes capital investment and maintenance burden. The Europe Suspended Scaffolding Market reflects this preference, with rental services expanding rapidly across regions. Specialized providers offer tailored rental packages, including setup and dismantling services. Contractors gain flexibility in matching scaffolding size to project scope. Rental access supports short-term renovation or façade cleaning projects. It also allows smaller firms to meet regulatory safety requirements without heavy upfront costs. This trend will shape business models in the market.
Integration of IoT and Automation in Scaffolding Systems
The adoption of smart technologies is transforming scaffolding into data-driven systems that support real-time monitoring. The Europe Suspended Scaffolding Market is embracing IoT-enabled platforms that monitor load capacity, positioning, and environmental conditions. These systems enhance worker safety and operational control. Automated winch systems allow remote lifting and lowering of platforms. Site supervisors use dashboards to track performance and prevent misuse. Smart integration helps meet EU safety compliance while boosting productivity. This trend is gradually becoming a standard in large-scale construction projects. It reflects a broader push toward digital transformation.
Growing Demand for Customizable Modular Scaffolding Platforms
Construction firms increasingly demand modular solutions that adapt to complex building geometries and variable working heights. The Europe Suspended Scaffolding Market is responding with customizable units that offer high configurability. These modular systems reduce assembly time and enable on-site adjustments. Demand is rising in sectors such as shipbuilding, stadium construction, and bridge maintenance. Suppliers offer interchangeable components and tool-free locking systems. Modular flexibility also allows easier transportation and storage. This trend supports lean construction practices and tight project deadlines. The market will continue to innovate in this direction.
- For example, Doka introduced its Ringlock modular scaffolding system, featuring galvanized steel components that assemble via hammer-only wedge-head connectors for efficient and bolt-free deployment. It supports high load capacities and adapts to irregular structures and tight site geometries, making it well suited for infrastructure, rebar, facade, and suspended scaffolding applications.
Market Challenges Analysis:
Complex Safety Compliance and Certification Requirements Across Countries
Navigating the fragmented safety regulations across European countries poses a challenge for suspended scaffolding providers. Different nations enforce varying certification standards and worker safety protocols. The Europe Suspended Scaffolding Market must address these regulatory discrepancies while ensuring product standardization. Manufacturers face delays in market entry due to prolonged approval timelines. It requires investment in compliance teams and localized certification processes. These complexities increase operational costs and extend go-to-market durations. Smaller firms struggle to scale across multiple countries under these conditions. Harmonizing standards remains difficult under current legal structures.
High Initial Investment and Maintenance Costs for Advanced Systems
Although modern suspended scaffolding systems offer safety and efficiency, they often come with high upfront costs. The Europe Suspended Scaffolding Market sees price sensitivity among smaller contractors and firms operating on limited budgets. Initial acquisition of motorized and sensor-enabled platforms demands substantial capital. Maintenance of these systems also adds recurring expenses. Some projects prefer basic, manually operated alternatives despite regulatory incentives. Financial constraints limit adoption across certain market segments. Cost-related challenges slow down modernization of scaffolding practices in low-margin construction zones. Market penetration remains uneven due to economic disparity.
Market Opportunities:
Expansion in Renewable Energy Infrastructure Projects and Offshore Installations
Rising investments in wind farms and solar energy projects across Europe are opening new application areas. Suspended scaffolding platforms serve installation and maintenance needs on offshore wind turbines and tall energy structures. The Europe Suspended Scaffolding Market can tap into this sector by offering corrosion-resistant and high-load-bearing systems. Vendors have opportunities to create energy-specific solutions that meet operational risks in marine environments. Growth in this niche can expand revenue sources for manufacturers. It also encourages collaborations with energy developers and EPC contractors across Europe.
Growing Demand for Scaffolding in Vertical Farming and Industrial Maintenance
Innovative use cases such as indoor vertical farming and complex industrial facility maintenance are creating fresh demand. The Europe Suspended Scaffolding Market can expand into these sectors by supplying compact, adjustable, and low-footprint systems. These applications require flexible platforms for access in constrained environments. Market players can differentiate by offering compact modular products tailored to these needs. This emerging demand represents a diversification opportunity beyond traditional construction markets. Vendors can leverage these segments for higher-margin contracts and specialized service offerings.
Market Segmentation Analysis:
The Europe Suspended Scaffolding Market is segmented
By suspension type into fixed suspension and suspended suspension. Suspended suspension leads the segment due to its flexibility and widespread application in high-rise construction and restoration projects. Fixed suspension is used in stable and repetitive applications where structural integration is viable.
- For instance, BrandSafway’s QuikDeck® system supports live load capacities up to 75 psf (~366 kg/m²) depending on configuration and suspender spacing. Its modular, tool-free assembly makes it a preferred solution for bridge and industrial maintenance, providing quick setup and safe, stable access work on complex structures
By material, the market is divided into steel and aluminum. Steel scaffolding holds a significant share due to its durability and high load capacity. However, aluminum is gaining traction for its lightweight nature, ease of transport, and corrosion resistance, making it ideal for maintenance and renovation projects.
- For example, KOMPLET Suspended Scaffolding by Accesus uses aluminum modules to create platforms from 2m up to 15m long, with a maximum capacity of 1,180kg (approx. 2,600lbs). This system is lightweight and easy to transport.
By capacity, the market is categorized into light duty (up to 1,000 lbs), medium duty (1,000–2,000 lbs), and heavy duty (over 2,000 lbs). Medium duty scaffolding dominates due to its versatility across construction and industrial applications. Light duty platforms are preferred for inspections and low-impact maintenance, while heavy duty systems are deployed in large-scale industrial and infrastructure projects.
By end use, the market includes construction, maintenance, inspection, and others. Construction leads the segment owing to increased high-rise developments and commercial infrastructure upgrades. Maintenance activities drive steady demand across residential and public assets. Inspection-based applications require lightweight and easily maneuverable scaffolding, supporting the use of modular platforms. The “others” category includes niche applications like event setups and specialized industrial uses, contributing to market diversity. The segment distribution reflects the broad application scope of suspended scaffolding systems across evolving urban and industrial landscapes.
Segmentation:
By Suspension Type:
- Fixed Suspension
- Suspended Suspension
By Material:
- Steel
- Aluminum
By Capacity:
- Light Duty (Up to 1,000 lbs)
- Medium Duty (1,000–2,000 lbs)
- Heavy Duty (Over 2,000 lbs)
By End Use:
- Construction
- Maintenance
- Inspection
- Others
By Region:
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
Regional Analysis:
Western Europe holds the largest share of the Europe Suspended Scaffolding Market, accounting for 42% of the regional market. Countries like Germany, France, and the United Kingdom drive growth due to their advanced construction sectors and frequent refurbishment of aging infrastructure. High demand for safe, efficient scaffolding systems in commercial real estate and public infrastructure upgrades sustains this dominance. Government mandates on worker safety and energy-efficient retrofits further accelerate product adoption. The market benefits from strong supplier networks and early adoption of automation. It remains a hub for product innovation and large-scale application.
Northern and Southern Europe collectively represent around 34% of the Europe Suspended Scaffolding Market. In Northern Europe, countries such as Sweden and Denmark show rising demand due to high-rise construction, sustainable building practices, and urban development. Southern Europe, including Italy and Spain, is recovering from past economic slowdowns with increased investment in tourism infrastructure, restoration projects, and urban renewal. These regions rely on flexible and modular scaffolding platforms suited to diverse building structures. Regulatory alignment with EU safety norms supports market development. Construction firms in these regions increasingly prioritize efficiency and safety.
Eastern Europe accounts for 24% of the Europe Suspended Scaffolding Market and represents a high-growth region. Countries such as Poland, Romania, and the Czech Republic are experiencing industrial expansion, modernization of transport infrastructure, and growing urbanization. EU funding and foreign investment in infrastructure projects support demand for advanced scaffolding systems. The market is gradually shifting from traditional scaffolding to suspended platforms due to cost efficiency and reduced labor requirements. Awareness of safety standards is improving, creating opportunities for international players. It stands as a promising region for long-term market penetration.
Key Player Analysis:
- Layher Ltd
- PERI Group
- GBM
- ADTO Industrial Group
- Altrad Group
- ULMA Group
- Aluminium Scaffold Towers Limited
- Euroscaffold Nederland
- MJ-Gerüst GmbH
- Waco Scaffolding and Equipment Company
Competitive Analysis:
The Europe Suspended Scaffolding Market features a competitive landscape with a mix of established global players and regional providers. Key companies include Altrex, FIXATOR, Tractel, Bee Access, and GEDA GmbH, each offering differentiated products tailored to various construction and industrial applications. Firms compete on parameters such as platform safety, material innovation, automation integration, and service contracts. Strategic partnerships with construction companies and rental service providers enhance market positioning. Manufacturers actively invest in R&D to meet evolving EU safety standards and environmental regulations. Pricing pressure persists due to the growing rental model and demand for cost-effective solutions. The market remains dynamic with frequent product upgrades and regional expansions.
Recent Developments:
- In March 2025, Layher Ltd genuinely launched a new era of scaffolding solutions at Bauma 2025, including innovations in safety, digitalization, modular spans, and sustainability-all supported by an official press article from Scaffmag. This includes the debut of their rebranded visual identity, CO₂-reduced decks, updates to the SoloTower and SIM2Field tools for smarter site planning, and several new scaffolding system components.
- In May 2025, the PERI Group’s affiliated company, Perion Network Ltd., officially acquired Greenbids, an advanced AI platform for digital campaign optimization, as covered in an official BusinessWire press release. The acquisition aims to enhance the company’s market position and digital capabilities globally, positioning PERI for further expansion and innovation.
Market Concentration & Characteristics:
The Europe Suspended Scaffolding Market demonstrates moderate concentration, with a few dominant players controlling significant market share. It is characterized by strong regulatory influence, technological advancement, and a growing preference for modular, lightweight systems. The market emphasizes safety compliance and equipment reliability. Rental models are gaining traction across small to medium contractors. Demand is largely project-driven and varies with public infrastructure cycles and urban development. Customization, quick installation, and low maintenance are essential buyer considerations. Competitive differentiation hinges on innovation and regional service capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Suspension Type, Material, Capacity and End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Europe Suspended Scaffolding Market is expected to witness steady growth driven by the continued expansion of commercial construction across major urban centers.
- Adoption of advanced safety technologies such as automated hoists and load monitoring systems will increase across high-rise and industrial projects.
- Rising demand for façade maintenance and retrofit initiatives will sustain long-term use of suspended scaffolding in both public and private sectors.
- Technological integration, including IoT and remote control features, will become a core differentiator among leading manufacturers.
- Growth in offshore infrastructure and renewable energy installations will create new use cases for corrosion-resistant suspended scaffolding systems.
- Market participants will expand rental services to support growing demand from cost-sensitive contractors and short-duration projects.
- Customizable modular platforms will gain traction due to their adaptability in complex architectural environments and time-sensitive applications.
- Regional expansion by international players into emerging Eastern European markets will intensify competitive dynamics.
- Stricter regulatory enforcement around worker safety and structural compliance will drive investments in certified scaffolding systems.
- Collaboration between OEMs and construction technology firms will foster innovation in product design and deployment efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Urban Infrastructure Development
Ongoing urbanization and infrastructure investments in major European cities are increasing the need for suspended scaffolding, especially for high-rise construction and complex architectural projects that require safe and efficient vertical access.
Growth in Renovation and Restoration of Aging Building Stock
Europe's large base of historic and aging buildings drives demand for suspended scaffolding, as these systems are essential for safe restoration, façade upgrades, and retrofitting projects, often incentivized by government programs.
Stringent Safety Regulations and Compliance
Strict EU and national safety regulations are compelling contractors to adopt advanced, certified suspended scaffolding systems with integrated safety features, driving market growth as compliance becomes a key purchasing criterion.
Rising Labor Shortages and Mechanization
A shrinking skilled labor pool in construction is accelerating the adoption of mechanized and automated suspended scaffolding platforms, which reduce manual workload, improve efficiency, and help contractors meet tight project timelines.
Adoption of Lightweight and Modular Materials
The shift toward lightweight aluminum and composite scaffolding materials is enabling faster installation, easier transport, and improved safety, making these solutions increasingly attractive for both new construction and renovation projects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Suspended Scaffolding Market, and what is its projected size in 2032?
Which Europe Suspended Scaffolding Market segment held the largest share in 2024?
Who are the leading companies in the Europe Suspended Scaffolding Market
Which region commanded the largest share of the Europe Suspended Scaffolding Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Construction
- 1.2.2 Maintenance
- 1.2.3 Inspection
- 1.2.4 Others
- 1.3 By Capacity
- 1.3.1 Light Duty (Up to 1,000 lbs)
- 1.3.2 Medium Duty (1,000–2,000 lbs)
- 1.3.3 Heavy Duty (Over 2,000 lbs)
- 1.4 By Material
- 1.4.1 Steel
- 1.4.2 Aluminum
- 1.5 By Suspension Type
- 1.5.1 Fixed Suspension
- 1.5.2 Suspended Suspension
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 216.76 million → 2032: USD 305.13 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Suspended Scaffolding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Suspended Scaffolding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Suspended Scaffolding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Suspended Scaffolding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Suspended Scaffolding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Suspended Scaffolding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Suspended Scaffolding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Suspended Scaffolding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 216.76 million → 2032: USD 305.13 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Suspended Scaffolding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Construction
- 12.3.7.2 Maintenance
- 12.3.7.3 Inspection
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Capacity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Light Duty (Up to 1,000 lbs)
- 12.4.7.2 Medium Duty (1,000–2,000 lbs)
- 12.4.7.3 Heavy Duty (Over 2,000 lbs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Steel
- 12.5.7.2 Aluminum
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Suspension Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Fixed Suspension
- 12.6.7.2 Suspended Suspension
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Suspended Scaffolding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Suspended Scaffolding Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Suspended Scaffolding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Suspended Scaffolding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Layher Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 PERI Group
- 18.4 GBM
- 18.5 ADTO Industrial Group
- 18.6 Altrad Group
- 18.7 ULMA Group
- 18.8 Aluminium Scaffold Towers Limited
- 18.9 Euroscaffold Nederland
- 18.10 MJ-Gerüst GmbH
- 18.11 Waco Scaffolding and Equipment Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

