
UAE Commercial Interior Fit Out Market Overview:
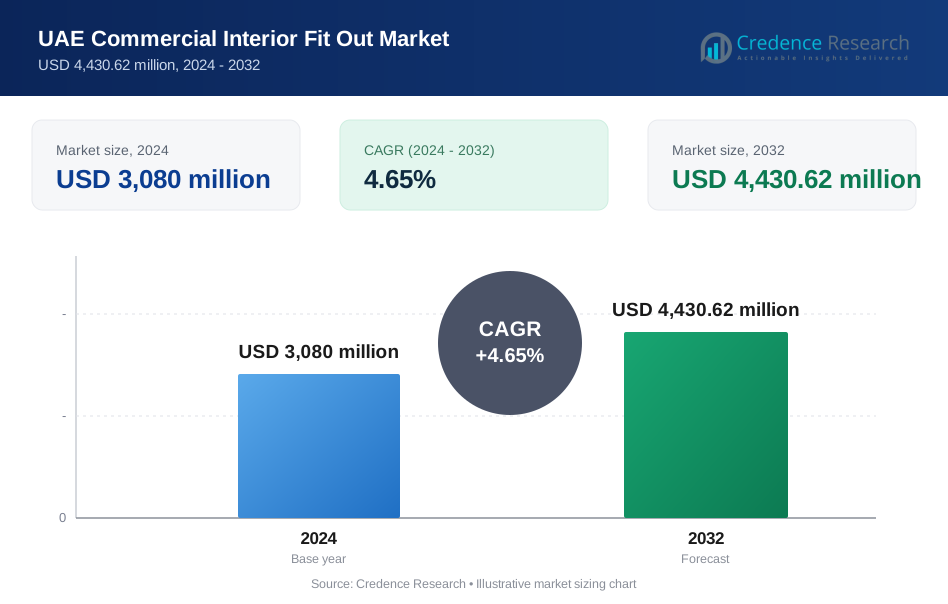
UAE Commercial Interior Fit Out Market size was valued at USD 3,080 million in 2024 and is anticipated to reach USD 4,430.62 million by 2032, at a CAGR of 4.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| UAE Commercial Interior Fit Out Market Size 2024 | USD 3,080 million |
| UAE Commercial Interior Fit Out Market , CAGR | 4.65% |
| UAE Commercial Interior Fit Out Market Size 2032 | USD 4,430.62 million |
UAE Commercial Interior Fit Out Market Insights
- Demand rises due to expanding commercial spaces, hospitality upgrades, and growing preference for sustainable and technology-integrated interiors across major business hubs.
- Key trends include hybrid office adoption, shorter refurbishment cycles, and higher investment in automation, modular layouts, and energy-efficient materials.
- The market remains competitive as leading firms focus on premium execution, faster delivery, and smart design capabilities to secure large contracts in office, retail, and hospitality sectors.
- Dubai dominated the market with about 49% share in 2024, followed by Abu Dhabi at nearly 32%, while hospitality led the application segment with around 34% share due to ongoing tourism growth and luxury renovation projects.

UAE Commercial Interior Fit Out Market Segmentation Analysis:
By Ownership
Self-owned spaces led the ownership segment in the UAE Commercial Interior Fit Out Market in 2024 with about 58% share. Many companies invested in long-term interior upgrades to enhance brand identity and improve workplace efficiency. Demand grew as firms sought flexible layouts, sustainable materials, and energy-saving designs. Rented spaces expanded as well due to rising commercial leasing in major hubs such as Dubai and Abu Dhabi. Growth in this category came from frequent tenant transitions, faster renovation cycles, and strong demand for modular and ready-to-move interior solutions.
- For instance, Emaar’s Dubai Mall Zabeel extension added almost 15,000 square meters of space and 3,000 parking spaces in Dubai.
By Application
Hospitality dominated the application segment in 2024 with nearly 34% share. Expansion in hotels, resorts, and luxury dining spaces boosted demand for premium fit-out work focused on themed aesthetics and guest experience. Commercial offices followed, supported by hybrid work layouts and modern collaboration zones. Retail also saw steady upgrades as brands refreshed stores to attract higher footfall. Growth across education and healthcare came from new institutional projects and rising quality benchmarks. The overall segment advanced due to rising construction activity and continuous design modernization in the UAE.
- For instance, Rixos Premium Dubai at JBR operates 414 rooms and suites along with 9 dining outlets, showing large-scale hospitality fit-out demand.
Key Growth Drivers
Rising Commercial Expansion
The UAE Commercial Interior Fit Out Market grows due to steady development across offices, retail hubs, and hospitality sites. New business setups in Dubai and Abu Dhabi increased demand for modern layouts that support branding and employee comfort. Many firms now focus on flexible work zones, visitor areas, and smart meeting rooms. This shift drives continuous spending on interior upgrades as companies aim to improve productivity and enhance client experience. Strong government support for foreign investment also pushes more commercial projects into the pipeline.
- For instance, DMCC reported 2,692 new companies joining its Dubai free zone in 2023, taking total registered firms to more than 24,000.
Focus on Premium Hospitality Projects
Growth accelerates as hotels, resorts, and fine-dining venues invest in themed interiors that enhance customer appeal. UAE tourism recovery and higher visitor inflow created strong demand for fresh designs, luxury finishes, and experience-focused spaces. Hospitality brands update lobbies, rooms, and dining zones to stay aligned with modern aesthetics. Developers also adopt sustainable materials and advanced lighting systems to improve service quality. This ongoing refurbishment cycle supports strong revenue expansion within the fit-out sector.
- For instance, FIVE Palm Jumeirah in Dubai offers 470 rooms and suites plus a 150-meter private beach as part of its luxury resort design.
Adoption of Smart and Sustainable Designs
Workplaces and commercial sites increasingly shift to energy-efficient layouts, automation, and eco-friendly materials. Companies demand intelligent lighting, modular partitions, and sensor-based climate systems to reduce long-term operating costs. Sustainability certifications also influence design choices, creating more demand for compliant solutions. These upgrades help businesses meet ESG goals while improving staff well-being. This transition toward smart and green interiors plays a major role in driving market growth across urban business districts.
Key Trends and Opportunities
Shift Toward Hybrid Work Environments
Many UAE companies redesign offices to support hybrid roles and enhance teamwork. Fit-out projects now focus on collaborative spaces, quiet zones, and technology-enabled meeting rooms. Demand rises for adaptable furniture, acoustic solutions, and flexible layouts that can shift with workforce needs. This trend creates strong opportunities for suppliers offering modular systems and digital integration. Growing preference for employee-centric workplaces supports long-term investment in innovative interior concepts.
- For instance, Jabra and partners opened the Hybrid Work Experience Center in Dubai Design District in 2022 as a 10-vendor collaboration showroom for hybrid-ready workspaces.
Growth of Renovation and Refurbishment Cycles
Frequent upgrades across retail, hospitality, and commercial offices create clear opportunities for fast-turnaround fit-out solutions. Brands seek refreshed interiors to maintain customer attention and remain competitive. Many projects target enhanced visual appeal, optimized space usage, and improved energy savings. The rising number of leased properties also fuels recurring renovation work as tenants update spaces during occupancy shifts. These ongoing cycles increase market stability and broaden opportunities for contractors.
- For instance, Majid Al Futtaim announced a renovation of Mall of the Emirates that will add 20,000 square meters of extra space and accommodate around 100 new stores in Dubai.
Demand for Technology-Integrated Spaces
Businesses now adopt integrated systems that support automation, digital displays, and smart security. Fit-out companies gain opportunities as clients ask for advanced meeting rooms, IoT-enabled office functions, and interactive retail features. The trend aligns with national goals for digital innovation across commercial sectors. This opportunity strengthens demand for providers offering both technical expertise and modern design capabilities.
Key Challenges
High Cost of Premium Materials and Labor
The market faces pressure from rising prices of imported materials, skilled labor, and specialized equipment. Premium finishes, sustainable products, and advanced electrical systems increase project budgets. Many clients delay upgrades or reduce scope due to cost concerns. Contractors also face tight margins while balancing quality expectations and cost-controlled delivery. These factors slow growth in cost-sensitive segments such as small offices and independent retailers.
Regulatory Compliance and Project Delays
Fit-out activities must meet strict building codes, safety rules, and approval procedures in major UAE cities. Lengthy permit cycles and design revisions often delay execution timelines. Firms also navigate frequent policy updates linked to sustainability and fire safety. These compliance requirements add complexity and administrative cost for contractors. Delays affect overall project flow and reduce profitability, creating a major challenge for market expansion.
Regional Analysis
Dubai
Dubai held the leading position in the UAE Commercial Interior Fit Out Market in 2024 with about 49% share. Strong demand came from expanding office hubs, luxury hotels, and high-traffic retail zones. Large multinational firms continued to invest in premium interiors to improve brand visibility and staff efficiency. Frequent refurbishment cycles in malls and hospitality sites also supported steady growth. Dubai’s push for tourism, global events, and foreign business setup increased the number of new commercial projects, raising spending on modern, technology-integrated, and sustainability-focused fit-out solutions across prime business districts.
Abu Dhabi
Abu Dhabi accounted for nearly 32% share of the UAE Commercial Interior Fit Out Market in 2024. Growth came from major government-backed developments, new commercial towers, and premium hospitality projects. Corporate offices in financial and energy sectors upgraded interiors to support digital work environments and productivity gains. Hotels and cultural venues also invested in thematic and sustainability-driven design updates. Abu Dhabi’s rapid expansion of mixed-use zones encouraged more demand for high-quality fit-out services. Rising investment in smart infrastructure strengthened the need for advanced lighting, automation, and modular design features across commercial properties.
Sharjah
Sharjah held about 11% share in 2024, supported by rising commercial space occupancy and the growth of mid-scale retail and hospitality projects. Local businesses invested in practical, cost-efficient interior upgrades to improve customer experience and operational flow. Education and healthcare facilities also contributed to steady demand through new campuses and clinic expansions. Sharjah’s focus on cultural tourism encouraged more boutique hotels and themed retail spaces, creating consistent fit-out opportunities. Increasing interest in sustainable layouts and energy-efficient lighting contributed to broader modernization across commercial zones in the emirate.
Rest of UAE
The Rest of UAE captured nearly 8% share in 2024, driven by development activity in emerging commercial clusters across Ras Al Khaimah, Fujairah, and Ajman. Growth came from expanding SMEs, new hospitality properties, and rising retail investment in secondary cities. Many projects focused on functional layouts, cost-effective materials, and faster completion requirements. Tourism-focused developments also boosted demand for modern interiors in resorts and service centers. Government infrastructure initiatives encouraged business expansion, creating steady fit-out opportunities across smaller markets seeking to improve commercial appeal and support new investment activity.
UAE Commercial Interior Fit Out Market Segmentations:
By Ownership
- Self-Owned
- Rented
By Application
- Hospitality
- Commercial
- Retail
- Education
- Healthcare
- Others
By Geography
- Dubai
- Abu Dhabi
- Sharjah
- Rest of UAE
Competitive Landscape
The UAE Commercial Interior Fit Out Market features strong competition among leading companies such as Summertown Interiors, Al Nabooda Interiors LLC, Horton Interiors, BW Interiors, Bond Interiors, Khansaheb Interiors, Al Shirawi Contracting Company LLC, Kinnarps Project Solutions LLC, A&T Group Interiors, and Xworks Interiors LLC.
Market participants focus on high-quality design execution, sustainable materials, and efficient project delivery to meet rising client expectations. Many firms invest in digital tools, advanced project management systems, and smart interior solutions to strengthen service capability. Competition intensifies as contractors pursue large hospitality, office, and retail projects across Dubai and Abu Dhabi.
Companies also expand renovation services to cater to frequent upgrade cycles in malls and corporate spaces. A growing emphasis on green certifications encourages broader adoption of energy-efficient systems and eco-friendly finishes, shaping long-term differentiation strategies across the competitive landscape.
Key Player Analysis
- Summertown Interiors
- Al Nabooda Interiors LLC
- Horton Interiors
- BW Interiors
- Bond Interiors
- Khansaheb Interiors
- Al Shirawi Contracting Company LLC
- Kinnarps Project Solutions LLC
- A&T Group Interiors
- Xworks Interiors LLC
Recent Developments
- In 2025, Bond Interiors secured a major contractto handle the complete interior fit-out for MERED's ICONIC Residences Design by Pininfarina, a 290-meter ultra-luxury tower in Dubai Internet City, covering residential units and common areas.
- In 2025, A&T Group Interiors earned recognition as a leading fit-out contractor in the Fit-Out Powerlist 2025 for exceptional craftsmanship across commercial projects.
- In 2024, Khansaheb Interiors Completed work on The Lana - Dorchester Collection in Business Bay, Dubai, a significant hospitality project.
Report Coverage
The research report offers an in-depth analysis based on Ownership, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow as new commercial spaces open across major UAE cities.
- Hospitality projects will expand due to rising tourism and premium guest experience demand.
- Offices will shift toward hybrid layouts, increasing need for flexible interior solutions.
- Retail brands will refresh stores more often to stay competitive in high-traffic zones.
- Smart and automated interior technologies will gain wider adoption in commercial sites.
- Sustainability-focused materials and energy-efficient designs will become standard choices.
- Refurbishment cycles will shorten as businesses frequently update branding and layouts.
- Fit-out contractors will invest in digital tools to improve project speed and accuracy.
- Government infrastructure programs will create more opportunities in emerging business districts.
- Demand for high-quality, customized interiors will rise as companies strengthen brand identity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Commercial Expansion
Steady development of offices, retail hubs, and hospitality sites in major UAE cities is driving demand for modern, flexible, and branded interior fit-out solutions. New business setups and government support for foreign investment are fueling continuous upgrades and new projects.
Focus on Premium Hospitality Projects
The growth of tourism and luxury hospitality in the UAE is leading to increased investment in themed, high-end interiors for hotels, resorts, and fine-dining venues. Ongoing refurbishment cycles and the need to enhance guest experiences are boosting fit-out demand in this segment.
Adoption of Smart and Sustainable Designs
Businesses are increasingly seeking energy-efficient layouts, automation, and eco-friendly materials to reduce operating costs and meet ESG goals. This shift toward smart and green interiors is a major growth driver, especially in urban business districts.
Shift Toward Hybrid Work Environments
The adoption of hybrid work models is prompting companies to redesign offices with collaborative spaces, quiet zones, and technology-enabled meeting rooms. This trend is increasing demand for modular, adaptable, and digitally integrated fit-out solutions.
Growth of Renovation and Refurbishment Cycles
Frequent upgrades in retail, hospitality, and commercial offices, driven by the need to maintain competitiveness and adapt to changing tenant requirements, are creating recurring opportunities for fast-turnaround fit-out projects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for UAE Commercial Interior Fit Out Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the UAE Commercial Interior Fit Out Market projected to grow between 2025 and 2032?
Which UAE Commercial Interior Fit Out Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the UAE Commercial Interior Fit Out Market?
Who are the leading companies in the UAE Commercial Interior Fit Out Market?
Which region commanded the largest share of the UAE Commercial Interior Fit Out Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Ownership
- 1.2.1 Self-Owned
- 1.2.2 Rented
- 1.3 By Application
- 1.3.1 Hospitality
- 1.3.2 Commercial
- 1.3.3 Retail
- 1.3.4 Education
- 1.3.5 Healthcare
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,080 million → 2032: USD 4,430.62 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UAE Commercial Interior Fit Out Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UAE Commercial Interior Fit Out Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UAE Commercial Interior Fit Out Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UAE Commercial Interior Fit Out Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UAE Commercial Interior Fit Out Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UAE Commercial Interior Fit Out Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UAE Commercial Interior Fit Out Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UAE Commercial Interior Fit Out Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,080 million → 2032: USD 4,430.62 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UAE Commercial Interior Fit Out Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Ownership - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Self-Owned
- 12.3.7.2 Rented
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitality
- 12.4.7.2 Commercial
- 12.4.7.3 Retail
- 12.4.7.4 Education
- 12.4.7.5 Healthcare
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 UAE Commercial Interior Fit Out End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 UAE Commercial Interior Fit Out Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 UAE Commercial Interior Fit Out Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 UAE Commercial Interior Fit Out Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Summertown Interiors
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Al Nabooda Interiors LLC
- 18.4 Horton Interiors
- 18.5 BW Interiors
- 18.6 Bond Interiors
- 18.7 Khansaheb Interiors
- 18.8 Al Shirawi Contracting Company LLC
- 18.9 Kinnarps Project Solutions LLC
- 18.10 A&T Group Interiors
- 18.11 Xworks Interiors LLC
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

