
Rimless Toilets Market Overview:
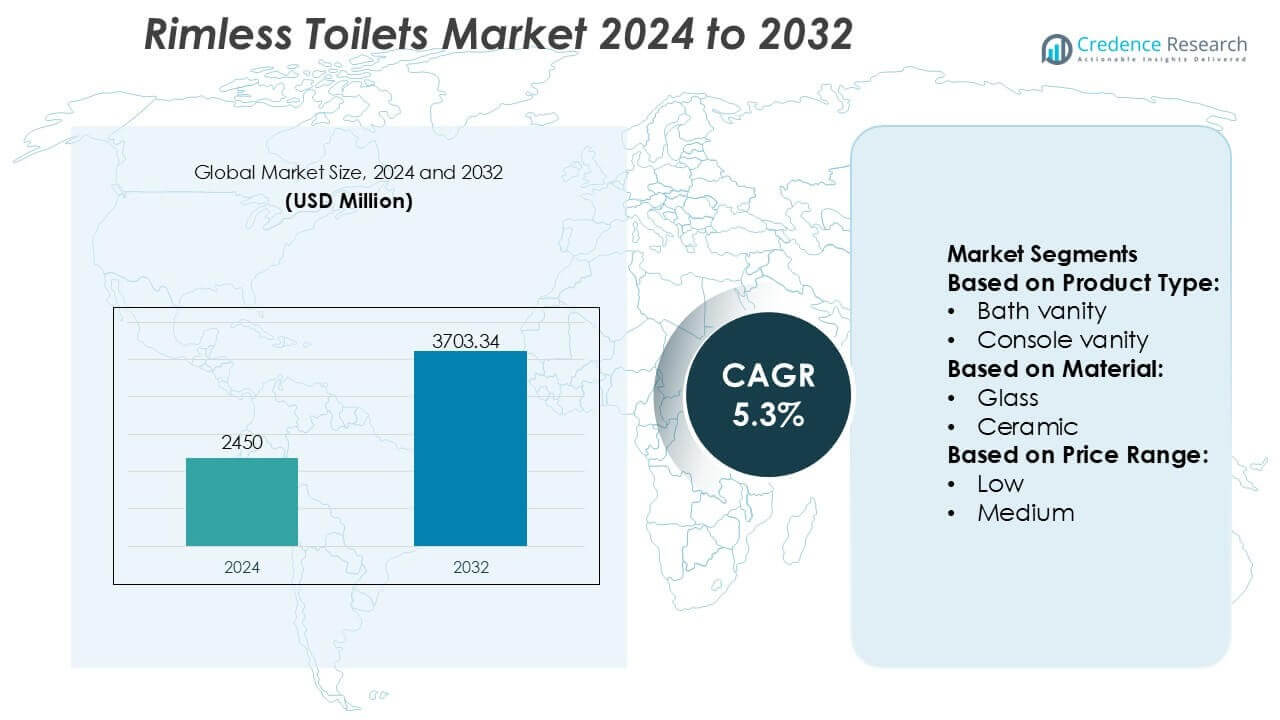
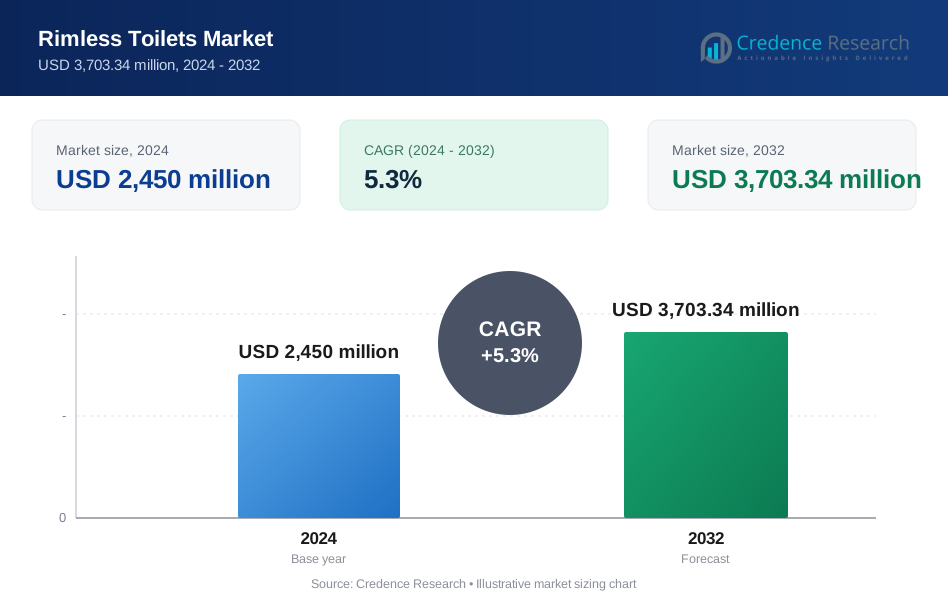
Rimless Toilets Market size was valued USD 2450 million in 2024 and is anticipated to reach USD 3703.34 million by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rimless Toilets Market Size 2024 | USD 2450 million |
| Rimless Toilets Market, CAGR | 5.3% |
| Rimless Toilets Market Size 2032 | USD 3703.34 million |
Rimless Toilets Market Insights
- Market growth is primarily driven by increasing demand for improved sanitation, easy-to-clean designs, and water-efficient fixtures, with the residential segment accounting for over half of total demand due to urban housing and renovation activity.
- Key market trends include adoption of antibacterial ceramic glazing, advanced rimless flushing hydraulics, and integration of touchless and smart bathroom features in mid- to premium-range products.
- Competitive analysis highlights strong rivalry among global manufacturers focused on design differentiation, automated production, premium finishes, and expansion across renovation and commercial construction channels.
- Regionally, Europe leads with an exact 38% market share, driven by stringent sanitation regulations, early technology adoption, high refurbishment rates, and strong demand from residential, hospitality, and institutional end users.
Rimless Toilets Market Segmentation Analysis:
By Product Type
Within the product type segmentation of the rimless toilets market, bath vanity–integrated toilet solutions emerge as the dominant sub-segment, accounting for an estimated 34% market share. Their leadership is driven by growing demand for space-efficient, integrated bathroom layouts that combine aesthetics with functionality. Bath vanities paired with rimless toilets enhance hygiene, simplify cleaning, and support minimalist bathroom designs, particularly in urban residential projects and premium hotels. Console vanities and vanity tops follow, benefiting from modular installations and customization trends, while bathroom mirrors and other accessories remain complementary, driven largely by renovation and replacement demand rather than new construction.
- For instance, Wellis engineers rimless toilet bowls with precisely contoured flush channels delivering controlled water distribution across the entire bowl surface, and its integrated vanity systems are manufactured using high-density ceramic bodies fired at temperatures above 1,200 °C, ensuring enhanced surface hardness, long-term dimensional stability, and consistent glaze adhesion for improved cleanability.
By Material
By material, ceramic holds a dominant position with approximately 46% market share, supported by its durability, ease of cleaning, stain resistance, and cost-effectiveness. Ceramic rimless toilets align well with hygiene-focused consumer preferences, as their non-porous surfaces reduce bacterial buildup. Glass and stone materials are increasingly adopted in high-end and designer bathrooms, driven by visual appeal and premium positioning, while wood-based applications remain niche due to moisture sensitivity and higher maintenance requirements. Overall, material selection is strongly influenced by lifecycle performance, water resistance, and compatibility with modern rimless flushing technologies.
- For instance, Kohler Co. produces vitreous china toilet bodies fired at temperatures exceeding 1,200 °C, achieving surface hardness values above 6 on the Mohs scale, and applies proprietary glazes engineered to withstand more than 1,000 standardized chemical exposure cycles without loss of gloss or smoothness, directly supporting hygiene and long-term durability in rimless ceramic designs.
By Price Range
In terms of price range, the medium-priced segment leads the rimless toilets market with an estimated 41% share, balancing affordability with advanced hygiene features and modern design. This segment benefits from rising middle-income households, large-scale residential developments, and hospitality projects seeking value-oriented premium solutions. Low-priced products gain traction in cost-sensitive markets through basic rimless designs, while high-priced offerings cater to luxury residences and upscale commercial spaces, driven by designer finishes, smart toilet integration, and advanced flushing systems. The medium segment’s dominance reflects strong volume demand and broad applicability across end-user categories.
Key Growth Drivers
Hygiene and Infection Control Standards
Rising awareness of bathroom hygiene and infection prevention is a primary growth driver for the rimless toilets market. Rimless designs eliminate concealed rims where bacteria, limescale, and dirt typically accumulate, enabling more effective flushing and easier cleaning. This advantage aligns strongly with stricter hygiene standards in residential buildings, healthcare facilities, hotels, and commercial spaces. Increasing concerns over waterborne pathogens and post-pandemic sanitation practices further accelerate adoption. Consumers and facility managers increasingly prefer solutions that reduce cleaning time, chemical usage, and maintenance costs while ensuring visibly cleaner toilet bowls.
- For instance, Jomoo Group manufactures rimless ceramic bowls fired at temperatures above 1,250 °C to achieve high vitrification density, and applies antibacterial glaze systems validated through laboratory testing to inhibit microbial growth across 24-hour incubation cycles, while automated flushing pathways are engineered to withstand more than 200,000 mechanical flush cycles without degradation, directly supporting long-term hygiene performance.
Urbanization and Modern Bathroom Renovation
Rapid urbanization and the steady growth of residential construction and renovation projects significantly support market expansion. Rimless toilets are increasingly specified in modern bathroom designs due to their sleek appearance, wall-hung compatibility, and space-saving profiles. Rising disposable incomes and lifestyle upgrades, particularly in urban households, encourage replacement of conventional toilets with contemporary, premium alternatives. Developers and architects favor rimless models to enhance property value and align with minimalist interior trends. This driver is reinforced by the growing penetration of organized retail and branded sanitaryware showrooms.
- For instance, Duravit AG produces rimless ceramic toilet bodies fired at temperatures exceeding 1,230 °C, applies its HygieneGlaze antibacterial surface treatment activated within 24 hours of exposure, and validates rimless flushing systems through endurance testing exceeding 250,000 flush cycles, ensuring sustained hygiene performance, surface integrity, and mechanical reliability over extended service life.
Water Efficiency and Sustainability Focus
Water conservation initiatives and sustainability-driven purchasing decisions are strongly influencing demand for rimless toilets. Advanced rimless flushing systems distribute water more evenly around the bowl, achieving effective cleaning with lower water volumes. Regulatory pressure to adopt water-efficient fixtures in residential and commercial buildings further supports this shift. Consumers increasingly associate rimless toilets with eco-friendly performance, reduced water bills, and compliance with green building standards. Manufacturers’ continuous improvements in dual-flush and optimized hydraulic designs strengthen the value proposition in both developed and emerging markets.
Key Trends & Opportunities
Adoption of Smart and Premium Sanitaryware
The integration of rimless technology into premium and smart toilet offerings represents a major market opportunity. Rimless designs are increasingly combined with features such as soft-close seats, concealed cisterns, touchless flushing, and antimicrobial coatings. This trend is particularly strong in luxury residential projects, hotels, and high-end commercial developments. Consumers seeking enhanced comfort, aesthetics, and hygiene are driving demand for technologically advanced sanitaryware. As smart home adoption expands, rimless toilets positioned within connected bathroom ecosystems are expected to gain further traction.
- For instance, Masco Corporation, through its premium plumbing brands, has developed electronic flushing systems rated for more than 300,000 actuator cycles, integrates infrared sensors with response times below 0.3 seconds, and manufactures soft-close seat assemblies tested for controlled closure durability exceeding 50,000 open–close cycles, reinforcing reliability and performance in smart rimless toilet platforms.
Growth in Commercial and Hospitality Applications
Expanding commercial infrastructure and hospitality projects present strong growth opportunities for rimless toilets. Hotels, airports, offices, and shopping centers prioritize fixtures that ensure cleanliness, durability, and low maintenance. Rimless toilets meet these requirements by simplifying cleaning routines and maintaining consistent hygiene standards under high-traffic conditions. Increasing investments in tourism and commercial real estate, particularly in emerging economies, support this trend. Specifiers increasingly recommend rimless models to reduce long-term operational costs and enhance user perception of restroom cleanliness.
- For instance, Xiaomi Corporation integrates rimless toilet solutions within its AIoT ecosystem using millimeter-wave and infrared sensors capable of detecting user presence within 0.2 seconds, supports electronic flushing actuators tested beyond 200,000 operational cycles, and employs ceramic glaze firing processes above 1,200 °C to ensure high-density, non-porous bowl surfaces compatible with automated cleaning and smart monitoring functions.
Expansion in Emerging Markets
Emerging markets offer significant untapped potential due to improving living standards and expanding urban housing. As awareness of hygiene and modern bathroom solutions increases, consumers in these regions are gradually shifting from basic sanitaryware to advanced designs. Government-led housing programs and infrastructure upgrades further support adoption. Manufacturers focusing on cost-optimized rimless models and localized distribution strategies can capture new customer segments. This trend creates opportunities for volume growth beyond premium urban centers.
Key Challenges
Higher Initial Cost Compared to Conventional Toilets
The relatively higher upfront cost of rimless toilets remains a key challenge, particularly in price-sensitive markets. Advanced flushing technologies, precision manufacturing, and premium materials contribute to higher prices compared to traditional rimmed models. For cost-conscious consumers and large-scale housing projects, this can limit adoption despite long-term hygiene and maintenance benefits. Budget constraints often lead buyers to prioritize lower initial expenditure over lifecycle value. Manufacturers must balance innovation with cost optimization to improve affordability and broaden market penetration.
Installation and Consumer Awareness Barriers
Limited consumer awareness and perceived installation complexity can hinder market growth. Some buyers remain unfamiliar with rimless technology and its advantages, leading to hesitation or preference for conventional toilets. Additionally, improper installation can impact flushing performance, creating negative perceptions. In regions with limited access to trained installers, adoption may be slower. Overcoming this challenge requires stronger education efforts, clear product communication, and collaboration with plumbers, contractors, and retailers to ensure correct installation and consistent performance.
Regional Analysis
North America
North America dominates the rimless toilets market with an estimated 34% market share, supported by strong residential renovation activity and early adoption of water-efficient bathroom fixtures. The U.S. leads regional demand due to strict plumbing efficiency standards, high awareness of hygiene benefits, and widespread acceptance of premium sanitaryware in both residential and commercial projects. Growth is further reinforced by smart bathroom integration, including touchless flushing and antimicrobial coatings. Canada contributes steadily through sustainable housing initiatives, while hospitality and healthcare infrastructure upgrades across the region continue to drive replacement demand for rimless toilet systems.
Europe
Europe accounts for approximately 31% of the global rimless toilets market, driven by stringent water conservation regulations and high penetration of modern bathroom designs. Countries such as Germany, the UK, Italy, and France lead adoption due to strong consumer preference for hygienic, easy-to-clean toilet systems. Sustainability certifications and eco-labeling play a critical role in purchase decisions, favoring rimless designs with reduced water usage. Renovation of aging housing stock, combined with premiumization trends in residential and hospitality sectors, sustains steady demand across both Western and Northern Europe.
Asia-Pacific
Asia-Pacific holds an estimated 26% market share and represents the fastest-growing regional market for rimless toilets. Rapid urbanization, rising disposable incomes, and expanding middle-class populations in China, Japan, South Korea, and India are key growth drivers. Large-scale residential construction, smart city projects, and increasing awareness of hygiene standards are accelerating adoption. Japan remains a technology leader with advanced sanitary innovations, while Southeast Asia shows rising demand from hotels and commercial developments. Price-competitive manufacturing and expanding distribution networks further strengthen regional market momentum.
Latin America
Latin America captures around 5% of the rimless toilets market, supported by gradual modernization of residential infrastructure and growing hospitality investments. Brazil and Mexico are the primary contributors, driven by urban housing projects and refurbishment of commercial buildings. Adoption remains moderate due to price sensitivity; however, increasing awareness of hygiene, water efficiency, and long-term maintenance benefits is improving market penetration. Government initiatives promoting water-saving fixtures and rising tourism-related construction are expected to gradually enhance demand for rimless toilet systems across key urban centers.
Middle East & Africa
The Middle East & Africa region holds approximately 4% market share, with growth concentrated in the Gulf Cooperation Council countries. High-end residential developments, luxury hotels, and commercial infrastructure projects in the UAE and Saudi Arabia are key demand drivers. Rimless toilets align well with regional preferences for hygiene and premium bathroom aesthetics. In Africa, adoption remains limited but is gradually increasing in urban areas due to new residential construction and international hotel chains. Long-term growth is supported by infrastructure development and improving sanitation standards.
Rimless Toilets Market Segmentations:
By Product Type:
- Bath vanity
- Console vanity
By Material:
- Glass
- Ceramic
By Price Range:
- Low
- Medium
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the rimless toilets market players such as Wellis, Kohler Co., Jomoo Group, Duravit AG, Masco Corporation, Xiaomi Corporation, Villeroy & Boch AG, Roca Sanitario SA, Toto Ltd. the rimless toilets market is defined by intense rivalry, continuous innovation, and a strong focus on hygiene-centric design. Manufacturers compete by enhancing rimless flushing efficiency, improving water distribution dynamics, and ensuring compliance with increasingly stringent water-conservation regulations. Product differentiation increasingly relies on advanced ceramic glazing, antibacterial surface treatments, and noise-reduction flushing systems that enhance user comfort and sanitation. Companies also emphasize modern aesthetics, compact designs, and ease of installation to appeal to urban residential projects and premium commercial developments. Expansion into smart bathroom integration, including touchless flushing and sensor-based features, further intensifies competition. In addition, strategic investments in automated production lines, supply-chain optimization, and regional manufacturing hubs enable players to balance cost efficiency with consistent quality, strengthening their competitive positioning across both mature and emerging markets.
Key Player Analysis
- Wellis
- Kohler Co.
- Jomoo Group
- Duravit AG
- Masco Corporation
- Xiaomi Corporation
- Villeroy & Boch AG
- Roca Sanitario SA
- Toto Ltd.
- LIXIL Group Corporation
Recent Developments
- In December 2024, CAM Construction Services is proud to announce the expansion of its cabinet manufacturing division, Heritage Wood Mills, to Glasgow, Missouri. This helps the company in eliminating overseas reliance and strengthening domestic manufacturing capabilities.
- In April 2024, Geberit launched several new bathroom products to expand its portfolio and strengthen market penetration across different price ranges. Key introductions included the AquaClean Alba shower toilet and an expanded range of TurboFlush-equipped WCs.
- In July 2023, Roca introduced the In-Wash Insignia shower toilet, which incorporates Roca Connect technology to provide unparalleled comfort and hygiene. Through the accompanying mobile app, called In-Wash Insignia, users can conveniently customize and regulate various operational modes and daily functionalities.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Price Range and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of rimless toilets will increase as hygiene awareness and sanitation standards continue to strengthen globally.
- Manufacturers will focus on improving flushing dynamics to enhance bowl coverage while minimizing water consumption.
- Demand will rise in urban residential projects driven by compact bathroom designs and modern aesthetics.
- Commercial and hospitality sectors will increasingly specify rimless models to meet higher cleanliness expectations.
- Smart bathroom integration, including touchless flushing and sensor-enabled features, will gain wider acceptance.
- Advanced ceramic glazing and antibacterial surface technologies will become standard across mid- to premium-range products.
- Sustainability regulations will encourage the development of water-efficient and eco-certified rimless toilet solutions.
- Growth in renovation and remodeling activities will support replacement demand in mature markets.
- Expansion of organized retail and e-commerce channels will improve product accessibility in emerging economies.
- Ongoing investments in automated manufacturing will enhance product consistency, scalability, and cost efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Rimless Toilets Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rimless Toilets Market projected to grow between 2024 and 2032?
Which Rimless Toilets Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rimless Toilets Market?
Who are the leading companies in the Rimless Toilets Market?
Which region commanded the largest share of the Rimless Toilets Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,450 million → 2032: USD 3,703.34 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rimless Toilets Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rimless Toilets Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rimless Toilets Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rimless Toilets Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rimless Toilets Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rimless Toilets Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rimless Toilets Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rimless Toilets Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,450 million → 2032: USD 3,703.34 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rimless Toilets Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rimless Toilets Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Rimless Toilets Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Rimless Toilets Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
