
Market Overview:
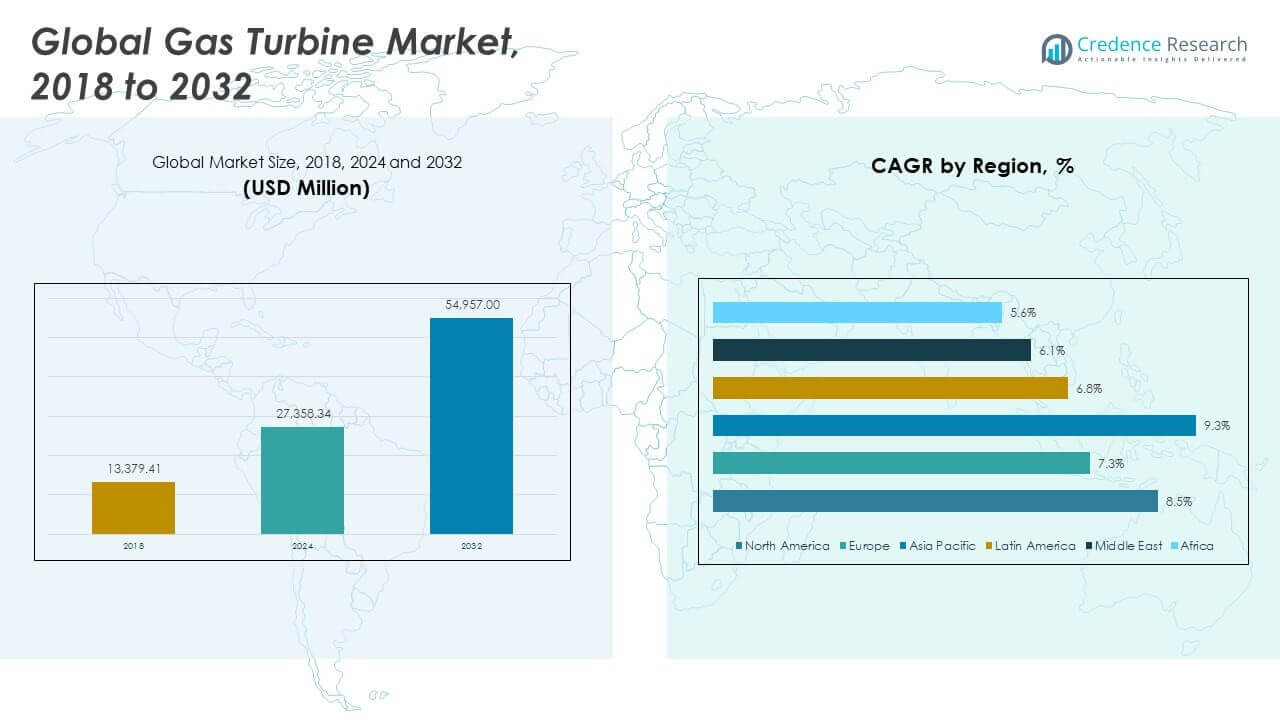
The Global Gas Turbine Market size was valued at USD 13,379.41 million in 2018 to USD 27,358.34 million in 2024 and is anticipated to reach USD 54,957.00 million by 2032, at a CAGR of 8.49% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Gas Turbines Market Size 2024 | USD 27,358.34 Million |
| Gas Turbines Market, CAGR | 8.49% |
| Gas Turbines Market Size 2032 | USD 54,957.00 Million |
Rising electricity demand drives strong investment in efficient power generation assets worldwide. Utilities favor gas turbines due to fast start capability and grid flexibility. Combined cycle plants improve fuel efficiency and lower operating costs. Governments support cleaner thermal power to reduce coal dependence. Industrial users deploy turbines for captive power and process heat needs. LNG availability improves fuel access across regions. Aging power infrastructure replacement supports steady equipment demand. Grid stability needs from renewable integration further strengthen gas turbine adoption.
North America leads due to large installed capacity and ongoing plant upgrades, led by the United States. Europe follows with a focus on energy transition and flexible backup power. The Middle East remains strong due to gas-rich economies and utility-scale projects. Asia Pacific emerges rapidly, driven by power demand growth in China and India. Southeast Asia expands capacity to support urbanization. Africa shows early growth through gas-based power diversification initiatives.
Market Insights:
- The Global Gas Turbine Market was valued at USD 13,379.41 million in 2018, reached USD 27,358.34 million in 2024, and is projected to hit USD 54,957.00 million by 2032, expanding at a CAGR of 8.49% due to rising power demand and transition fuel adoption.
- Asia Pacific leads with about 48.6% share, driven by rapid urbanization, grid expansion, and strong utility investments, followed by North America at nearly 26.9% due to grid modernization and shale gas access, and Europe at around 16.8% supported by flexible backup needs for renewable-heavy grids.
- Asia Pacific is also the fastest-growing region, supported by large-scale capacity additions in China and India, rising LNG imports, and expanding industrial captive power demand.
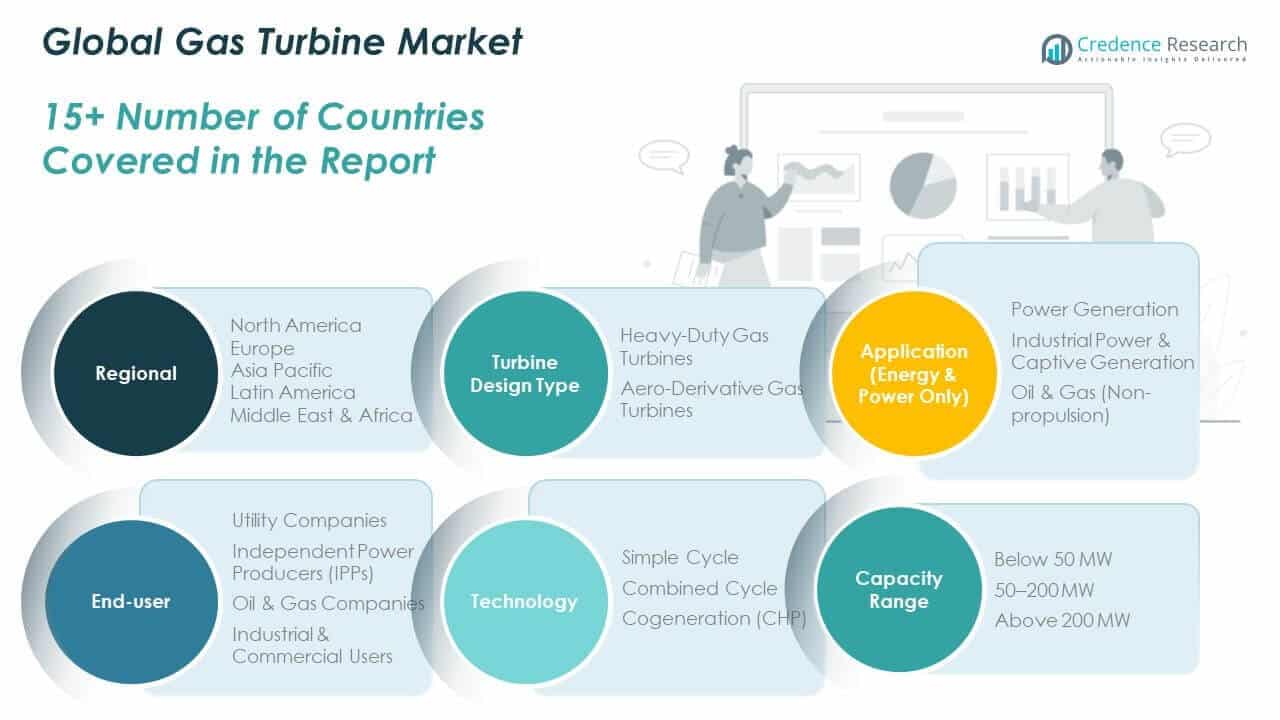
- By turbine design type, heavy-duty gas turbines account for roughly 70% of market share, reflecting dominance in utility-scale and combined cycle power plants.
- Aero-derivative gas turbines hold about 30% share, supported by demand for fast-start, flexible, and peaking power applications across utilities and industries.
Market Drivers:
Rising Need For Flexible And Reliable Power Generation Infrastructure Across Grids
The Global Gas Turbine Market gains support from rising power reliability needs. Utilities require fast ramp power for grid balance. Gas turbines provide quick start and shutdown capability. Peak load management favors flexible thermal assets. Grid operators value stable frequency control support. Industrial zones require uninterrupted electricity supply. Power shortages push capacity expansion plans. Infrastructure upgrades sustain procurement cycles.
- For instance, Siemens Energy reports that its SGT-800 gas turbine can reach full load in under 10 minutes, supporting grid frequency response in high-renewable power systems.
Strong Preference For High Efficiency Combined Cycle Power Plants
Utilities focus on higher thermal efficiency assets. Combined cycle configurations raise fuel utilization levels. Gas turbines support lower heat rates versus legacy plants. Operators aim to reduce operating expenditure. Fuel efficiency improves plant dispatch priority. Long-term power purchase agreements favor efficient units. Modern turbines fit baseload and mid-load roles. Efficiency targets drive technology upgrades.
- For instance, Mitsubishi Power states that its J-series combined cycle plants have achieved efficiency levels above 64%, lowering fuel use per unit of electricity generated.
Expansion Of Industrial Captive Power And Cogeneration Installations
Industries deploy turbines for captive power security. Manufacturing sites need stable electricity supply. Cogeneration supports simultaneous heat and power use. Process industries reduce grid dependency through turbines. Refineries and chemicals favor gas-based systems. Energy cost control influences investment decisions. Operational reliability supports continuous production. Industrial growth sustains turbine demand.
Policy Support For Cleaner Thermal Power Transition Pathways
Governments promote lower-emission power alternatives. Gas turbines emit less carbon than coal plants. Transition policies encourage fuel switching strategies. Energy security plans include gas-based generation. Power sector reforms support private investment. Regulatory clarity improves project approvals. Cleaner thermal assets fit transition timelines. Policy alignment sustains market momentum.
Market Trends:
Integration Of Advanced Digital Monitoring And Control Systems
The Global Gas Turbine Market reflects rising digital system adoption. Operators deploy predictive maintenance platforms. Sensors enable real-time performance tracking. Digital twins improve outage planning accuracy. Analytics reduce unplanned downtime risks. Control systems optimize combustion efficiency. Remote monitoring supports asset lifecycle management. Software integration enhances plant reliability.
- For instance, GE Vernova notes that its digital gas turbine fleet monitoring has reduced unplanned outages by up to 5% through condition-based maintenance analytics.
Growing Adoption Of Modular And Mobile Gas Turbine Solutions
Project developers seek faster deployment timelines. Modular turbine units support quick installation. Mobile turbines address temporary power needs. Emergency power applications expand demand. Construction sites require short-term generation assets. Utilities use mobile units during grid upgrades. Flexibility improves project economics. Compact designs gain wider acceptance.
- For instance, APR Energy deployed mobile gas turbine units in Puerto Rico after Hurricane Maria, restoring approximately 70 MW of temporary power within four weeks.
Shift Toward Long-Term Service Agreements And Lifecycle Contracts
Asset owners prefer bundled service contracts. OEM-led maintenance improves operational certainty. Long-term agreements stabilize cost forecasting. Performance-based contracts align supplier incentives. Service revenues gain strategic importance. Operators reduce in-house maintenance burden. Lifecycle management supports asset availability. Contract models reshape competitive dynamics.
Rising Focus On Fuel Flexibility And Multi-Fuel Capability
Operators demand turbines with fuel adaptability. Systems support natural gas and liquid fuels. Fuel switching improves supply security. Multi-fuel units support remote locations. Backup fuel readiness reduces operational risk. Energy transition drives interest in hydrogen blends. OEMs invest in combustion upgrades. Fuel flexibility becomes a key selection factor.
Market Challenges Analysis:
High Capital Costs And Extended Project Development Timelines
The Global Gas Turbine Market faces cost-related constraints. Large-scale plants require heavy upfront investment. Financing approvals extend project schedules. Interest rate volatility affects project viability. Developers face budget overruns during construction. Equipment customization increases procurement complexity. Long lead times delay capacity additions. Cost pressure limits adoption in smaller markets.
Regulatory Uncertainty And Environmental Compliance Pressures
Emission norms tighten across key regions. Approval processes require detailed environmental assessments. Policy shifts create planning uncertainty. Carbon pricing impacts operating economics. Public opposition delays thermal power projects. Permitting timelines vary by jurisdiction. Compliance costs increase operational burden. Regulatory risk affects investor confidence.
Market Opportunities:
Hydrogen Blending And Low-Carbon Fuel Adaptation Initiatives
The Global Gas Turbine Market sees opportunity in fuel innovation. Hydrogen blending gains policy support. OEMs develop hydrogen-ready turbines. Pilot projects validate combustion stability. Low-carbon fuels reduce emission intensity. Energy transition funding supports retrofits. Early adoption builds competitive advantage. Technology leadership drives future demand.
Emerging Market Power Expansion And Grid Modernization Programs
Developing regions expand electricity infrastructure. Urbanization increases base power demand. Grid modernization requires flexible generation assets. Gas availability improves through LNG terminals. Private power projects gain policy backing. Industrial growth drives captive installations. Electrification programs boost capacity needs. Emerging markets create long-term growth avenues.
Market Segmentation Analysis:
By Turbine Design Type
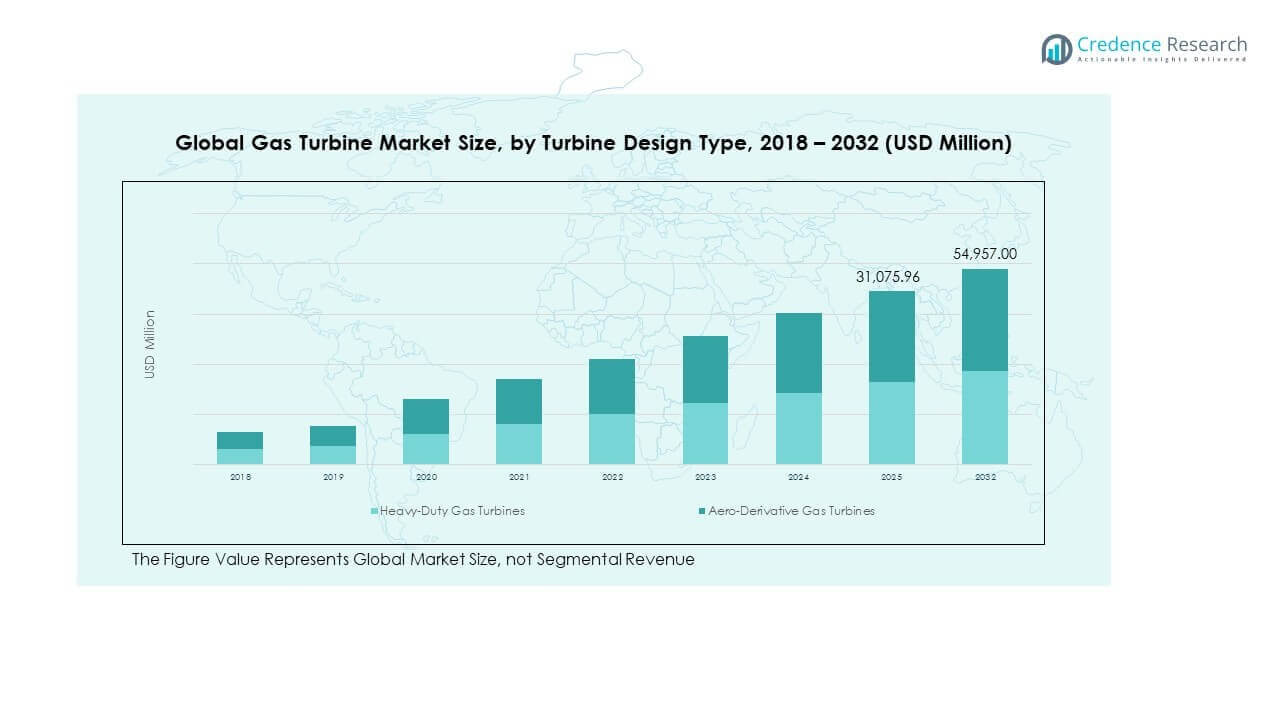
Heavy-duty gas turbines dominate large-scale and baseload projects due to high output and durability. Aero-derivative gas turbines serve peaking and fast-response needs through lightweight design and quick start capability.
- For instance, GE’s HA-class heavy-duty gas turbines have exceeded 3 million operating hours globally, supporting large combined cycle plants and industrial power applications.
By Application (Energy & Power Only)
Power generation remains the primary application due to grid reliability needs. Industrial power and captive generation support manufacturing continuity and cost control. Oil and gas non-propulsion use focuses on upstream and midstream operational power.
By End-User
Utility companies lead deployment for grid-scale electricity supply. Independent power producers focus on flexible and merchant power projects. Oil and gas companies use turbines for field operations. Industrial and commercial users adopt systems for captive and backup power.
By Technology
Simple cycle systems address peak demand and emergency use. Combined cycle technology improves efficiency through waste heat recovery. Cogeneration supports simultaneous power and thermal energy needs in industrial facilities.
By Capacity Range
Below 50 MW units serve decentralized and industrial sites. The 50–200 MW range fits mid-scale plants and captive projects. Above 200 MW systems support large utility and combined cycle installations.
By Fuel Type
Natural gas leads due to availability and lower emissions. Hydrogen-blended gas gains attention for transition pathways. Synthetic and low-carbon fuels support decarbonization goals. Dual-fuel systems improve operational flexibility.
By Component
Combustion systems drive efficiency and emission control. Turbine blades and rotors define performance limits. Compressors manage air intake efficiency. Generators convert mechanical power to electricity. Control and monitoring systems ensure safe operation. HRSGs enable combined cycle performance across the Global Gas Turbine Market.
Segmentation:
By Turbine Design Type- Heavy-Duty Gas Turbines
- Aero-Derivative Gas Turbines
- Power Generation
- Industrial Power & Captive Generation
- Oil & Gas (Non-propulsion)
- Utility Companies
- Independent Power Producers (IPPs)
- Oil & Gas Companies
- Industrial & Commercial Users
- Simple Cycle
- Combined Cycle
- Cogeneration (CHP)
- Below 50 MW
- 50–200 MW
- Above 200 MW
- Natural Gas
- Hydrogen-Blended Gas
- Synthetic & Low-Carbon Fuels
- Dual-Fuel
- Combustion Systems
- Turbine Blades & Rotors
- Compressors
- Generators
- Control & Monitoring Systems
- Heat Recovery Steam Generators (HRSGs)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Gas Turbine Market size was valued at USD 3,643.81 million in 2018 to USD 7,326.84 million in 2024 and is anticipated to reach USD 14,783.98 million by 2032, at a CAGR of 8.5 during the forecast period. North America holds nearly 26.9% share of the Global Gas Turbine Market by 2032. The region benefits from strong grid modernization programs. Utilities invest in replacing aging thermal assets. Gas turbines support renewable integration and grid stability needs. Industrial facilities rely on captive power solutions. The United States leads due to shale gas availability. Canada supports growth through efficiency upgrades. Mexico expands capacity to meet rising electricity demand.
Europe
The Europe Global Gas Turbine Market size was valued at USD 2,603.10 million in 2018 to USD 5,043.04 million in 2024 and is anticipated to reach USD 9,251.06 million by 2032, at a CAGR of 7.3 during the forecast period. Europe accounts for about 16.8% share of the Global Gas Turbine Market. Energy transition policies shape regional demand patterns. Gas turbines act as backup for renewable-heavy grids. Countries focus on flexible and low-emission assets. Combined cycle plants gain preference for efficiency. Germany and the UK drive replacement projects. Southern Europe invests in grid reliability. Regulatory clarity supports long-term capacity planning.
Asia Pacific
The Asia Pacific Global Gas Turbine Market size was valued at USD 5,916.83 million in 2018 to USD 12,540.22 million in 2024 and is anticipated to reach USD 26,709.59 million by 2032, at a CAGR of 9.3 during the forecast period. Asia Pacific holds the largest share at nearly 48.6% of the Global Gas Turbine Market. Rapid urbanization drives electricity demand growth. Countries expand utility-scale power infrastructure. Natural gas adoption supports cleaner generation goals. China and India lead capacity additions. Southeast Asia invests in flexible power assets. LNG import terminals improve fuel access. Industrial growth sustains captive power demand.
Latin America
The Latin America Global Gas Turbine Market size was valued at USD 631.97 million in 2018 to USD 1,276.19 million in 2024 and is anticipated to reach USD 2,269.03 million by 2032, at a CAGR of 6.8 during the forecast period. Latin America represents around 4.1% share of the Global Gas Turbine Market. Power demand rises with urban expansion. Gas turbines support grid reliability in hydro-dependent systems. Brazil leads regional installations. Argentina advances gas-based generation using domestic reserves. Utilities favor flexible thermal backup. Industrial users deploy captive systems. Policy reforms improve private sector participation.
Middle East
The Middle East Global Gas Turbine Market size was valued at USD 365.87 million in 2018 to USD 682.29 million in 2024 and is anticipated to reach USD 1,150.75 million by 2032, at a CAGR of 6.1 during the forecast period. The Middle East holds nearly 2.1% share of the Global Gas Turbine Market. Gas-rich economies support turbine deployment. Utilities invest in large-scale power plants. Peak power demand drives capacity expansion. Cogeneration gains traction in industrial zones. UAE and Saudi Arabia lead regional projects. Grid expansion supports economic diversification. Reliable power remains a strategic priority.
Africa
The Africa Global Gas Turbine Market size was valued at USD 217.83 million in 2018 to USD 489.77 million in 2024 and is anticipated to reach USD 792.58 million by 2032, at a CAGR of 5.6 during the forecast period. Africa accounts for about 1.4% share of the Global Gas Turbine Market. Electrification needs drive infrastructure investment. Gas turbines support off-grid and grid projects. Countries focus on reducing power deficits. Nigeria and Egypt lead gas-based capacity additions. Industrial projects adopt captive generation. Fuel availability shapes project feasibility. Development programs improve long-term market outlook.
Key Player Analysis:
- General Electric
- Siemens Energy
- Mitsubishi Power
- Ansaldo Energia
- MAN Energy Solutions
Competitive Analysis:
The Global Gas Turbine Market shows a concentrated structure with a few global OEMs holding strong positions. Leading players compete on efficiency, reliability, and lifecycle service capability. Technology depth and long-term service agreements shape competitive strength. Players invest in fuel-flexible and hydrogen-ready platforms. Regional manufacturing and service hubs improve delivery timelines. Strategic partnerships support access to large utility projects. Aftermarket services provide stable recurring revenue. It favors companies with strong balance sheets and global references.
Recent Developments:
- Ansaldo Energia secured a major contract in December 2025 from Hungary's MVM Group to supply a hydrogen-ready GT26 gas turbine and accompanying steam turbine with generators for the new Matra Power Plant. The 521-megawatt combined-cycle facility, expected to commence commercial operations in early 2029, will replace an existing lignite-fired plant and deliver up to 70 percent reduction in CO2 emissions compared to the facility it supersedes. The GT26 turbine, featuring sequential combustion for rapid load ramping and a minimum environmental load of approximately 30 percent, achieves net site efficiency of around 60 percent and can integrate up to 30 percent hydrogen in the fuel blend, providing substantial decarbonization pathway optionality. This award reinforces Ansaldo Energia's position in Central European energy transition initiatives and demonstrates market recognition of its technology platform's operational flexibility and environmental credentials.
- In November 2025, Ansaldo Energia completed a significant modernization partnership with ABB to upgrade the gas turbine control systems at Sorgenia's Modugno combined-cycle power plant in southern Italy. The 810-megawatt facility's existing gas turbine controls were evolved from legacy ABB Egatrol-8 GT26 systems to the latest ABB Ability System 800xA technology platform. This modernization extended equipment lifetime, improved operational efficiency, enhanced cybersecurity posture, and enabled seamless integration of the entire plant automation infrastructure into a unified control architecture, delivering real-time operational insights and productivity optimization for the plant operator.
- In November 2025, GE Vernova secured a significant order from Poland's Enea Group for two 9HA.01 H-Class combined-cycle blocks destined for the Kozienice Power Station. Scheduled for commercial operation in 2029, this $1.2 billion project will deliver approximately 1.2 gigawatts of electricity while generating up to 60 percent lower emissions compared to an equivalent coal-fired facility. This order represents a major milestone for GE Vernova's H-Class fleet, which has now surpassed 200 units of cumulative orders, underscoring sustained demand for heavy-duty gas turbine technology in Europe's energy transition initiatives.
- In June 2025, Siemens Energy formalized a strategic partnership with Eaton, a global power management firm, to accelerate data center construction through integrated onsite power systems. The collaboration centers on a modular, scalable power plant design producing 500 megawatts of electricity using highly efficient SGT-800 gas turbines enhanced with battery energy storage for maximum reliability. This partnership enables parallel construction of data centers and their power infrastructure, offering developers unprecedented flexibility in choosing between grid-independent and grid-connected configurations while supporting future hydrogen-ready operations as decarbonization pathways mature.
Report Coverage:
The research report offers an in-depth analysis based on turbine design type and application segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Utilities will increase investment in flexible thermal assets to support grid stability.
- Hydrogen-ready gas turbines will see wider pilot and early commercial adoption.
- Combined cycle power plants will remain the preferred choice for efficiency gains.
- Original equipment manufacturers will strengthen long-term service agreement portfolios.
- Emerging economies will drive new capacity additions across utility-scale projects.
- Digital control and monitoring systems will improve operational reliability and uptime.
- Fuel-flexible turbine designs will gain preference among power producers.
- Industrial users will continue adopting captive gas turbine power solutions.
- Grid operators will rely on gas turbines to balance renewable power variability.
- Policy support for transition power will sustain market demand over the long term.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Grid Flexibility and Renewable Integration
Gas turbines offer rapid start-up and ramping capabilities, making them essential for balancing grids with high shares of intermittent renewable energy. Utilities increasingly deploy gas turbines to provide frequency regulation and backup power, supporting stable electricity supply as renewables expand.
Preference for High-Efficiency Combined Cycle Plants
Combined cycle gas turbine plants deliver superior fuel efficiency and lower operating costs compared to older thermal assets. Utilities and independent power producers are investing in these systems to meet stricter efficiency targets, reduce emissions, and secure long-term power purchase agreements.
Industrial Captive Power and Cogeneration Demand
Manufacturing, refining, and process industries require reliable, cost-effective power and heat. Gas turbines are widely adopted for captive generation and cogeneration (CHP), enabling operational continuity, energy cost control, and reduced grid dependency for industrial users.
Policy Support for Cleaner Thermal Power
Governments are promoting gas-based generation as a transition pathway away from coal, offering regulatory clarity and incentives for lower-emission technologies. This policy environment encourages investment in new gas turbine projects and upgrades to existing plants.
Fuel Flexibility and Hydrogen-Readiness
Operators are increasingly seeking turbines capable of running on multiple fuels, including hydrogen blends, to future-proof assets against fuel supply risks and decarbonization mandates. OEMs are responding with advanced combustion systems and hydrogen-ready platforms, driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Gas Turbine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Gas Turbine Market projected to grow between 2025 and 2032?
Which Global Gas Turbine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Gas Turbine Market?
Who are the leading companies in the Global Gas Turbine Market?
Which region commanded the largest share of the Gas Turbines Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Simple Cycle
- 1.2.2 Combined Cycle
- 1.2.3 Cogeneration (CHP)
- 1.3 By Application
- 1.3.1 Power Generation
- 1.3.2 Industrial Power & Captive Generation
- 1.3.3 Oil & Gas (Non-propulsion)
- 1.4 By Capacity Range
- 1.4.1 Below 50 MW
- 1.4.2 50–200 MW
- 1.4.3 Above 200 MW
- 1.5 By Turbine Design Type
- 1.5.1 Heavy-Duty Gas Turbines
- 1.5.2 Aero-Derivative Gas Turbines
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 27,358.34 million → 2032: USD 54,957.00 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Gas Turbines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Gas Turbines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Gas Turbines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Gas Turbines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Gas Turbines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Gas Turbines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Gas Turbines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Gas Turbines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 27,358.34 million → 2032: USD 54,957.00 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Gas Turbines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Simple Cycle
- 12.3.7.2 Combined Cycle
- 12.3.7.3 Cogeneration (CHP)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Power Generation
- 12.4.7.2 Industrial Power & Captive Generation
- 12.4.7.3 Oil & Gas (Non-propulsion)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Capacity Range - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Below 50 MW
- 12.5.7.2 50–200 MW
- 12.5.7.3 Above 200 MW
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Turbine Design Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Heavy-Duty Gas Turbines
- 12.6.7.2 Aero-Derivative Gas Turbines
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Gas Turbines End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Gas Turbines Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Gas Turbines Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Gas Turbines Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 General Electric
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens Energy
- 18.4 Mitsubishi Power
- 18.5 Ansaldo Energia
- 18.6 MAN Energy Solutions
- 18.7 Baker Hughes
- 18.8 Solar Turbines (Caterpillar)
- 18.9 Rolls-Royce
- 18.10 Kawasaki Heavy Industries
- 18.11 Doosan Enerbility
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

