
Market Overview:
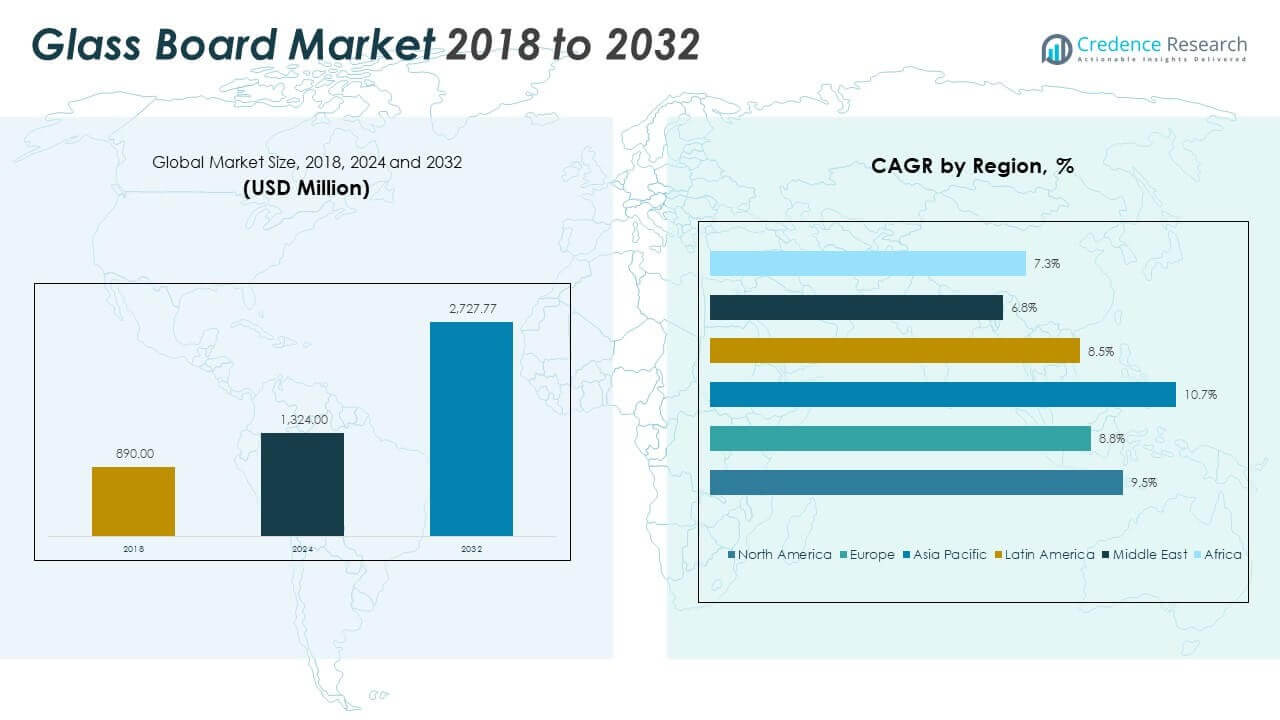
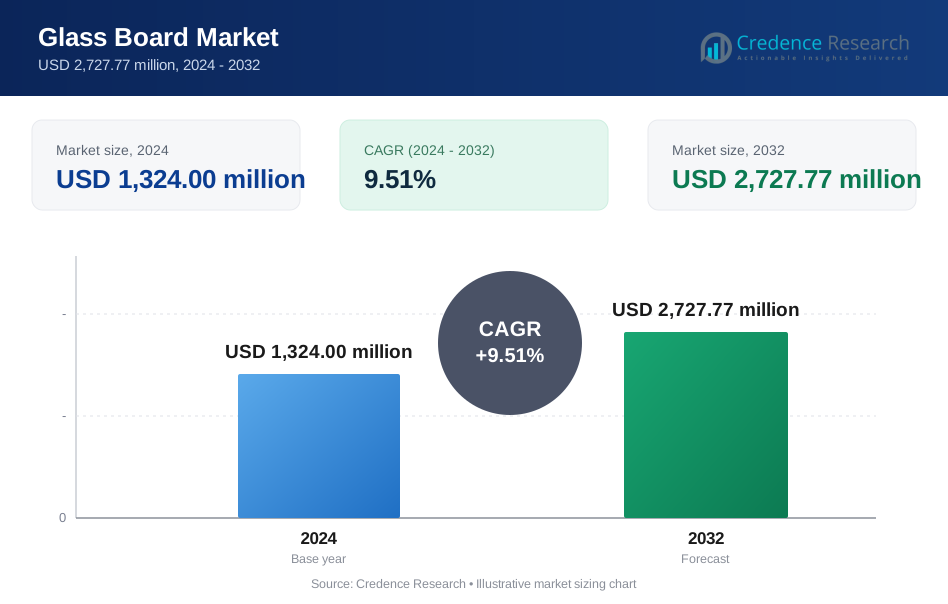
The Glass Board Market size was valued at USD 890.00 million in 2018 to USD 1,324.00 million in 2024 and is anticipated to reach USD 2,727.77 million by 2032, at a CAGR of 9.51% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Glass Board Market Size 2024 | USD 1,324.00 Million |
| Glass Board Market, CAGR | 9.51% |
| Glass Board Market Size 2032 | USD 2,727.77 Million |
The market grows due to rising demand for modern and durable visual communication tools. Corporate offices replace traditional whiteboards with glass boards for better clarity and lifespan. Education institutions adopt glass boards for clean writing and low maintenance needs. Growth in coworking spaces increases demand for stylish collaboration tools. Healthcare and commercial facilities value hygienic, non-porous surfaces. Product options such as magnetic and frameless boards improve functionality. Interior designers prefer glass boards for premium office layouts. Easy cleaning supports frequent daily use. Long service life improves overall value perception.
North America leads the market due to strong corporate infrastructure and office renovation activity. The United States drives demand across enterprises and educational institutions. Europe follows with adoption in modern workplaces and universities, led by Germany and the UK. Asia Pacific emerges rapidly due to urbanization and expanding office construction. China and India see strong uptake from commercial and education sectors. Latin America shows steady growth with improving business infrastructure. Middle East demand comes from premium offices and education projects. Africa remains emerging with gradual adoption in urban centers.
Market Insights:
- The Glass Board Market size was USD 890.00 million in 2018, rose to USD 1,324.00 million in 2024, and is projected to reach USD 2,727.77 million by 2032, growing at a CAGR of 9.51%.
- North America led the global market in 2024 with a 33.6% share, driven by high corporate infrastructure investment and rapid adoption across offices and schools.
- Asia Pacific held a 29.8% market share in 2024 and showed the fastest CAGR at 10.7%, fueled by urbanization, office expansion, and education sector upgrades in China and India.
- Europe captured 24.9% of the market in 2024, with strong demand from design-led workspaces and modern institutional deployments across Germany, the UK, and France.
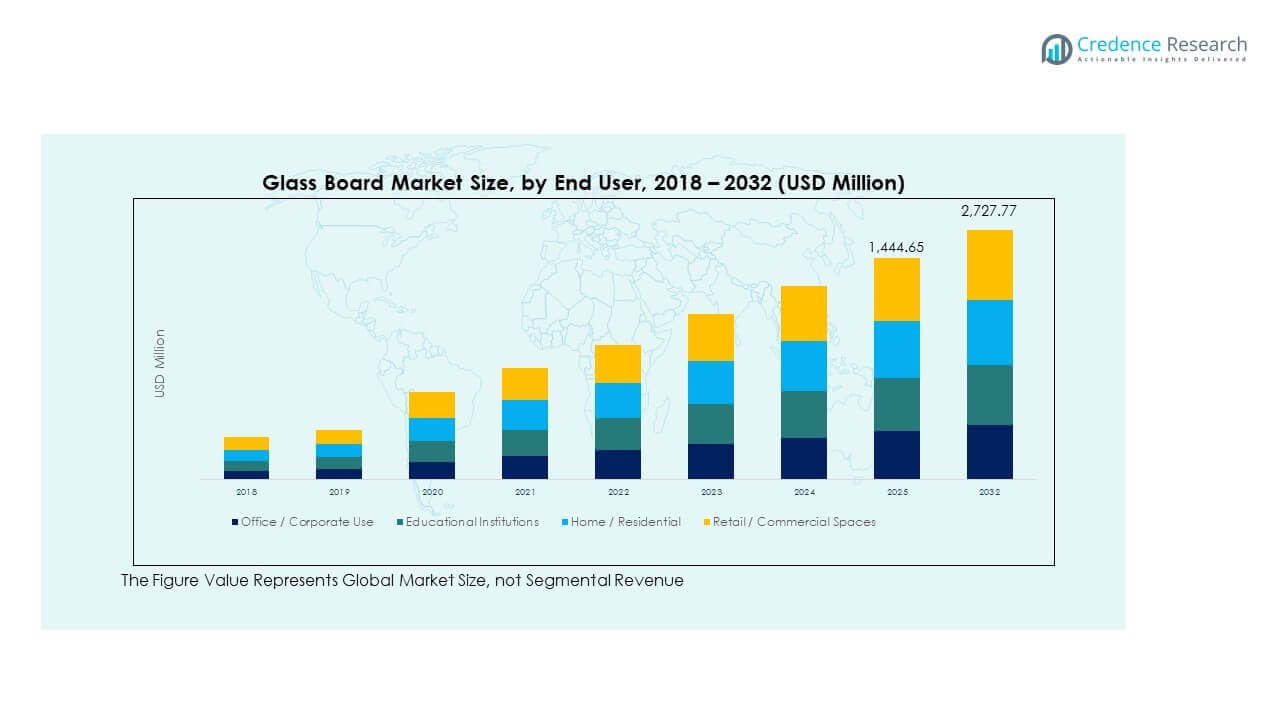
- Segment-wise, the Office/Corporate Use category accounted for the highest adoption rate, while B2B channels dominated distribution due to institutional bulk procurement patterns.
Market Drivers:
Rising Preference For Premium And Durable Writing Surfaces In Workspaces
The Glass Board Market benefits from strong demand for premium office interiors. Companies focus on clean and modern collaboration tools. Glass boards offer long service life versus traditional whiteboards. Stain resistance improves daily usability across teams. Corporate buyers value smooth writing and easy cleaning. Visual clarity supports clear presentations and meetings. It fits modern workspace design standards. Facility managers prefer low maintenance solutions. Office renovation activity sustains steady demand.
- For instance, Clarus Corporation's Lynk digital glassboard integrates VibeOS technology, enabling seamless wireless screen sharing across multiple devices in a single session.
Expansion Of Corporate Offices And Coworking Infrastructure Globally
The Glass Board Market gains traction from global office expansion. Coworking spaces invest in aesthetic collaboration tools. Startups prefer flexible and reusable writing surfaces. Enterprises expand meeting rooms and training areas. Glass boards match open office design concepts. It supports frequent brainstorming and planning sessions. Interior designers specify glass boards in new projects. Corporate real estate growth drives volume demand. Workspace upgrades remain a key driver.
- For instance, MagnaVisual's Summit Series Krystal glass writing boards use 1/4-inch tempered glass that never stains or ghosts, held 3/4-inch from walls by satin aluminum standoffs for modern aesthetics.
Growing Adoption Across Educational And Training Institutions
The Glass Board Market sees strong support from education sectors. Schools upgrade classrooms with modern teaching tools. Universities prefer reusable boards for lecture halls. Glass surfaces improve visibility for large groups. Teachers value clean boards with minimal ghosting. It supports repeated daily use without surface damage. Training centers adopt glass boards for professional appeal. Education reforms promote better learning environments. Institutional procurement strengthens market demand.
Demand For Hygienic And Easy-To-Clean Surfaces In Public Facilities
The Glass Board Market benefits from hygiene-focused purchasing behavior. Healthcare facilities prefer non-porous writing surfaces. Glass boards resist stains and chemical cleaners. Public offices value easy sanitation processes. It supports infection control practices. Smooth surfaces reduce marker residue buildup. Facility operators prioritize cleanliness standards. Safety regulations influence material selection. Hygiene awareness supports long-term adoption.
Market Trends:
Shift Toward Frameless And Minimalist Glass Board Designs
The Glass Board Market shows strong design-led product trends. Buyers prefer frameless and sleek board formats. Minimal designs suit modern office aesthetics. Wall-mounted boards save floor space. It blends with glass-heavy interiors. Neutral colors support visual consistency. Designers specify boards as décor elements. Clean edges improve visual appeal. Design differentiation influences purchasing decisions.
- For instance, Quartet Infinity Magnetic Glass boards feature frameless designs in sizes like 96 x 48 inches using tempered glass that resists scratches and dents. Minimal designs suit modern office aesthetics.
Rising Popularity Of Magnetic Glass Board Solutions
The Glass Board Market trends toward multifunctional products. Magnetic glass boards combine writing and display use. Offices use magnets for notes and charts. It reduces the need for pinboards. Users value space efficiency in meeting rooms. Product innovation focuses on stronger magnetic strength. Premium models target executive spaces. Hybrid use improves product value. Demand grows in collaborative environments.
Customization And Color Options Gaining Buyer Attention
The Glass Board Market reflects demand for customization. Buyers request custom sizes and colors. Branding requirements influence color selection. It supports corporate identity alignment. Custom boards fit unique wall layouts. Architects favor tailored installations. Manufacturers expand customization capabilities. Personalized products improve customer satisfaction. Custom orders support higher margins.
- For instance, Skyline Design writable glassboards reach up to 72 x 144 inches in 1/4-inch thickness with color-match technology from a curated library. Branding requirements influence color selection.
Growth Of Online And Direct-To-Business Sales Channels
The Glass Board Market adopts digital sales channels steadily. Buyers compare products through online catalogs. Direct sales simplify bulk corporate purchases. It improves access for small offices. E-commerce supports wider geographic reach. Online platforms offer installation support options. Digital marketing educates buyers on benefits. Faster ordering improves procurement cycles. Channel expansion reshapes distribution models.
Market Challenges Analysis:
High Initial Cost Compared To Traditional Writing Boards
The Glass Board Market faces cost-related adoption barriers. Glass boards cost more than standard whiteboards. Price sensitivity affects small offices and schools. Budget constraints delay purchase decisions. It limits penetration in developing regions. Procurement teams prioritize low-cost alternatives. Replacement cycles remain longer due to cost. Limited financing options affect buyers. Cost perception challenges market expansion.
Logistics, Installation, And Breakage Risk Concerns
The Glass Board Market experiences operational challenges. Glass products require careful transport handling. Breakage risk raises logistics costs. Installation needs skilled labor support. It increases total project expense. Improper mounting creates safety concerns. Damage during transit affects supplier margins. Limited installer availability delays projects. Operational risks impact buyer confidence.
Market Opportunities:
Rising Office Construction And Interior Renovation Activities
The Glass Board Market holds strong growth opportunities. Commercial construction supports product demand. Office renovations focus on modern collaboration tools. It aligns with workspace modernization trends. Architects specify glass boards in new builds. Corporate relocations increase fresh installations. Growing service sector expands office footprints. Design-led demand creates steady opportunities.
Untapped Demand Across Emerging Economies And SMEs
The Glass Board Market sees opportunity in emerging regions. Small enterprises seek professional office setups. Urbanization drives new office development. It supports entry-level glass board variants. Education institutions in developing markets upgrade facilities. Local manufacturing reduces product costs. Distributor expansion improves regional access. Awareness campaigns support adoption growth.
Market Segmentation Analysis:
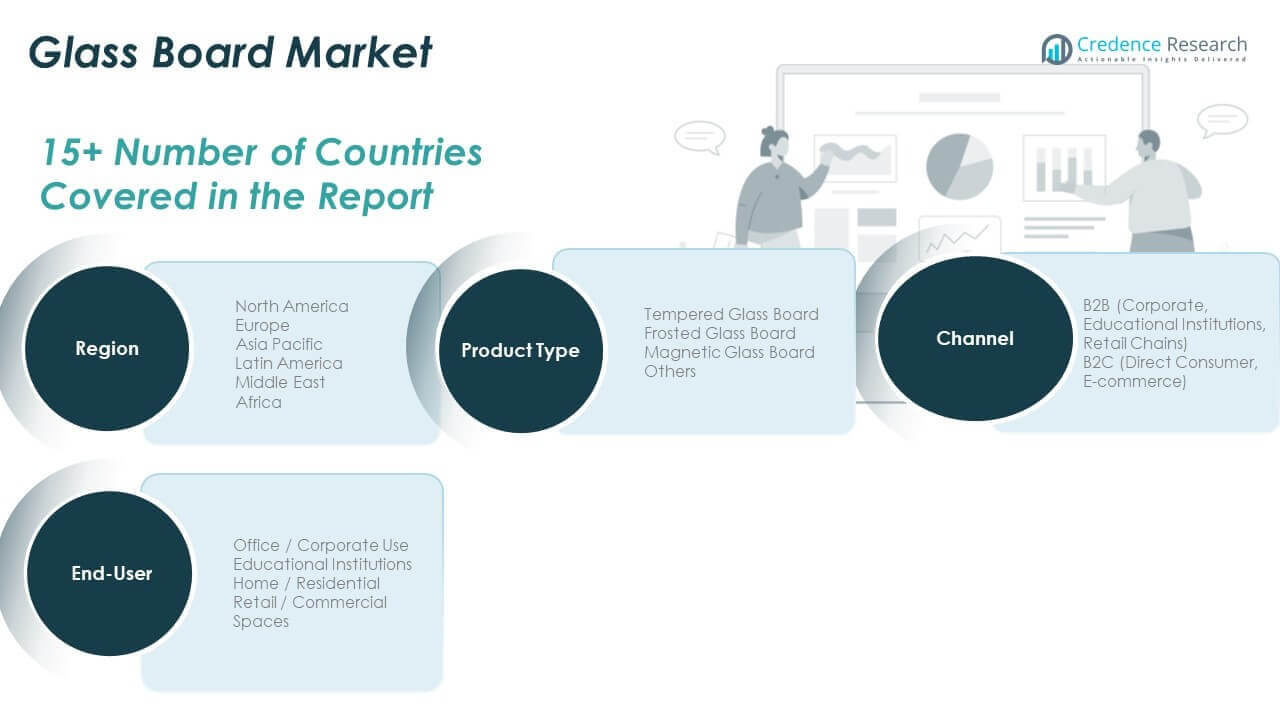
The Glass Board Market is segmented by product type, channel, and end-user, each contributing uniquely to market expansion.
By product type, tempered glass boards lead due to their durability and high resistance to stains and scratches. Frosted glass boards follow, favored for their soft, matte finish and reduced glare in high-light settings. Magnetic glass boards gain demand in collaborative offices, allowing dual functionality for writing and pinning. The “others” segment includes custom and colored boards that serve design-specific needs in modern spaces.
- For instance, Fab Glass and Mirror's tempered glass is verified as five times stronger than standard annealed glass through thermal treatment, with surface compression meeting ANSI Z97.1 standards of at least 10,000 psi.
By channel, the B2B segment dominates the Glass Board Market. Corporates, educational institutions, and retail chains invest heavily in high-volume procurement of glass boards. It supports long-term use and fits formal interiors. B2C is rising fast with growing e-commerce access and direct purchases from consumers setting up home offices or learning spaces.
- For instance, MooreCo's Visionary Hierarchy boards hold SCS Indoor Advantage Gold certification, confirming low VOC emissions for institutional bulk orders.
By end-user, office and corporate use remains the largest segment due to high demand for professional, clean communication tools. Educational institutions adopt glass boards in smart classrooms for better visibility and long-term use. Home and residential use is expanding with remote work and learning trends. Retail and commercial spaces adopt boards for display and interactive communication, further boosting product diversity.
Segmentation:
By Product Type:
- Tempered Glass Board
- Frosted Glass Board
- Magnetic Glass Board
- Others
By Channel:
- B2B (Corporate, Educational Institutions, Retail Chains)
- B2C (Direct Consumer, E-commerce)
By End-User:
- Office / Corporate Use
- Educational Institutions
- Home / Residential
- Retail / Commercial Spaces
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Glass Board Market size was valued at USD 312.57 million in 2018 to USD 459.15 million in 2024 and is anticipated to reach USD 944.63 million by 2032, at a CAGR of 9.5% during the forecast period. North America holds the largest market share of approximately 33.6%. The region’s dominance stems from high corporate infrastructure spending, particularly in the United States. Offices, coworking spaces, and educational institutions continue to modernize interiors. The demand for durable, aesthetic, and easy-to-maintain boards supports strong sales. B2B procurement across large enterprises remains consistent. Product innovation, such as magnetic and frameless glass boards, appeals to premium buyers. Educational institutions integrate these boards for long-term use and visual clarity. E-commerce and specialty retailers ensure wide availability across urban and suburban markets.
Europe
The Europe Glass Board Market size was valued at USD 243.50 million in 2018 to USD 348.70 million in 2024 and is anticipated to reach USD 680.18 million by 2032, at a CAGR of 8.8% during the forecast period. Europe accounts for approximately 24.9% of the global market. Demand grows from corporate renovations, universities, and training centers. Germany, the UK, and France lead the regional sales volume. Offices in major cities adopt design-centric glass boards to enhance collaborative spaces. Institutional buyers prioritize long-life boards to reduce maintenance needs. Frosted and customized options find traction among design-conscious customers. Regulatory focus on eco-friendly and long-lasting materials drives procurement decisions. Digital retail channels and B2C sales also gain strength.
Asia Pacific
The Asia Pacific Glass Board Market size was valued at USD 236.21 million in 2018 to USD 365.75 million in 2024 and is anticipated to reach USD 825.70 million by 2032, at a CAGR of 10.7% during the forecast period. Asia Pacific contributes approximately 29.8% to global revenue. China, India, Japan, and South Korea are key growth markets. Urbanization and rapid office construction fuel strong demand. Corporates invest in modern communication tools for new offices and training rooms. Educational spending rises across private and public schools. Low-cost manufacturing enhances regional availability. Local distributors and e-commerce platforms improve access in tier-2 and tier-3 cities. Customization options cater to diverse buyer needs. Product awareness campaigns improve uptake in emerging economies.
Latin America
The Latin America Glass Board Market size was valued at USD 56.96 million in 2018 to USD 83.93 million in 2024 and is anticipated to reach USD 160.58 million by 2032, at a CAGR of 8.5% during the forecast period. Latin America accounts for around 5.9% market share. Brazil and Mexico are the largest contributors to regional sales. Growing commercial construction and educational upgrades support demand. Businesses adopt glass boards in new office setups and training zones. Public institutions modernize infrastructure, replacing chalkboards with clean writing surfaces. Online retail platforms enable direct purchases. Import dependency affects pricing dynamics. Suppliers partner with regional distributors to strengthen presence.
Middle East
The Middle East Glass Board Market size was valued at USD 18.87 million in 2018 to USD 24.88 million in 2024 and is anticipated to reach USD 41.75 million by 2032, at a CAGR of 6.8% during the forecast period. The region holds about 1.5% of the global market. Demand emerges from the UAE and Saudi Arabia due to strong commercial project pipelines. Offices and high-end educational institutes prefer premium design finishes. Government initiatives for digital learning increase adoption in classrooms. The hospitality sector adds demand through design-focused interiors. Importers dominate the supply chain. Price sensitivity limits reach in smaller cities. Regional distributors and turnkey service providers influence bulk sales.
Africa
The Africa Glass Board Market size was valued at USD 21.89 million in 2018 to USD 41.58 million in 2024 and is anticipated to reach USD 74.93 million by 2032, at a CAGR of 7.3% during the forecast period. Africa contributes around 2.7% to the total market. South Africa and Nigeria lead regional adoption. Investments in private education and office spaces drive the market. Glass boards gain traction as long-life alternatives to whiteboards. Limited local production creates reliance on imports. Affordability remains a key concern for institutions. Urban centers show faster adoption than rural areas. Regional suppliers push awareness and cost-effective variants.
Key Player Analysis:
- Quartet Global
- Ghent International
- U Brands Inc.
- Magnetoplan GmbH
- Bi-Office Ltd
Competitive Analysis:
The Glass Board Market features a mix of global manufacturers and regional suppliers competing on design, durability, and pricing. Leading companies focus on product differentiation through frameless, magnetic, and customizable boards. Players invest in surface technology to ensure better stain resistance and writing clarity. It remains competitive due to low entry barriers in emerging markets. Key manufacturers expand reach via B2B contracts with corporate and institutional buyers. E-commerce platforms help brands capture direct consumer demand. Strategic partnerships with office furniture companies support bundled sales. Regional players target cost-sensitive segments with basic offerings. Innovation in installation systems and mounting options adds value to premium products.
Recent Developments:
- In June 2025, Quartet introduced the innovative Anti-Glare InvisaMount Glass Dry-Erase Board series, featuring advanced glass treatment that reduces reflections by up to 70% for better visibility in bright offices, along with a Flip-Top Desktop Dry-Erase Computer Pad for organized workspaces.
Report Coverage:
The research report offers an in-depth analysis based on product type, channel, and end-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for glass boards will rise with continued corporate workspace upgrades and office expansion globally.
- Integration of magnetic and hybrid-function boards will grow as collaboration needs evolve.
- Custom-sized and colored glass boards will gain popularity across startups and creative industries.
- Online B2C sales will increase as home offices and personal workspaces become more common.
- Education sector investments will drive large-scale adoption in schools, universities, and training centers.
- Urban commercial real estate projects will specify premium boards to align with modern interiors.
- Emerging markets in Asia and Latin America will offer strong volume growth due to rising office construction.
- Product durability and hygiene benefits will make glass boards preferred in healthcare and public facilities.
- Smart board integration may emerge in premium segments, merging traditional and digital writing solutions.
- Local manufacturing and distributor expansion will improve access in developing regions and reduce costs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Preference for Premium and Durable Writing Surfaces
Corporate offices and institutions are increasingly replacing traditional whiteboards with glass boards due to their superior durability, stain resistance, and modern aesthetics, supporting long-term usability and aligning with contemporary workspace design standards.
Expansion of Corporate Offices and Coworking Infrastructure
Global growth in office construction, coworking spaces, and workspace renovations is driving demand for stylish, reusable, and collaborative visual communication tools like glass boards, which are favored for their flexibility and ability to support frequent brainstorming.
Adoption in Educational and Training Institutions
Schools, universities, and training centers are upgrading to glass boards for their clean writing surfaces, minimal ghosting, and long service life, which enhances classroom visibility and reduces maintenance costs, especially as education reforms promote better learning environments.
Demand for Hygienic and Easy-to-Clean Surfaces
Healthcare facilities, public offices, and commercial spaces are prioritizing glass boards for their non-porous, easy-to-sanitize surfaces, which support infection control and meet heightened hygiene standards in high-traffic environments.
Customization and Design Trends
Rising demand for frameless, magnetic, and custom-colored glass boards is fueled by interior designers and corporate branding needs, as organizations seek visually appealing and tailored solutions that integrate seamlessly with modern office and institutional interiors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Glass Board Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Glass Board Market projected to grow between 2024 and 2032?
Which Glass Board Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Glass Board Market?
Who are the leading companies in the Glass Board Market?
Which region commanded the largest share of the Glass Board Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Channel
- 1.2.1 B2B (Corporate, Educational Institutions, Retail Chains)
- 1.2.2 B2C (Direct Consumer, E-commerce)
- 1.3 By End-User
- 1.3.1 Office / Corporate Use
- 1.3.2 Educational Institutions
- 1.3.3 Home / Residential
- 1.3.4 Retail / Commercial Spaces
- 1.4 By Product Type
- 1.4.1 Tempered Glass Board
- 1.4.2 Frosted Glass Board
- 1.4.3 Magnetic Glass Board
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,324.00 million → 2032: USD 2,727.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Glass Board Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Glass Board Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Glass Board Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Glass Board Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Glass Board Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Glass Board Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Glass Board Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Glass Board Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,324.00 million → 2032: USD 2,727.77 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Glass Board Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Channel - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 B2B (Corporate, Educational Institutions, Retail Chains)
- 12.3.7.2 B2C (Direct Consumer, E-commerce)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Office / Corporate Use
- 12.4.7.2 Educational Institutions
- 12.4.7.3 Home / Residential
- 12.4.7.4 Retail / Commercial Spaces
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Tempered Glass Board
- 12.5.7.2 Frosted Glass Board
- 12.5.7.3 Magnetic Glass Board
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Glass Board End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Glass Board Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Glass Board Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Glass Board Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Quartet Global
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ghent International
- 18.4 U Brands Inc.
- 18.5 Magnetoplan GmbH
- 18.6 Bi-Office Ltd
- 18.7 Clarus Corporation
- 18.8 MooreCo Inc.
- 18.9 Fab Glass and Mirror
- 18.10 Skyline Design
- 18.11 MagnaVisual
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

