
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Glycine Chelates Market Size 2024 | USD 2,440.01 million |
| Glycine Chelates Market, CAGR | 4.55% |
| Glycine Chelates Market Size 2032 | USD 3,574.63 million |
Market Overview:
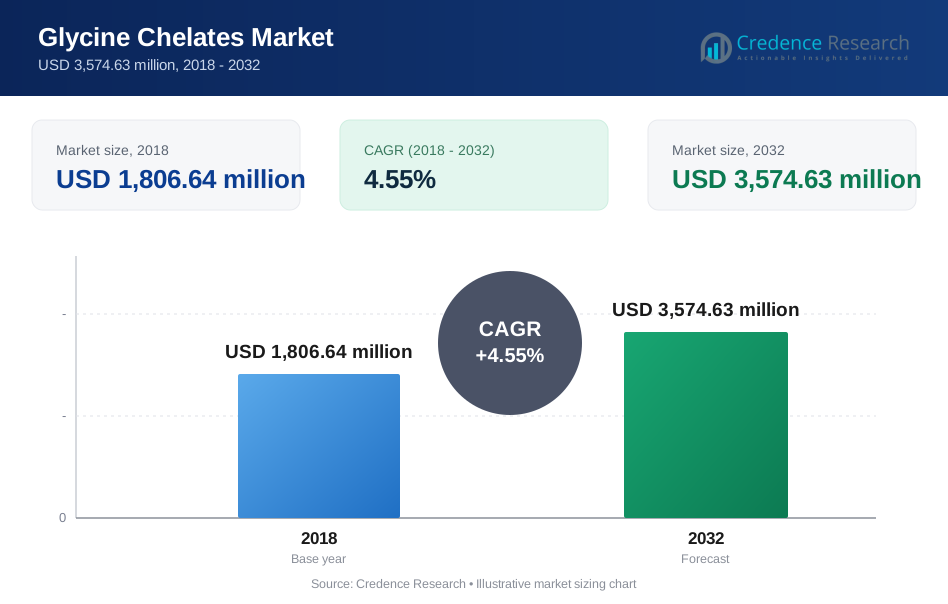
The Global Glycine Chelates Market size was valued at USD 1,806.64 million in 2018 to USD 2,440.01 million in 2024 and is anticipated to reach USD 3,574.63 million by 2032, at a CAGR of 4.55% during the forecast period.
Several factors are propelling the demand for glycine chelates. In agriculture, these chelates are increasingly utilized in fertilizers and animal feed due to their enhanced nutrient absorption properties, leading to improved crop yields and livestock health. They help improve plant growth and increase nutrient availability, even in challenging soil conditions, making them crucial for sustainable agriculture. In the pharmaceutical and nutraceutical sectors, glycine chelates are favored for their stability and efficacy in delivering essential minerals, thereby supporting metabolic functions and overall health. Their superior bioavailability ensures better absorption and effectiveness in enhancing human nutrition. Additionally, the growing consumer awareness regarding the benefits of chelated minerals is further driving market expansion, as individuals seek more efficient solutions for their health and well-being.
Geographically, the Asia-Pacific region, led by China and India, dominates the glycine chelates market. This dominance is attributed to the extensive manufacturing capabilities and the rising demand from the agriculture and feed industries, where the need for efficient, cost-effective solutions continues to grow. As countries in the region prioritize food security and high-yield farming techniques, the use of glycine chelates in agriculture becomes increasingly essential. North America, particularly the United States, exhibits significant growth potential, fueled by the increasing adoption of dietary supplements and pharmaceuticals, alongside a growing emphasis on health and wellness trends. Europe also presents steady growth opportunities, driven by advancements in agricultural practices and the demand for high-quality food products that require enhanced mineral content and bioavailability.

Market Insights:
- The Global Glycine Chelates Market was valued at USD 1,806.64 million in 2018 and is expected to reach USD 3,574.63 million by 2032, growing at a CAGR of 4.55%.
- Increasing demand for sustainable agricultural practices is propelling the market as glycine chelates improve nutrient absorption, leading to higher crop yields and healthier livestock.
- Glycine chelates are gaining traction in the nutraceutical and pharmaceutical sectors due to their superior bioavailability, which ensures better absorption of essential minerals like iron, magnesium, and calcium.
- Emerging economies, particularly in Asia-Pacific, are key growth drivers as countries like China and India modernize their agricultural practices, promoting the adoption of glycine chelates for enhanced crop productivity.
- Environmental concerns and sustainability goals are fueling the demand for glycine chelates as they help reduce nutrient waste and environmental impact in farming and industrial processes.
- High production costs pose a challenge to the market, as manufacturers struggle to streamline production while maintaining quality and cost-effectiveness.
- Regulatory hurdles in different regions, particularly around agricultural and food regulations, present challenges for global market expansion, impacting product formulations and compliance processes.
Market Drivers:
Rising Demand for Agricultural Applications
The global glycine chelates market benefits from the increasing demand for more efficient and sustainable agricultural practices. Glycine chelates are widely used in fertilizers and animal feed to improve nutrient absorption, leading to higher crop yields and healthier livestock. Their ability to provide better nutrient availability, even in nutrient-poor or challenging soil conditions, makes them essential for modern farming techniques. Farmers are increasingly relying on chelates to enhance soil health and ensure crops thrive in diverse environmental conditions. With the growing need to meet food security demands, glycine chelates help boost agricultural productivity while minimizing the use of traditional fertilizers, which can be less efficient and environmentally friendly. The shift toward precision farming further increases the adoption of these products to ensure optimum nutrient delivery.
Health and Wellness Trends Fueling the Nutraceutical and Pharmaceutical Sectors
The global glycine chelates market experiences significant growth due to the expanding consumer focus on health and wellness. In the nutraceutical and pharmaceutical sectors, glycine chelates are valued for their superior bioavailability, offering an efficient means of delivering essential minerals such as iron, magnesium, and calcium. These chelates are increasingly incorporated into dietary supplements aimed at improving health and preventing deficiencies. The market sees rising consumer awareness about the benefits of chelated minerals, particularly for bone health, immune function, and overall metabolic support. As consumers look for safe, natural, and effective alternatives to synthetic additives, the demand for glycine chelates grows, especially in the aging population seeking nutritional support.
- For instance, Albion Laboratories has long been a leader in developing highly bioavailable chelated minerals. One specific example is the use of Albion's Ferrochel® iron bisglycinate, a chelated iron supplement designed to improve iron absorption.
Agricultural Advancements in Emerging Economies
Emerging economies, particularly in Asia-Pacific, contribute significantly to the growth of the glycine chelates market. Countries like China and India are making strides in modernizing their agricultural sectors to meet the challenges posed by rapid population growth and urbanization. In these regions, the adoption of glycine chelates in agriculture improves nutrient absorption in crops, which is essential for increasing food production sustainably. Governments in these countries are pushing for more efficient farming practices, making the use of chelates a critical component in achieving higher agricultural productivity. This trend supports the increasing adoption of glycine chelates in the region, driving market expansion.
Sustainability and Environmental Awareness
Growing concerns about environmental sustainability play a key role in driving the global glycine chelates market. As more industries and consumers demand sustainable solutions, the use of chelated minerals in agricultural and industrial processes has gained significant traction. Glycine chelates contribute to reducing environmental impacts by improving the efficiency of nutrient usage, which leads to reduced waste and less runoff in farming practices. The shift toward eco-friendly products that align with sustainability goals encourages the adoption of glycine chelates across various sectors. These chelates support the sustainable use of resources, offering an effective solution for minimizing the environmental footprint of industries reliant on mineral supplementation.
- For instance, Solvay, a global leader in sustainable chemical solutions, has applied chelated minerals in agricultural applications to reduce nutrient runoff and environmental pollution.
Market Trends:
Rising Demand for Organic and Sustainable Products
The increasing consumer shift towards organic and sustainable products is significantly driving the growth of the Global Glycine Chelates Market. As consumers become more health-conscious, the demand for products that align with environmental and organic standards continues to rise. Glycine chelates, which are used in agricultural and food applications, are increasingly being recognized for their ability to improve nutrient uptake while reducing the environmental impact of fertilizers. This demand for sustainable farming practices is expected to continue, as it enhances both soil health and crop yield with minimal adverse effects on the environment. The trend is particularly strong in the agriculture sector, where organic farming is gaining traction globally.
- For instance, BASF and Yuntianhua verified a reduction of roughly 46,000 tons of CO₂ equivalent emissions in 2023 by using Limus-treated fertilizer, demonstrating the environmental benefits of innovative fertilizer solutions
Expanding Applications in Animal Feed Industry
The use of glycine chelates in animal feed has witnessed a significant increase due to their positive impact on animal health and productivity. It helps in enhancing the bioavailability of essential trace elements, which improves animal growth and reproductive performance. The Global Glycine Chelates Market is seeing wider adoption in the animal husbandry industry, especially in livestock and poultry farming. As the global demand for high-quality animal products grows, the need for more efficient and healthier feed additives continues to drive market growth. Furthermore, the rising awareness about animal welfare and the nutritional needs of livestock boosts the demand for effective chelates in feed formulations.
Technological Advancements in Chelating Agents
Technological advancements in the production and formulation of glycine chelates are contributing to the expansion of its market applications. New production techniques are leading to more efficient and cost-effective methods of manufacturing glycine chelates, making them more accessible to a wide range of industries. These innovations are particularly beneficial for sectors such as agriculture, where cost-efficiency is critical. By improving the efficiency of these chelates, manufacturers can provide better solutions for enhancing plant growth, which in turn supports the agricultural industry's need for more sustainable and high-yield solutions. The technological improvements in glycine chelates are expected to strengthen its market position further.
- For instance, Balchem is recognized as a global leader in microencapsulation technology for animal nutrition, providing rumen-protected nutrients that improve feed efficiency and allow for targeted nutrient delivery in livestock diets.
Growing Demand for Nutrient-Rich Food Products
The increasing global demand for nutrient-rich food products is driving the use of glycine chelates in the food and beverage industry. Consumers are becoming more aware of the importance of essential nutrients in their diets, which has led to a rise in the consumption of fortified foods. Glycine chelates are being incorporated into food products to enhance the bioavailability of trace minerals such as iron, zinc, and copper. As the demand for functional foods grows, it will likely lead to an increase in the application of glycine chelates in food fortification. This trend is expected to continue, especially in developing regions where micronutrient deficiencies are prevalent.
Market Challenges Analysis:
High Production Costs
One of the key challenges facing the Global Glycine Chelates Market is the high production costs associated with manufacturing these chelates. The complex synthesis process and the need for high-quality raw materials contribute significantly to the overall cost structure. As the demand for glycine chelates grows, manufacturers must find ways to streamline production without compromising the quality and effectiveness of the final product. High production costs can limit the widespread adoption of glycine chelates, particularly in regions where cost sensitivity is a major factor. This challenge could hinder market expansion, especially in price-sensitive industries such as agriculture and animal feed.
Regulatory Hurdles and Compliance
Regulatory compliance is another significant challenge for the Global Glycine Chelates Market. Different countries have varying standards and regulations concerning the use of chelates in food, agriculture, and animal feed, making it difficult for manufacturers to operate globally. Strict regulatory requirements on product formulations and labeling, particularly in the food and agricultural sectors, often delay market entry and increase operational costs. Manufacturers must navigate these regulations carefully to ensure product safety and compliance, which can be a time-consuming and costly process. This complexity limits the ability of companies to scale efficiently across regions and may discourage new entrants into the market.

Market Opportunities:
Expansion in Emerging Markets
The Global Glycine Chelates Market presents significant opportunities for growth in emerging markets, where agriculture and animal husbandry are experiencing rapid development. In regions such as Asia-Pacific and Latin America, increasing agricultural productivity and rising demand for livestock products create a fertile ground for the adoption of glycine chelates. These regions are seeing improvements in farming practices, which opens the door for more efficient and sustainable agricultural inputs. Manufacturers can capitalize on this growth by offering cost-effective and innovative glycine chelates tailored to the specific needs of these markets, potentially boosting market share.
Advancements in Functional Foods and Fortification
The growing trend of functional foods and the increasing consumer focus on health and wellness provide another promising opportunity for the Global Glycine Chelates Market. As consumers seek products that offer enhanced nutritional benefits, glycine chelates are finding new applications in food fortification. By improving the bioavailability of essential minerals, it offers a solution to micronutrient deficiencies. The market can tap into the rising demand for fortified foods, particularly in developing countries where deficiencies in trace minerals are widespread. This expanding consumer interest in health-focused products presents a key opportunity for market growth.
Market Segmentation Analysis:
The Global Glycine Chelates Market is segmented by type, form, and application, each contributing significantly to its growth.
By type, the market includes calcium glycinate, magnesium glycinate, zinc glycinate, iron glycinate, copper glycinate, manganese glycinate, and sodium glycinate. Among these, calcium glycinate and zinc glycinate are the most widely used in agricultural and nutritional applications due to their superior bioavailability.
By form, glycine chelates are primarily available in dry (powder/granules) and liquid forms. The dry form is preferred for agricultural and feed applications, while the liquid form is favored in pharmaceutical and nutraceutical industries due to its ease of absorption and application.
- For example, YaraVita GLYTREL ZnP is a liquid product that can be co-applied with other agrochemicals, and is recommended at rates of 1–3 pints per acre for crops like alfalfa and wheat, with a minimum water rate of 30 gallons per acre.
By application segment includes pharmaceuticals/nutraceuticals, food additives, feed additives, and personal care products. Pharmaceuticals and nutraceuticals dominate the market, driven by the growing need for enhanced mineral absorption to support metabolic functions and overall health. Feed additives are experiencing steady growth due to their use in improving livestock health and productivity. The demand for food additives is expanding as consumers seek nutrient-enriched food products. Personal care products, although a smaller segment, are emerging with the increasing use of chelated minerals in skincare formulations for their nutritional benefits.
- For instance, Balchem’s Albion® iron bisglycinate is incorporated into nutraceutical products that, according to company-sponsored clinical trials, raise serum ferritin by an average of 25% over 12 weeks in iron-deficient adults.
Segmentation:
By Type:
- Calcium Glycinate
- Magnesium Glycinate
- Zinc Glycinate
- Iron Glycinate
- Copper Glycinate
- Manganese Glycinate
- Sodium Glycinate
By Form:
- Dry (Powder/Granules)
- Liquid
By Application:
- Pharmaceuticals/Nutraceuticals
- Food Additives
- Feed Additives
- Personal Care Products
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Regional Analysis
The North America Global Glycine Chelates Market size was valued at USD 551.65 million in 2018, reaching USD 733.98 million in 2024, and is anticipated to reach USD 1,079.57 million by 2032, at a CAGR of 4.60% during the forecast period. North America holds a significant market share within the Global Glycine Chelates Market, driven by the growing demand for sustainable agricultural practices and high-quality animal feed. The U.S. and Canada are major contributors to this market, where advancements in farming techniques and an emphasis on organic and sustainable farming methods have spurred the use of glycine chelates. The increasing adoption of advanced farming solutions in the region, along with stringent environmental regulations, is expected to continue fueling market growth.
Europe Regional Analysis
The Europe Global Glycine Chelates Market size was valued at USD 417.95 million in 2018, reaching USD 539.52 million in 2024, and is expected to reach USD 733.20 million by 2032, with a CAGR of 3.60% during the forecast period. Europe, especially in countries such as Germany, France, and the U.K., has a strong market presence, driven by a high demand for organic farming solutions and animal feed additives. The agricultural sector in Europe focuses on reducing environmental impacts while increasing crop yield and nutrient efficiency, making glycine chelates a popular choice. The region’s stringent regulatory policies supporting sustainable agricultural practices will likely contribute to consistent growth in this market.
Asia Pacific Regional Analysis
The Asia Pacific Global Glycine Chelates Market size was valued at USD 716.04 million in 2018, reaching USD 1,006.44 million in 2024, and is expected to reach USD 1,573.25 million by 2032, at a CAGR of 5.40% during the forecast period. The market in this region is the fastest-growing, driven by the increasing adoption of modern agricultural practices, especially in countries like China, India, and Japan. The rising demand for high-quality, sustainable agricultural solutions, coupled with the growth in the animal feed industry, is boosting the use of glycine chelates. This is particularly important as Asia Pacific faces challenges related to food security and the need to enhance productivity while reducing environmental impact.
Latin America Regional Analysis
The Latin America Global Glycine Chelates Market size was valued at USD 60.43 million in 2018, reaching USD 80.19 million in 2024, and is expected to reach USD 98.31 million by 2032, with a CAGR of 2.20% during the forecast period. The market in Latin America is seeing gradual growth as agricultural practices shift towards more sustainable solutions. Countries like Brazil and Argentina are key markets, with increasing investments in agricultural innovation and animal feed enhancements. However, the adoption rate is slower compared to other regions due to cost sensitivity and regulatory factors. The market’s growth will depend on continued developments in organic and efficient farming solutions.
Middle East Regional Analysis
The Middle East Global Glycine Chelates Market size was valued at USD 35.14 million in 2018, reaching USD 41.59 million in 2024, and is expected to reach USD 46.63 million by 2032, with a CAGR of 1.10% during the forecast period. The market in the Middle East is smaller compared to other regions but is expected to grow steadily due to the region’s growing focus on improving agricultural efficiency and productivity. Countries like Saudi Arabia and the UAE are investing heavily in agricultural innovations, such as water-efficient farming techniques and nutrient-rich soil practices, which boosts the adoption of glycine chelates. However, the growth is hindered by limited arable land and the dependency on imported agricultural products.
Africa Regional Analysis
The Africa Global Glycine Chelates Market size was valued at USD 25.43 million in 2018, reaching USD 38.30 million in 2024, and is expected to reach USD 43.67 million by 2032, at a CAGR of 1.30% during the forecast period. Africa’s market for glycine chelates remains relatively small but has potential for growth, especially as the demand for more sustainable agricultural practices and animal feed solutions increases. Key markets in South Africa, Nigeria, and Egypt are beginning to recognize the benefits of using glycine chelates to improve soil health and crop yield. However, slow infrastructure development, limited access to advanced agricultural technologies, and lower adoption rates of modern farming solutions pose challenges for rapid market expansion.
Key Player Analysis:
- BASF SE
- Albion Laboratories Inc.
- Solvay SA
- Ajinomoto Co., Inc.
- Clariant AG
- Shijiazhuang Donghua Jinlong Chemical Co., Ltd.
- Galaxy Surfactants Ltd.
- Novotech Nutraceuticals Inc.
- Schaumann GmbH & Co. KG
- Dunstan Nutrition Ltd.
Competitive Analysis:
The Global Glycine Chelates Market is highly competitive, with several key players focusing on innovation and sustainability to capture a larger market share. Leading companies in this market are investing in advanced manufacturing techniques and product development to meet the increasing demand for efficient agricultural and animal feed solutions. Key players include BASF SE, AkzoNobel N.V., and Nouryon, which leverage their strong R&D capabilities to introduce more cost-effective and eco-friendly chelate formulations. Companies are also expanding their geographic presence to capitalize on emerging market opportunities, particularly in Asia Pacific and Latin America. While large multinational corporations dominate the market, regional players are making significant strides by offering tailored solutions to local agricultural needs. Competition remains intense, with firms competing on product quality, sustainability, and pricing strategies, aiming to address the growing demand for efficient nutrient delivery systems across agriculture and animal nutrition industries.
Recent Developments:
- In April 2025, BASF SE introduced a new sustainable chelating agent named Trilon G, which utilizes GLDA (glutamic acid diacetate) chemistry. This product is designed for the home care and industrial cleaning sectors, enhancing surfactant efficiency and water softening while being partially biobased and readily biodegradable. The launch reinforces BASF’s commitment to sustainability and innovation in the chelating agents market.
- In May 2025, BASF SE also announced an agreement to acquire DOMO Chemicals’ 49% stake in the Alsachimie joint venture. Upon completion, BASF will become the sole owner of Alsachimie, strengthening its position in the European polyamide 6.6 value chain and ensuring a reliable supply of polyamide precursors for industries such as automotive and textiles. The transaction is expected to close by mid-2025, pending regulatory consultations.
Market Concentration & Characteristics:
The Global Glycine Chelates Market exhibits moderate concentration, with a few large multinational companies leading the industry. These companies hold a significant share of the market due to their strong research and development capabilities, extensive distribution networks, and diverse product offerings. However, the market also features regional players who focus on localized solutions and cater to specific agricultural and animal feed needs. Market dynamics are driven by the increasing demand for sustainable and efficient agricultural practices, with a growing emphasis on organic and environmentally friendly products. As the demand for glycine chelates expands across various industries, especially in emerging markets, competition intensifies, pushing companies to innovate continuously. The market is characterized by moderate entry barriers, with established players dominating but creating space for smaller, specialized firms to grow by offering differentiated products and solutions.
Report Coverage:
The research report offers an in-depth analysis based on type, form, and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Glycine Chelates Market is expected to continue expanding, driven by increasing demand for sustainable agricultural solutions.
- Adoption in animal feed will grow as industries seek to enhance livestock productivity with efficient nutrient absorption.
- The rise in organic farming practices will fuel demand for eco-friendly and efficient fertilizers, including glycine chelates.
- Market growth in Asia Pacific will remain robust, with increased agricultural development in emerging economies.
- North America and Europe will continue to lead in market share, driven by stringent environmental regulations and innovation.
- Technological advancements in chelate production will make glycine chelates more cost-effective, supporting broader adoption.
- Rising awareness of micronutrient deficiencies will increase the use of glycine chelates in food fortification.
- The agriculture industry will see enhanced crop yields as more farmers embrace glycine chelates for nutrient optimization.
- Regulatory policies promoting sustainable practices will create opportunities for growth in the agriculture and feed industries.
- Competitive pressure will drive continuous product innovation, offering more targeted solutions for various industry needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Glycine Chelates Market?
What factors are driving the growth of the Global Glycine Chelates Market?
What are the key segments within the Global Glycine Chelates Market?
What are some challenges faced by the Global Glycine Chelates Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Glycine Chelates Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Glycine Chelates Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 1,806.64 million → 2032: USD 3,574.63 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Glycine Chelates Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Glycine Chelates Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Glycine Chelates Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Glycine Chelates Market Drivers
- 3.3 Glycine Chelates Market Restraints & Challenges
- 3.4 Glycine Chelates Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Glycine Chelates Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Glycine Chelates Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Glycine Chelates category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Glycine Chelates Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Glycine Chelates Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Glycine Chelates market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Glycine Chelates Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Glycine Chelates Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Glycine Chelates Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Glycine Chelates (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Glycine Chelates Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Glycine Chelates Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Glycine Chelates Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Glycine Chelates Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Glycine Chelates Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Glycine Chelates Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Glycine Chelates Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Glycine Chelates Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Glycine Chelates Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
