
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
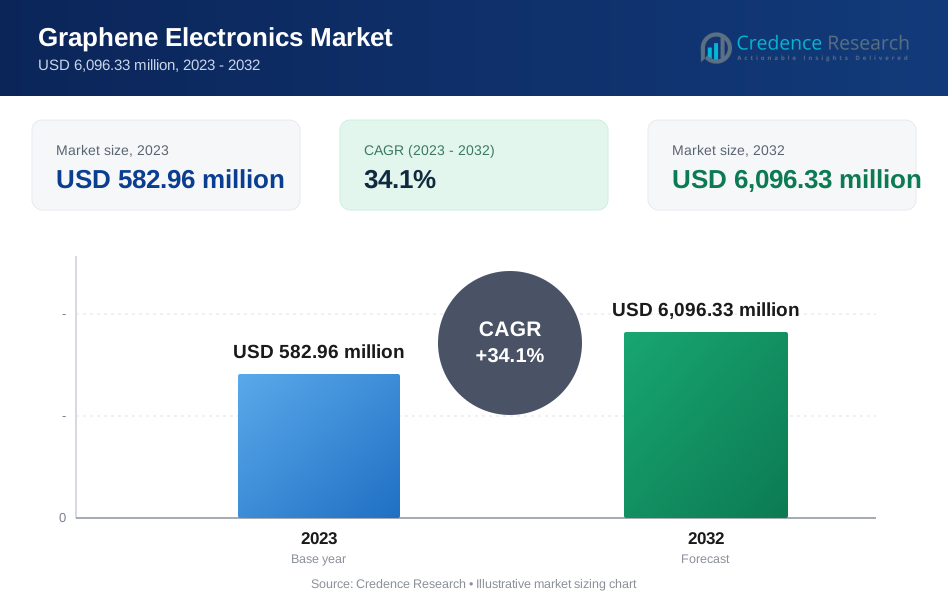
| Graphene Electronics Market Size 2023 | USD 582.96 Million |
| Graphene Electronics Market, CAGR | 34.1% |
| Graphene Electronics Market Size 2032 | USD 6,096.33 Million |
Market Overview
The Global Graphene Electronics Market is projected to grow from USD 582.96 million in 2023 to an estimated USD 6,096.33 million by 2032, reflecting a compound annual growth rate (CAGR) of 34.1% from 2024 to 2032. This exceptional growth trajectory highlights the market’s increasing adoption across various industries, including consumer electronics, energy storage, and automotive sectors. Graphene's remarkable properties, such as its high electrical conductivity, flexibility, and superior
Key drivers for the graphene electronics market's rapid growth include rising demand for high-performance electronic devices, a surge in research and development investments, and the increasing integration of graphene into next-generation batteries and sensors. Trends such as the emergence of graphene-enabled wearable technologies and the use of graphene for enhancing semiconductor devices and transparent conductive films underscore the material’s transformative potential. Additionally, the push for sustainable energy solutions and lighter, more durable electronic components is further accelerating market adoption.
Geographically, North America and Europe are key regions leading market growth due to extensive research capabilities, supportive government initiatives, and a strong base of leading industry players. Asia-Pacific is witnessing significant expansion, driven by robust demand in consumer electronics and rising industrial activity. Prominent companies driving innovation and commercialization in this market include IBM Corporation, Samsung Electronics, Graphene Flagship, Haydale Graphene Industries, and Applied Graphene Materials, all of which are leveraging graphene’s unique properties to develop cutting-edge technologies.
Market Drivers
Superior Material Properties and Broad Application Spectrum
The unique physical, electrical, and mechanical properties of graphene are a primary driver propelling the growth of the global graphene electronics market. Graphene, known for its exceptional electrical conductivity, lightweight nature, mechanical strength, and flexibility, serves as an attractive material across numerous high-performance applications. For instance, graphene's remarkable electrical conductivity and mechanical strength enable its use in high-performance applications such as transistors and sensors. Research has demonstrated that graphene transistors can achieve electron mobility rates that are substantially higher than those of traditional silicon-based devices, enhancing processing speeds in electronic circuits. Additionally, its lightweight nature and flexibility make it a prime candidate for wearable technology, where comfort and performance are paramount.Consequently, graphene finds increasing applications in transistors, sensors, touchscreens, supercapacitors, and energy storage devices. Its intrinsic properties outperform traditional materials like silicon, offering better electron mobility, superior heat resistance, and transparency. As industries such as consumer electronics, automotive, and aerospace strive to adopt efficient, durable, and lightweight solutions, the demand for graphene-based electronic products is anticipated to surge. Companies and researchers are consistently exploring graphene’s potential to create novel technologies that significantly improve device performance and energy efficiency, thereby driving market growth.
Rising Demand for Advanced and Flexible Electronics
The expanding global demand for next-generation, flexible, and wearable electronics is fostering the uptake of graphene technologies. As electronic devices become increasingly lightweight, compact, and flexible, graphene’s unique flexibility and electrical capabilities make it the preferred material for various innovative applications. For example, the development of foldable displays and smart textiles showcases how graphene's unique properties are being harnessed to create innovative solutions that meet modern consumer needs. The Internet of Things (IoT) market, as well as sectors like healthcare and telecommunications, have shown a growing inclination toward graphene-based solutions that allow seamless integration, high durability, and reduced power consumption. Moreover, as technology advances further toward ultra-thin, transparent electronic products, graphene is expected to play a key role in the development of futuristic consumer devices, which will continue to stimulate market demand.
Surge in Research and Development Initiatives and Investments
The global graphene electronics market is also experiencing substantial growth due to increased investments in research and development (R&D) by both public and private organizations. Governments worldwide recognize graphene’s potential as a game-changing material and are funding research programs to harness its properties for commercial applications. Notably, initiatives like the European Union’s Graphene Flagship aim to bridge the gap between laboratory research and commercial viability. This has led to advancements in scalable production techniques such as chemical vapor deposition (CVD) and liquid-phase exfoliation, which lower costs and enable large-scale manufacturing of graphene components.The sustained emphasis on research and development—supported by public-private collaboration—is anticipated to create a continuous flow of innovative applications that further accelerate market growth. These initiatives not only enhance the feasibility of integrating graphene into various industries but also stimulate ongoing innovation in electronic applications.
Growing Demand for Energy Storage and Sustainable Solutions
The surge in demand for energy-efficient and sustainable technologies is driving significant growth in the graphene electronics market. Graphene's high surface area, remarkable conductivity, and electrochemical properties make it highly desirable for energy storage applications, including batteries and supercapacitors. As the world transitions toward renewable energy and electric mobility solutions, graphene-based energy storage devices are emerging as key components that offer enhanced charge capacity, faster charge/discharge cycles, and improved energy density compared to conventional materials. The growing adoption of electric vehicles (EVs) and grid-level energy storage systems presents significant opportunities for graphene-enhanced batteries, which deliver better performance and longevity. In parallel, the increasing focus on sustainability in industries, combined with graphene’s potential for developing lightweight, energy-efficient components, contributes to market demand for environmentally friendly, advanced electronic solutions that help reduce carbon footprints. This trend aligns with the global push toward green technologies, reinforcing graphene's critical role in the next wave of electronics innovation.
Market Trends
Integration of Graphene in Next-Generation Flexible and Wearable Devices
One prominent trend shaping the global graphene electronics market is the integration of graphene into flexible and wearable electronic devices. Graphene’s unique combination of flexibility, high conductivity, and mechanical strength is driving its adoption in wearable electronics, such as smartwatches, fitness trackers, and healthcare monitoring devices. For instance, a recent study highlights the development of a graphene-based wearable sensor system that not only facilitates biometric authentication but also enables real-time health monitoring. This innovative system employs a combination of warm expanded graphite and polyvinylidene fluoride to create a flexible, conductive material that enhances signal quality and user comfort, making it ideal for integration into various wearable technologies. Additionally, graphene is widely used in flexible displays, touchscreens, and sensors. Consumer demand for smaller, more versatile, and efficient electronic products is steadily rising, and graphene’s exceptional properties enable manufacturers to design ultra-thin, lightweight, and durable devices that offer enhanced performance and comfort. Moreover, the versatility of graphene is further demonstrated through its application in health tracking devices and environmental sensors. Prototypes utilizing graphene have shown significant advancements in functionality, including the ability to monitor vital signs and environmental conditions seamlessly. These developments underscore the material's potential to redefine consumer electronics by enabling lightweight, durable, and efficient products that cater to the growing demand for advanced wearable technologies. Furthermore, advancements in the development of flexible batteries and energy storage systems using graphene are enabling new capabilities in wearable and portable electronics, further fueling this trend. As research and commercial applications progress, graphene-based wearable technologies are expected to redefine the consumer electronics landscape, fostering broader market expansion.
Increased Focus on Graphene-Enhanced Energy Storage Solutions
The global shift toward sustainable energy solutions is driving increased interest in graphene-enhanced energy storage applications, particularly in batteries and supercapacitors. For example, graphene-based supercapacitors are being explored for their ability to provide faster charge/discharge cycles and longer lifespans compared to traditional energy storage devices. This capability is particularly crucial in sectors like electric vehicles (EVs) and renewable energy, where high-performance energy solutions are essential for meeting consumer expectations for efficiency and sustainability. Graphene's superior electrical conductivity, high surface area, and ability to enhance charge storage capacity make it an attractive material for improving the performance of lithium-ion batteries, solid-state batteries, and capacitors.This trend is particularly evident in the electric vehicle (EV) and renewable energy sectors, where high-performance, fast-charging, and long-lasting energy storage solutions are in high demand. Industry players and research organizations are increasingly collaborating to enhance the scalability and commercial viability of graphene-based energy storage technologies, with a focus on achieving superior efficiency, reduced weight, and eco-friendly alternatives. This trend underscores the role of graphene as a catalyst for innovation and growth in energy storage markets globally.
Market Restraints and Challenges
High Production Costs and Scalability Issues
A major challenge impeding the widespread adoption of graphene electronics is the high cost and complexity associated with large-scale graphene production. While graphene exhibits exceptional properties, achieving consistent quality and scalability at economically feasible rates remains a significant barrier for many manufacturers. The synthesis processes, such as chemical vapor deposition (CVD), often involve expensive equipment and strict conditions that drive up production costs. Furthermore, variations in graphene quality, such as layer thickness, purity, and structure, can impact the performance of end-use applications, making it challenging for manufacturers to produce reliable and cost-effective graphene materials at scale. This limitation hampers the overall market penetration of graphene-based technologies, especially for cost-sensitive industries like consumer electronics and energy storage. Efforts are underway to develop cost-efficient and scalable production methods; however, these technological hurdles continue to pose constraints on broader market adoption.
Limited Commercialization and Standardization Challenges
Another key challenge for the global graphene electronics market is the limited commercialization of graphene-based products due to a lack of industry standards and regulatory frameworks. The market is still in a relatively nascent stage compared to conventional electronic materials, which presents hurdles in achieving widespread acceptance and integration into established manufacturing processes. The absence of standardized protocols for graphene synthesis, characterization, and integration into devices contributes to varying performance metrics and end-user expectations. This lack of consistency can deter potential investors and slow the adoption of graphene technologies. Additionally, establishing regulatory guidelines that ensure the safe handling, production, and application of graphene-based materials is essential for mitigating risks and fostering greater market trust. Addressing these standardization and commercialization challenges is critical for unlocking the full potential of graphene in electronic applications and ensuring its long-term viability across diverse sectors.
Market Segmentation Analysis
By Vertical Industry
Graphene's exceptional properties, such as high electrical conductivity and flexibility, drive its adoption across multiple industry verticals, including consumer electronics, where it enhances smartphones, tablets, wearable devices, and flexible displays to meet the demand for smaller, more efficient technology. In the automotive sector, graphene is utilized for improving battery performance, lightweighting, and developing advanced sensors, aligning with the growth of electric vehicles and vehicle efficiency enhancements. Healthcare benefits from graphene’s biocompatibility and high surface area, enabling its use in wearable medical devices, biosensors, drug delivery systems, and implants, advancing personalized care solutions. Industrial robotics leverage graphene-based sensors and electronic components for enhanced precision, durability, and responsiveness in automation systems. Aerospace and defense sectors utilize graphene for lightweight structural components, advanced coatings, and efficient electronic systems, improving performance and thermal management. Additionally, industries like energy, telecommunications, and environmental monitoring explore graphene applications to support advanced, sustainable functionalities.
By Product
Graphene's exceptional properties drive its use across various product segments. In displays, it enables flexible, lightweight, and energy-efficient screens, supporting next-generation devices. For memories, graphene enhances non-volatile memory devices like resistive random-access memory (RRAM) with faster speeds and lower energy consumption. Its integration into batteries boosts energy storage, fast-charging capabilities, and overall performance, crucial for consumer electronics, electric vehicles, and grid solutions. In solar cells, graphene's transparency and conductivity improve efficiency, flexibility, and cost-effectiveness in renewable energy applications. Graphene-based transistors and chips enhance data processing, reduce heat generation, and enable miniaturization, benefiting the semiconductor industry. Additionally, graphene's application extends to sensors, supercapacitors, and conductive inks, showcasing its broad potential in diverse electronic and industrial solutions.
Segments
Based on Industry Vertical
- Consumer Electronics
- Automotive
- Healthcare
- Industrial Robotics
- Aerospace and Défense
- Others
Based on Product
- Display
- Memories
- Batteries
- Solar Cell
- Integrated Circuits and Chips
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (35%):
North America is a leading market for graphene electronics, accounting for approximately 35% of the global market share. The region’s strong position is driven by extensive research and development activities, significant investments from both public and private entities, and the presence of major players such as IBM Corporation and Applied Graphene Materials. The United States, in particular, has robust academic and industrial research initiatives, supported by government grants aimed at commercializing graphene-based technologies. High demand for advanced materials in electronics, energy storage, and healthcare sectors further supports market growth.
Europe (30%):
Europe holds around 30% of the market share and remains at the forefront of graphene innovation, thanks to extensive government-funded programs like the Graphene Flagship. This initiative, the largest of its kind globally, focuses on developing practical applications for graphene and boosting industrial adoption. European countries such as Germany, the United Kingdom, and Sweden are prominent players in graphene R&D and commercialization efforts. The region’s focus on sustainable technologies, particularly in energy storage and lightweight materials for automotive and aerospace applications, bolsters the market’s growth trajectory.
Key players
- Grafen Chemical Industries Co. Ltd
- Graphene Square, Inc.
- Graphenea
- Graphene Frontiers LLC
- Versarien plc
- Graphene Platform Corporation
- Talga Group
- AMG Advanced Metallurgical Group N.V.
- NanoXplore Inc.
- First Graphene
Competitive Analysis
The global graphene electronics market is highly competitive, with a diverse range of established players and emerging startups driving innovation and commercialization. Companies such as Graphenea, Graphene Square, and Versarien plc are recognized for their focus on high-quality graphene materials, facilitating research and commercial applications in electronics. NanoXplore Inc. and First Graphene emphasize scalable production and cost-efficient solutions, aiming to bridge the gap between research and market adoption. Meanwhile, Talga Group and AMG Advanced Metallurgical Group N.V. leverage their expertise in raw material sourcing and processing. The competitive landscape is defined by ongoing R&D efforts, strategic collaborations, and advancements in graphene production techniques. Market players continuously innovate to differentiate their offerings, targeting sectors such as energy storage, sensors, and flexible electronics, positioning themselves for long-term growth in a rapidly evolving market.
Recent Developments
- In **January 2023**, Grafen Chemical announced the launch of a new line of graphene-based conductive inks designed for use in flexible electronics and printed circuit boards.
- In **February 2024**, Graphene Frontiers announced a partnership with a leading semiconductor manufacturer to develop graphene-based transistors that promise to significantly enhance speed and efficiency in electronic circuits.
- In **November 2022**, Versarien reported the successful development of a new graphene-enhanced composite material that improves the strength and durability of automotive parts, aiming for commercial applications in the automotive industry.
- In **August 2023**, Talga Group announced the completion of its pilot production facility for graphene-enhanced anode materials, which are expected to improve the performance of lithium-ion batteries significantly.
- In **December 2022**, AMG announced an acquisition of a graphene production facility to expand its capabilities in manufacturing high-quality graphene for various electronic applications.
- In **January 2024**, NanoXplore launched a new range of graphene-enhanced polymers designed for use in electronics, which offer improved conductivity and mechanical properties.
Market Concentration and Characteristics
The Global Graphene Electronics Market exhibits a moderate to high level of market concentration, with a mix of key established players and numerous emerging companies driving innovation. The market is characterized by rapid technological advancements, intense competition, and substantial investments in research and development to unlock new applications for graphene. While a few dominant players hold significant market shares due to their extensive R&D capabilities, large-scale production facilities, and established customer bases, smaller firms often lead niche innovations or specialize in specific graphene-based applications. The market is defined by its focus on high-performance materials, scalability challenges, and the pursuit of cost-effective manufacturing techniques to meet diverse industry demands, including consumer electronics, automotive, and energy sectors.
Report Coverage
The research report offers an in-depth analysis based on Industry Vertical, Product and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience growth as graphene continues to be incorporated into flexible displays, wearable devices, and next-generation electronic components, enhancing device performance and longevity.
- Graphene’s use in high-capacity batteries and supercapacitors will expand, addressing the rising demand for fast-charging, energy-efficient solutions in electric vehicles and renewable energy systems.
- R&D efforts will focus on overcoming scalability challenges and developing cost-effective manufacturing methods, accelerating the commercialization of graphene-based technologies.
- Graphene’s lightweight and conductive properties will drive increased adoption in the automotive industry, enhancing battery efficiency, safety features, and overall vehicle performance.
- Graphene’s biocompatibility and conductive capabilities will lead to more applications in biosensors, drug delivery systems, and medical devices, revolutionizing healthcare technology.
- As demand for innovative, flexible electronics grows, graphene-based materials will play a pivotal role in creating ultra-thin, durable, and high-performance devices.
- The market will see increased utilization of graphene for lightweight components, advanced coatings, and electronic systems, improving efficiency and durability in aerospace and defense applications.
- Graphene’s superior conductivity will support the development of high-speed, energy-efficient integrated circuits and chips, driving growth in computing and data processing markets.
- Graphene’s potential to create eco-friendly, high-performance solutions will align with global sustainability goals, boosting its adoption across industries.
- Industry players will collaborate to establish standards for graphene synthesis, integration, and commercialization, fostering market stability and encouraging broader adoption of graphene technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Graphene Electronics Market in 2023 and 2032?
What are the primary drivers for growth in the graphene electronics market?
Which industries are expected to see the most impact from graphene electronics?
Which regions lead the market for graphene electronics?
Why is graphene considered a transformative material for electronics?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Graphene Electronics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Graphene Electronics Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 582.96 million → 2032: USD 6,096.33 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Graphene Electronics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Graphene Electronics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Graphene Electronics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Graphene Electronics Market Drivers
- 3.3 Graphene Electronics Market Restraints & Challenges
- 3.4 Graphene Electronics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Graphene Electronics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Graphene Electronics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Graphene Electronics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Graphene Electronics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Graphene Electronics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Graphene Electronics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Graphene Electronics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Graphene Electronics Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Graphene Electronics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Graphene Electronics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Graphene Electronics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Graphene Electronics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Graphene Electronics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Graphene Electronics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Graphene Electronics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Graphene Electronics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Graphene Electronics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Graphene Electronics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Graphene Electronics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
