
Market Overview
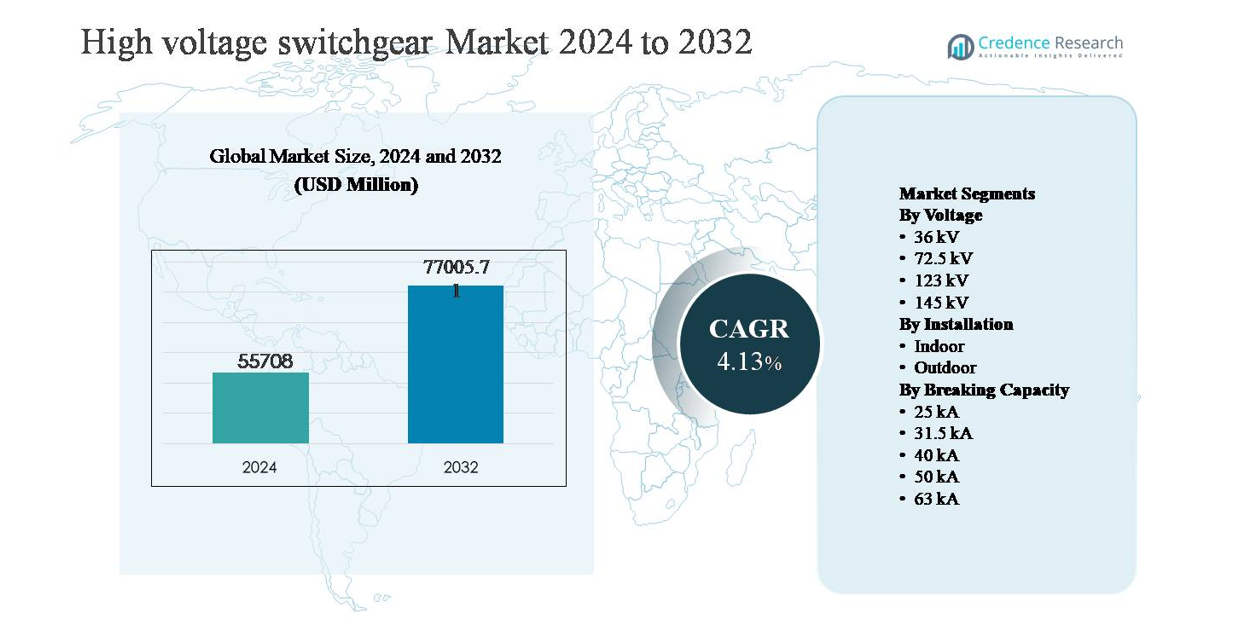
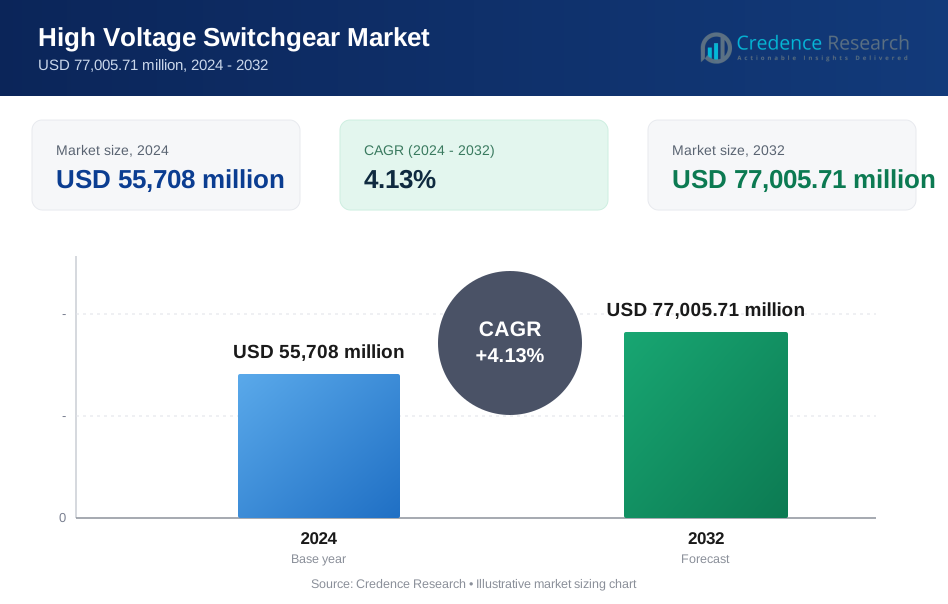
The high-voltage switchgear market was valued at USD 55,708 million in 2024 and is anticipated to reach USD 77,005.71 million by 2032, expanding at a compound annual growth rate (CAGR) of 4.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| High Voltage Switchgear Market Size 2024 | USD 55,708 million |
| High Voltage Switchgear Market, CAGR | 4.13% |
| High Voltage Switchgear Market Size 2032 | USD 77,005.71 million |
The high-voltage switchgear market is led by a group of globally established manufacturers with strong utility and industrial portfolios, including ABB, General Electric, Hitachi, Eaton, HD Hyundai Electric, Fuji Electric, Hyosung Heavy Industries, CG Power and Industrial Solutions, Bharat Heavy Electricals, and E + I Engineering. These companies compete through advanced high-voltage technologies, large-scale manufacturing capabilities, and long-term service offerings aligned with grid modernization and renewable integration needs. Asia Pacific is the leading region, accounting for approximately 38% of the global market share, driven by extensive transmission expansion, rising electricity demand, and large utility investments in China, India, and Southeast Asia. Strong project pipelines and government-backed grid development programs reinforce the region’s leadership position.
Market Insights
- The high-voltage switchgear market was valued at USD 55,708 million in 2024 and is projected to reach USD 77,005.71 million by 2032, growing at a CAGR of 4.13% during the forecast period, supported by sustained investments in transmission and grid infrastructure.
- Market growth is primarily driven by large-scale transmission network expansion, grid modernization, and rising integration of renewable energy, with the 145 kV voltage segment emerging as the dominant sub-segment due to its extensive use in transmission substations and interconnections.
- Key market trends include increasing adoption of digital and smart switchgear, demand for eco-efficient insulation technologies, and growing preference for high breaking capacity ratings, where 31.5 kA holds the largest segment share owing to its balance of performance and cost efficiency.
- The competitive landscape is characterized by global players focusing on technology innovation, localized manufacturing, and long-term service contracts to strengthen utility relationships and address evolving grid requirements.
- Regionally, Asia Pacific leads with around 38% market share, followed by North America at ~24% and Europe at ~22%, while outdoor installations dominate globally with nearly 60% share, reflecting utility-scale deployment patterns.
Market Segmentation Analysis:
By Voltage
The high-voltage switchgear market by voltage is led by the 145 kV segment, which accounts for an estimated around 35% of total market share. This dominance is driven by its widespread use in transmission substations, cross-border interconnections, and grid expansion projects supporting renewable energy integration. Utilities favor 145 kV systems for their optimal balance between capacity, footprint, and lifecycle cost in high-load networks. The 123 kV segment follows closely, supported by upgrades of aging transmission infrastructure, while 36 kV and 72.5 kV primarily serve sub-transmission and large industrial applications.
- "For instance, Hitachi Energy supplies its PASS M0hybrid switchgear platform rated up to 145 kV, with a typical short-circuit current withstand capability of 40 kA and compact bay widths below 4 m, enabling space-efficient transmission substations in dense grid corridors."
By Installation
By installation, the outdoor switchgear segment dominates with approximately 60% market share, driven by large-scale utility transmission and distribution projects. Outdoor installations are preferred for high-voltage applications due to easier scalability, higher voltage handling, and suitability for open substations in power generation and grid expansion projects. Rapid investments in renewable energy evacuation infrastructure and cross-country transmission lines further reinforce demand. Indoor switchgear continues to grow steadily, supported by urban substations, metro rail projects, and space-constrained industrial facilities requiring compact and environmentally controlled solutions.
- For instance, Siemens Energy supplies outdoor live-tank circuit breakers in the 3AP series rated up to 420 kV, with interrupting capacities of 63 kA and continuous current ratings reaching 4,000 A, enabling deployment in large transmission substations and interconnection nodes exposed to harsh environmental conditions.
By Breaking Capacity
In terms of breaking capacity, the 31.5 kA segment holds the leading position with about 32% market share, owing to its broad applicability across transmission and high-capacity distribution networks. Utilities widely deploy 31.5 kA switchgear as a standard rating that balances fault-handling capability with cost efficiency. The 40 kA segment is gaining traction in dense urban grids and renewable-heavy networks where higher fault levels are common. Lower ratings such as 25 kA serve legacy systems, while 50 kA and 63 kA cater to ultra-high fault current applications.
Key Growth Driver
Expansion and Modernization of Power Transmission Infrastructure
Large-scale expansion and modernization of power transmission networks remain a primary growth driver for the high-voltage switchgear market. Aging grid infrastructure across developed economies is driving utilities to replace legacy air-insulated systems with advanced, digitally enabled switchgear to improve reliability and fault management. Simultaneously, emerging economies are investing heavily in new transmission corridors to support rising electricity demand from urbanization, industrialization, and electrification programs. High-voltage switchgear plays a critical role in substations, interconnections, and grid reinforcement projects by enabling safe switching, isolation, and protection of high-capacity networks. Government-backed grid strengthening initiatives and cross-border interconnection projects further accelerate adoption, as utilities prioritize equipment that supports higher load capacities, long operational lifespans, and compliance with evolving grid codes.
- "For instance, GE Grid Solutions has delivered gas-insulated switchgear for 420 kV interconnection substations in Europe, with gas compartments designed to be highly resistant to leaks and intended for operating lifetimes exceeding 40 years. The equipment features mechanical endurance ratings above 10,000 operating cycles, enabling reliable operation under frequent switching and high-load conditions mandated by modern interconnected power systems."
Integration of Renewable Energy and Grid Stability Requirements
The rapid integration of renewable energy sources such as wind and solar is significantly driving demand for high-voltage switchgear. Renewable power plants often operate in remote locations and require long-distance transmission infrastructure, increasing the need for reliable high-voltage substations and switching equipment. High-voltage switchgear supports grid stability by managing variable power flows, isolating faults, and enabling rapid reconnection during disturbances. Utilities increasingly deploy advanced switchgear solutions to accommodate bidirectional power flows and higher short-circuit levels associated with renewable-heavy grids. As countries pursue aggressive decarbonization targets, investments in renewable energy evacuation systems, offshore wind connections, and hybrid substations continue to boost demand for high-voltage switchgear with enhanced performance and reliability.
- For instance, HD Hyundai Electric manufactures high-voltage gas-insulated and air-insulated switchgear rated up to 800 kV, with live-tank circuit breakers designed for continuous currents of 8,000 Aand short-circuit breaking capacities of 50 kA, supporting bulk power transfer from large onshore and offshore renewable hubs to national grids."
Rising Electrification of Industrial and Urban Infrastructure
Growing electrification across industrial facilities, transportation networks, and urban infrastructure is another key driver for the high-voltage switchgear market. Energy-intensive industries such as metals, chemicals, data centers, and manufacturing require high-capacity electrical systems to ensure uninterrupted operations and safety. Urban expansion, metro rail projects, electric vehicle charging infrastructure, and smart city developments further increase demand for high-voltage substations equipped with advanced switchgear. Utilities and industrial users prioritize switchgear systems that offer compact designs, high fault-handling capabilities, and integration with digital monitoring platforms. This trend supports sustained investment in high-voltage switchgear as electricity consumption patterns shift toward higher loads and more complex distribution architectures.
Key Trend & Opportunity
Adoption of Digital and Smart Switchgear Technologies
Digitalization is transforming the high-voltage switchgear market through the adoption of smart monitoring, protection, and control technologies. Modern switchgear increasingly incorporates sensors, intelligent electronic devices, and communication interfaces that enable real-time condition monitoring and predictive maintenance. These capabilities help utilities reduce unplanned outages, extend equipment lifespan, and optimize asset management strategies. The shift toward digital substations creates opportunities for manufacturers to offer value-added solutions that integrate seamlessly with supervisory control and data acquisition systems. As grid operators pursue automation and data-driven decision-making, demand for digitally enabled high-voltage switchgear is expected to accelerate, creating long-term opportunities beyond traditional hardware sales.
- For instance, Hyosung Heavy Industries supplies extra-high-voltage digital switchgear and circuit breakers equipped with condition monitoring systems that track operating time, contact wear, and mechanical performance, with breaker designs rated for interrupting capacities of 63 kA and mechanical endurance exceeding 10,000 operating cycles, supporting predictive maintenance in digitally managed transmission substations.
Transition Toward Environmentally Sustainable Switchgear Solutions
Environmental sustainability is emerging as a major trend and opportunity in the high-voltage switchgear market. Regulatory pressure to reduce greenhouse gas emissions is driving a gradual shift away from conventional insulating gases toward eco-efficient alternatives. Manufacturers are investing in research and development to commercialize switchgear technologies that lower environmental impact while maintaining high performance and safety standards. Utilities increasingly prefer sustainable solutions to meet environmental compliance requirements and corporate decarbonization goals. This transition opens opportunities for differentiated product offerings, particularly in regions with strict environmental regulations and strong commitments to sustainable power infrastructure development.
- "For instance, CG Power's medium-voltage vacuum circuit breaker (VCB) platforms are designed for mechanical endurance exceeding 10,000 operating cycles (meeting the IEC M2 classification) and are designed to support service lifetimes beyond 30 years, supporting long-term deployment in utility substations while reducing maintenance interventions and associated environmental impact."
Growth of Compact and Space-Efficient Substation Designs
The demand for compact and space-efficient substation solutions is increasing, particularly in densely populated urban areas. High land costs and limited space availability are pushing utilities to adopt switchgear systems that reduce footprint without compromising performance. Compact designs enable indoor and underground substations, supporting urban grid expansion and transportation infrastructure projects. This trend creates opportunities for manufacturers to develop modular, factory-assembled switchgear that simplifies installation and reduces project timelines. As cities continue to expand and electrification intensifies, space-efficient high-voltage switchgear solutions are expected to gain stronger traction.
Key Challenge
High Capital Costs and Complex Installation Requirements
High capital investment and complex installation processes present a significant challenge for the high-voltage switchgear market. The cost of equipment, civil works, and associated infrastructure can be substantial, particularly for large-scale transmission projects. Installation often requires specialized engineering expertise, extended commissioning timelines, and strict safety compliance, which can delay project execution. For utilities in cost-sensitive markets, budget constraints may limit the pace of grid upgrades and new substation development. These factors can slow adoption, especially in regions with limited financial resources or where power infrastructure investments compete with other public spending priorities.
Technical Complexity and Maintenance Demands
The increasing technical complexity of high-voltage switchgear systems poses ongoing challenges for utilities and industrial users. Advanced designs with higher fault ratings, digital components, and automation features require skilled personnel for operation and maintenance. Inadequate technical expertise can increase the risk of operational errors, equipment downtime, and safety incidents. Additionally, maintaining consistent performance over long service lifecycles demands rigorous inspection and asset management practices. In regions facing shortages of trained electrical professionals, these challenges can hinder efficient deployment and long-term reliability of high-voltage switchgear installations.
Regional Analysis
North America
North America accounts for approximately 24% of the global high-voltage switchgear market, supported by ongoing grid modernization and replacement of aging transmission infrastructure. Utilities across the United States and Canada are upgrading substations to enhance reliability, integrate renewable energy, and improve resilience against extreme weather events. Strong investments in wind and solar interconnections, data center power infrastructure, and cross-state transmission projects continue to drive demand. The region also benefits from advanced adoption of digital substations and strict safety standards, encouraging utilities to deploy high-performance, automated high-voltage switchgear across transmission and large industrial networks.
Europe
Europe represents around 22% of the global high-voltage switchgear market, driven by aggressive renewable energy integration and cross-border grid interconnections. The region’s transition toward low-carbon power systems requires extensive reinforcement of transmission networks, particularly for offshore wind and inter-regional electricity trade. Utilities across Western and Northern Europe prioritize advanced switchgear solutions to manage variable power flows and ensure grid stability. Additionally, stringent environmental regulations and sustainability targets are accelerating the adoption of eco-efficient switchgear technologies. Grid refurbishment projects in aging networks across Germany, France, and the U.K. further sustain market growth.
Asia Pacific
Asia Pacific dominates the high-voltage switchgear market with approximately 38% market share, reflecting rapid power infrastructure expansion across China, India, and Southeast Asia. Rising electricity demand from urbanization, industrial growth, and electrification initiatives is driving large-scale investments in transmission and distribution networks. Governments across the region are prioritizing grid expansion to support renewable energy deployment and rural electrification programs. High-capacity substations, long-distance transmission lines, and new industrial zones significantly boost demand. The region’s strong pipeline of utility-scale projects and manufacturing expansion positions Asia Pacific as the leading growth engine globally.
Latin America
Latin America holds about 8% of the global high-voltage switchgear market, supported by gradual expansion of transmission infrastructure and renewable energy integration. Countries such as Brazil, Chile, and Mexico continue to invest in grid reinforcement to connect hydropower, wind, and solar projects to national networks. Aging transmission assets and increasing electricity demand from mining and industrial sectors also contribute to market growth. However, investment cycles remain influenced by regulatory frameworks and public funding availability. Despite these challenges, long-term power sector reforms and renewable targets sustain steady demand for high-voltage switchgear solutions.
Middle East & Africa
The Middle East & Africa region accounts for approximately 8% of the global high-voltage switchgear market, driven by power generation expansion and grid development initiatives. Gulf countries are investing heavily in transmission networks to support urban growth, industrial diversification, and large-scale renewable energy projects. In Africa, electrification programs and cross-country transmission projects are gradually increasing demand. Utilities prioritize robust, high-capacity switchgear to operate under harsh environmental conditions. While infrastructure investment varies by country, long-term energy diversification strategies and population growth continue to create opportunities across the region.
Market Segmentations:
By Voltage
- 36 kV
- 72.5 kV
- 123 kV
- 145 kV
By Installation
- Indoor
- Outdoor
By Breaking Capacity
- 25 kA
- 31.5 kA
- 40 kA
- 50 kA
- 63 kA
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the high-voltage switchgear market is characterized by the presence of established global electrical equipment manufacturers and strong regional players competing on technology, reliability, and lifecycle performance. Leading companies focus on expanding their high-voltage portfolios through continuous innovation, particularly in digital monitoring, automation, and environmentally efficient insulation technologies. Strategic investments in manufacturing capacity and localized production enable suppliers to meet large utility tenders and regional grid standards. Companies also emphasize long-term service agreements, predictive maintenance, and retrofit solutions to strengthen customer relationships and recurring revenue streams. Partnerships with utilities, EPC contractors, and renewable energy developers remain central to securing large-scale transmission projects. Competitive differentiation increasingly centers on system integration capabilities, operational safety, compliance with evolving regulations, and the ability to deliver scalable solutions for renewable-heavy and high-load transmission networks.
Key Player Analysis
- General Electric
- Hitachi
- ABB
- Eaton
- HD Hyundai Electric
- Fuji Electric
- Hyosung Heavy Industries
- CG Power and Industrial Solutions
- Bharat Heavy Electricals
- E + I Engineering
Recent Developments
- In October 2025, Hitachi Energy introduced the PASS M00-Wind dual-breaker switchgear, engineered specifically for high-power offshore wind applications, enabling scalable deployment of next-generation turbines and supporting high-capacity renewable evacuation infrastructure.
- In July 2025, ABB announced it would supply its next-generation SF₆-free gas-insulated switchgear (SafeRing and SafePlus Air technologies) to E.ON in Germany. This deployment marks a shift toward lower-environmental-impact insulating technologies for utility grids.
- In February 2024, GE Vernova’s Grid Solutions business secured substantial orders from Power Grid Corporation of India (PGCIL) for the supply of 765 kV shunt reactors to support transmission projects that reinforce grid stability and facilitate renewable integration, strengthening grid infrastructure in key regional corridors.
Report Coverage
The research report offers an in-depth analysis based on Voltage, Installation, Breaking capacity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Grid modernization programs will continue to drive replacement of aging high-voltage switchgear across transmission networks.
- Renewable energy integration will increase demand for high-voltage switchgear with higher fault-handling and grid-stabilization capabilities.
- Utilities will accelerate adoption of digital and smart switchgear to enable predictive maintenance and real-time monitoring.
- Demand for eco-efficient and low-emission insulation technologies will rise in response to tightening environmental regulations.
- Outdoor high-voltage switchgear installations will remain dominant due to large-scale utility transmission projects.
- Compact and modular switchgear designs will gain traction in urban and space-constrained substations.
- Higher breaking capacity ratings will see increased adoption as grid fault levels continue to rise.
- Localization of manufacturing will expand to support regional grid standards and reduce supply chain risks.
- Long-term service contracts and retrofit solutions will grow in importance for revenue stability.
- Emerging economies will remain key growth engines due to sustained investments in power infrastructure expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion and Modernization of Power Transmission Infrastructure
Utilities are investing in new transmission corridors and upgrading aging grid assets to meet rising electricity demand and improve reliability. High-voltage switchgear is essential for safe switching, isolation, and protection in these expanded and modernized networks.
Integration of Renewable Energy and Grid Stability Requirements
The rapid growth of wind and solar power, often located far from demand centers, requires robust high-voltage switchgear for long-distance transmission and grid stability. Advanced switchgear enables utilities to manage variable power flows and higher short-circuit levels associated with renewable-heavy grids.
Rising Electrification of Industrial and Urban Infrastructure
Industrial facilities, urban expansion, and transportation electrification are driving demand for high-capacity electrical systems. High-voltage switchgear is critical for supporting uninterrupted operations, safety, and the integration of new loads in these sectors.
Adoption of Digital and Smart Switchgear Technologies
Utilities are increasingly deploying digital switchgear with real-time monitoring and predictive maintenance capabilities to reduce outages and optimize asset management. This trend is accelerating as grid operators pursue automation and data-driven decision-making.
Transition Toward Environmentally Sustainable Switchgear Solutions
Regulatory pressure to reduce greenhouse gas emissions is prompting a shift toward eco-efficient insulation technologies in high-voltage switchgear. Utilities and manufacturers are investing in sustainable solutions to meet environmental compliance and corporate decarbonization goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for High voltage switchgear, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the High voltage switchgear projected to grow between 2024 and 2032?
What factors are driving the growth of the high-voltage switchgear market?
How does high-voltage switchgear contribute to the power infrastructure amidst the surge in global energy consumption?
What are the key challenges hindering the widespread adoption of high-voltage switchgear systems?
How is the market responding to environmental concerns, and what eco-friendly trends are emerging?
Who are the leading companies in the High voltage switchgear market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Voltage
- 1.2.1 36 kV
- 1.2.2 72.5 kV
- 1.2.3 123 kV
- 1.2.4 145 kV
- 1.3 By Installation
- 1.3.1 Indoor
- 1.3.2 Outdoor
- 1.4 By Breaking Capacity
- 1.4.1 25 kA
- 1.4.2 31.5 kA
- 1.4.3 40 kA
- 1.4.4 50 kA
- 1.4.5 63 kA
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 55,708 million → 2032: USD 77,005.71 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global High Voltage Switchgear Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global High Voltage Switchgear Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global High Voltage Switchgear Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global High Voltage Switchgear Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global High Voltage Switchgear Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global High Voltage Switchgear Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global High Voltage Switchgear Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global High Voltage Switchgear Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 55,708 million → 2032: USD 77,005.71 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global High Voltage Switchgear Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Voltage - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 36 kV
- 12.3.7.2 72.5 kV
- 12.3.7.3 123 kV
- 12.3.7.4 145 kV
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Installation - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Indoor
- 12.4.7.2 Outdoor
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Breaking Capacity - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 25 kA
- 12.5.7.2 31.5 kA
- 12.5.7.3 40 kA
- 12.5.7.4 50 kA
- 12.5.7.5 63 kA
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global High Voltage Switchgear Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global High Voltage Switchgear Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global High Voltage Switchgear Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 ABB
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 General Electric
- 17.4 Hitachi
- 17.5 Eaton
- 17.6 HD Hyundai Electric
- 17.7 Fuji Electric
- 17.8 Hyosung Heavy Industries
- 17.9 CG Power and Industrial Solutions
- 17.10 Bharat Heavy Electricals
- 17.11 E + I Engineering
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

