
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Hormone Sensitive Prostate Cancer Market Size 2024 | USD 12442.5 Million |
| Hormone Sensitive Prostate Cancer Market, CAGR | 7.4% |
| Hormone Sensitive Prostate Cancer Market Size 2032 | USD 22026.31 Million |
Market Overview:
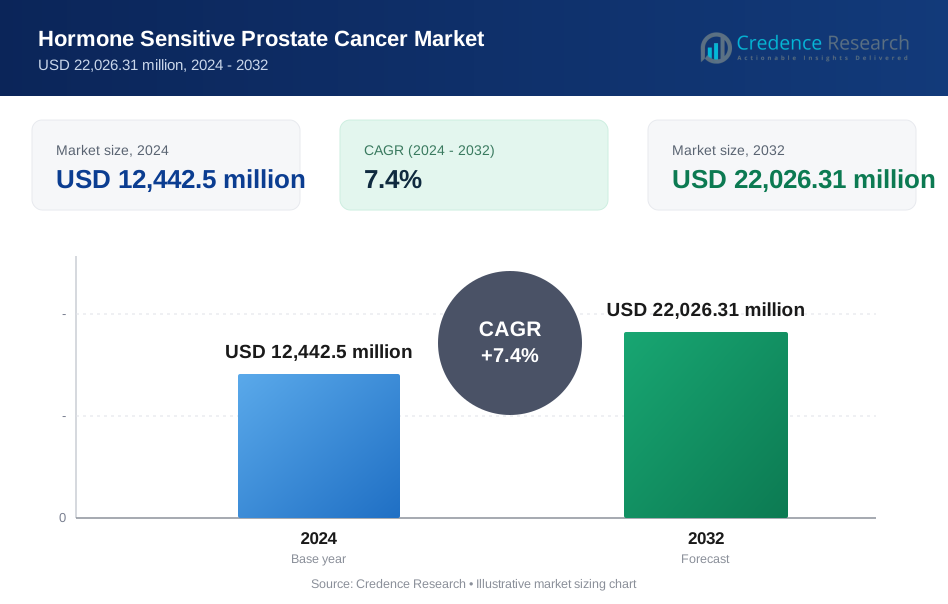
The Hormone Sensitive Prostate Cancer Market is projected to grow from USD 12442.5 million in 2024 to an estimated USD 22026.31 million by 2032, with a compound annual growth rate (CAGR) of 7.4% from 2024 to 2032.
Market drivers include advancements in precision medicine and the development of targeted therapies that improve treatment outcomes for hormone-sensitive prostate cancer. Rising awareness campaigns by healthcare organizations and governments have significantly contributed to the early detection and timely treatment of prostate cancer. Additionally, the integration of advanced diagnostic technologies, such as PSA tests and imaging tools, enables better patient stratification and monitoring. Pharmaceutical companies are increasingly investing in research and development to introduce combination therapies, enhancing efficacy and patient survival rates. The aging global population, which is particularly vulnerable to prostate cancer, is another critical driver, amplifying demand for effective treatment modalities. The market is also witnessing a surge in clinical trials and approvals of next-generation hormone therapies.
From a regional perspective, North America dominates the HSPC market, accounting for the largest share due to high healthcare expenditure, strong infrastructure, and the prevalence of advanced treatment options. Europe follows, driven by government-backed healthcare systems and rising awareness of prostate cancer screening programs. The Asia-Pacific region is projected to experience the fastest growth owing to an increasing patient population, improved access to healthcare services, and rising investments in healthcare infrastructure. Countries like China and India are emerging as lucrative markets, supported by economic growth and heightened focus on oncology care. Meanwhile, Latin America and the Middle East are also experiencing moderate growth, facilitated by improving healthcare systems and awareness initiatives.
Market Insights:
- The Hormone Sensitive Prostate Cancer Market is projected to grow from USD 12,442.5 million in 2024 to USD 22,026.31 million by 2032, with a CAGR of 4% during the forecast period.
- Advancements in hormonal therapies like abiraterone acetate and enzalutamide, combined with androgen deprivation therapy (ADT), are improving survival rates and expanding the therapeutic landscape.
- Rising awareness campaigns, such as PSA screening initiatives, have resulted in a 20% increase in early detection globally, enhancing treatment outcomes.
- North America holds the largest market share (40%), driven by robust healthcare infrastructure, high adoption of next-generation therapies, and strong insurance coverage.
- The Asia-Pacific region is the fastest-growing market, witnessing a 5% annual increase in prostate cancer incidence and significant growth in healthcare access and investments.
- High treatment costs and therapy resistance remain critical challenges, with advanced therapies often inaccessible in low-income regions due to premium pricing and healthcare disparities.
- Regulatory and reimbursement hurdles, alongside complex approval pathways, limit the market entry of novel therapies and create barriers for equitable treatment availability globally.
Market Drivers:
Advancements in Hormonal Therapies
The continuous development of innovative hormonal therapies is a primary driver for the growth of the hormone-sensitive prostate cancer (HSPC) market. Traditional androgen deprivation therapy (ADT) has seen significant enhancements, including the integration of next-generation hormone therapies such as abiraterone acetate and enzalutamide, which target androgen receptor pathways more effectively. For instance, enzalutamide has shown a 55% reduction in the risk of death or visible signs of tumor progression when combined with talazoparib in patients with BRCA mutations. These advancements have led to improved survival rates and better patient outcomes, encouraging broader adoption. The introduction of combination regimens involving ADT and novel agents has further increased treatment efficacy, expanding the therapeutic landscape for HSPC.
Rising Incidence of Prostate Cancer
The growing prevalence of prostate cancer globally is significantly impacting the demand for effective treatment solutions in the HSPC market. According to global health statistics, prostate cancer remains one of the most common cancers among men, particularly in aging populations. According to the Global Cancer Observatory, there were 1,467,854 new cases of prostate cancer in 2022. Factors such as lifestyle changes, increased life expectancy, and improved screening techniques contribute to higher diagnosis rates. This surge in cases has created a robust need for advanced hormonal therapies, fostering continuous research and development in this domain.
Increased Awareness and Early Diagnosis
Awareness campaigns by governments and healthcare organizations have played a crucial role in improving early detection of prostate cancer. Programs promoting regular screening, such as PSA (prostate-specific antigen) testing, have resulted in timely diagnosis and treatment, boosting the market for HSPC therapies. For instance, the "Know Your Numbers" campaign by the Prostate Cancer Foundation encourages men to learn about their PSA levels, significantly increasing early detection rates. Early intervention not only improves patient prognosis but also drives the adoption of innovative therapies tailored to the initial stages of the disease. The integration of advanced diagnostic imaging technologies has further complemented these efforts, enabling accurate patient stratification and personalized treatment plans.
Expanding Research and Development Investments
The HSPC market is witnessing substantial investment in research and development activities by pharmaceutical companies and academic institutions. These efforts focus on identifying novel therapeutic targets, enhancing the efficacy of existing treatments, and minimizing side effects. Clinical trials evaluating new drug candidates and combination therapies have gained momentum, supported by regulatory frameworks that prioritize oncology innovation. For example, the VISION trial involving 177 Lu-PSMA-617 showed significant efficacy in slowing the progression of advanced prostate cancer. Moreover, partnerships between biopharma companies and research organizations have accelerated the development pipeline, ensuring a steady influx of advanced therapies into the market. Such advancements are not only improving patient outcomes but also positioning the HSPC market as a dynamic and growth-oriented segment within the broader oncology field.
Market Trends:
Integration of Combination Therapies in Standard Treatment Protocols
A significant trend in the hormone-sensitive prostate cancer (HSPC) market is the growing preference for combination therapies as part of standard treatment protocols. Recent clinical studies have demonstrated that combining androgen deprivation therapy (ADT) with novel agents such as abiraterone acetate or apalutamide enhances progression-free survival and reduces mortality rates. For instance, the TITAN trial showed that adding apalutamide to ADT improved overall survival by 33% in patients with metastatic HSPC. This trend reflects a shift toward more aggressive initial treatment approaches, aiming to delay disease progression and improve patient quality of life. As healthcare professionals increasingly adopt these combination regimens, pharmaceutical companies are focusing on developing multi-drug solutions tailored for HSPC patients.
Emergence of Biomarker-Driven Treatment Strategies
Biomarker-driven treatment strategies are gaining traction in the HSPC market, reflecting the industry’s shift toward precision medicine. Advances in genetic and molecular profiling are enabling clinicians to identify specific biomarkers that predict disease behavior and therapeutic response. For instance, the identification of androgen receptor splice variant-7 (AR-V7) has provided insights into treatment resistance, paving the way for targeted interventions. The integration of biomarker testing into routine clinical practice not only optimizes therapy selection but also reduces unnecessary side effects, aligning with the broader trend of personalized oncology care.
Adoption of Digital Health Technologies
Digital health technologies are transforming the HSPC market by enhancing patient monitoring, treatment adherence, and outcome assessment. Remote monitoring tools, including wearable devices and mobile applications, enable real-time tracking of patient health metrics such as PSA levels and treatment side effects. For example, the use of the Apple Watch for continuous heart rate monitoring has been integrated into clinical trials to assess cardiovascular health in prostate cancer patients. Telemedicine platforms have also gained prominence, facilitating remote consultations and expanding access to specialized care in underserved regions. These digital solutions are improving patient engagement and fostering a data-driven approach to prostate cancer management, aligning with the healthcare sector's broader digital transformation.
Geographic Expansion of Advanced Therapies
The geographic expansion of advanced HSPC therapies is another noteworthy trend, driven by increasing healthcare investments in emerging markets. Countries in the Asia-Pacific and Latin American regions are witnessing growing adoption of novel treatments due to rising prostate cancer awareness and improving healthcare infrastructure. Governments and private entities in these regions are prioritizing the availability of cutting-edge therapies, supported by collaborations with global pharmaceutical companies. For example, regulatory approvals for advanced hormone therapies in countries like India and Brazil have accelerated their accessibility, making them a viable option for a broader patient base. This trend underscores the global effort to standardize cancer care and address disparities in treatment availability.
Market Challenges Analysis:
High Treatment Costs
The significant cost associated with advanced therapies for hormone-sensitive prostate cancer (HSPC) is a major restraint for market growth. Novel hormonal agents, combination therapies, and precision medicine approaches often come with premium pricing, making them inaccessible to many patients, particularly in low- and middle-income countries. Even in developed regions, healthcare systems face budgetary constraints that limit the widespread adoption of cutting-edge treatments. The high costs of long-term care, including follow-ups and monitoring, further exacerbate the economic burden on patients and healthcare providers.
Side Effects and Therapy Resistance
Another challenge facing the HSPC market is the prevalence of side effects and the development of resistance to hormonal therapies. Treatments like androgen deprivation therapy (ADT) can lead to adverse effects such as bone density loss, cardiovascular risks, and metabolic changes, impacting patient compliance. Moreover, resistance to existing therapies remains a significant clinical challenge, with many patients progressing to castration-resistant prostate cancer (CRPC) over time. This highlights an unmet need for therapies that are not only effective but also minimize adverse effects and delay resistance.
Limited Awareness and Diagnosis in Emerging Markets
Despite advancements in treatment, limited awareness and late diagnosis in emerging markets remain significant barriers. Many patients in these regions lack access to regular screening programs, such as PSA testing, due to inadequate healthcare infrastructure and socioeconomic factors. As a result, prostate cancer is often diagnosed at advanced stages, reducing the effectiveness of hormone-sensitive therapies. Efforts to enhance awareness and improve diagnostic infrastructure are crucial to overcoming these challenges and expanding the market.
Regulatory and Reimbursement Hurdles
Complex regulatory pathways and inconsistent reimbursement policies present further obstacles for market players. Stringent approval processes for new therapies can delay market entry, while inconsistent insurance coverage and reimbursement policies create uncertainty for both patients and providers. Addressing these issues is critical for ensuring the equitable availability of advanced HSPC treatments.
Market Opportunities:
The hormone-sensitive prostate cancer (HSPC) market presents significant growth opportunities driven by advancements in precision medicine and increasing global awareness of prostate cancer management. With the rising prevalence of prostate cancer, especially among aging populations, the demand for innovative treatment options is expanding. The integration of next-generation hormonal therapies, coupled with combination regimens, offers improved clinical outcomes and longer progression-free survival, making this a lucrative segment for pharmaceutical and biotechnology companies. Additionally, the growing focus on biomarker-driven therapies to personalize treatment plans aligns with the broader trend toward precision oncology, creating pathways for the development of targeted and efficacious solutions. Emerging technologies such as liquid biopsies and genetic profiling provide an added layer of opportunity, enabling early diagnosis and optimized therapy selection.
Expanding healthcare infrastructure in emerging markets further underscores the untapped potential of the HSPC market. Regions such as Asia-Pacific and Latin America are witnessing significant investments in oncology care, supported by government initiatives to improve access to advanced therapies. Increasing awareness campaigns and the adoption of telemedicine are enhancing early diagnosis and treatment, particularly in rural and underserved areas. Partnerships between global pharmaceutical firms and local healthcare providers are also facilitating the rapid introduction of cutting-edge therapies in these regions. As the demand for equitable and high-quality prostate cancer care continues to grow, companies that innovate while addressing affordability and accessibility stand to gain a competitive edge in this dynamic and evolving market.
Market Segmentation Analysis:
The Hormone Sensitive Prostate Cancer (HSPC) Market is segmented based on treatment type, diagnosis method, stage of cancer, patient age group, and region. These segments enable a comprehensive understanding of the market dynamics and targeted growth strategies.
By Treatment Type, hormonal therapy dominates the market due to its widespread adoption as the primary treatment for HSPC. Chemotherapy and radiation therapy are utilized in advanced or resistant cases, while immunotherapy is emerging as a promising adjunct in personalized treatment regimens.
By Diagnosis Method, imaging tests, including MRI and CT scans, hold the largest share due to their accuracy in staging cancer. Biopsy remains a critical diagnostic tool, while blood and urine tests, including PSA levels, are increasingly used for early detection and monitoring.
By Stage of Cancer, localized HSPC represents the largest segment due to the high diagnosis rate at early stages. Locally advanced and metastatic stages are also significant, reflecting a need for advanced therapies as the disease progresses.
By Patient Age Group, individuals aged over 65 account for the largest share, driven by the higher prevalence of prostate cancer in older populations. The 50–65 age group follows, reflecting improved screening and early detection.
Segmentation:
By Treatment Type
- Hormonal Therapy
- Chemotherapy
- Radiation Therapy
- Immunotherapy
By Diagnosis Method
- Biopsy
- Imaging Tests
- Blood Tests
- Urine Tests
By Stage of Cancer
- Localized
- Locally Advanced
- Metastatic
By Patient Age Group
- Under 50
- 50-65
- Over 65
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America dominates the hormone-sensitive prostate cancer (HSPC) market, holding the largest market share at approximately 40% in 2023. The region sees an annual prostate cancer incidence rate of over 248,000 cases in the United States alone, contributing significantly to the demand for advanced therapies. The adoption rate of next-generation hormone therapies, such as abiraterone and enzalutamide, has risen by over 15% annually due to their proven efficacy in extending progression-free survival. Additionally, over 85% of healthcare facilities in the U.S. offer access to comprehensive prostate cancer care, supported by strong insurance coverage for advanced treatments. Awareness initiatives like the Movember campaign have achieved notable success, raising millions of dollars annually and increasing participation in early screening by 20% over the past five years.
Europe
Europe accounts for nearly 30% of the global HSPC market, supported by universal healthcare systems and well-established cancer care frameworks. The region records approximately 450,000 new prostate cancer diagnoses annually, with Germany, the UK, and France contributing to more than 60% of these cases. Prostate-specific antigen (PSA) screening uptake has increased by 10% in the last three years due to government-backed awareness campaigns. Furthermore, more than 70% of oncology centers in Europe have adopted next-generation hormonal agents as part of their standard treatment protocols. Research funding in the European Union for oncology innovations exceeds €2 billion annually, driving advancements in biomarker-based treatments and combination therapies.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the HSPC market, capturing a market share of around 20% in 2023. Prostate cancer incidence in this region has increased by 5% annually, with China and India accounting for over 40% of the regional cases. Improved healthcare access has led to a 30% rise in prostate cancer screenings in urban areas across Asia in recent years. Japan, known for its aging population, has seen a 25% growth in hormone-sensitive prostate cancer diagnoses among men aged 60 and above. Digital health platforms have facilitated remote monitoring for over 1 million prostate cancer patients, improving adherence to treatment regimens. Regional governments, such as India’s healthcare schemes, have allocated substantial budgets to oncology care, contributing to increased treatment adoption.
Rest of the World (RoW)
The Rest of the World, including Latin America, the Middle East, and Africa, accounts for approximately 10% of the HSPC market. Latin America, with over 100,000 annual prostate cancer cases, has seen a 15% increase in access to advanced hormonal therapies due to improved healthcare initiatives. In the Middle East, government investments in oncology have driven a 12% annual rise in prostate cancer screenings. South Africa leads in sub-Saharan Africa, with nearly 50% of urban healthcare facilities now offering early prostate cancer detection services. Collaborations between global pharmaceutical companies and local governments are expanding access to therapies, particularly in underserved rural areas.
Key Player Analysis:
- AbbVie
- Amgen
- AstraZeneca
- Bayer
- BristolMyers Squibb
- Eli Lilly
- Gilead Sciences
- GSK
- Ipsen
- Johnson and Johnson
- Merck
- Novartis
- Pfizer
- Sanofi
- Teva Pharmaceuticals
Competitive Analysis:
The hormone-sensitive prostate cancer (HSPC) market is characterized by intense competition among leading pharmaceutical companies, driven by the development of innovative therapies and robust research pipelines. Key players such as Pfizer Inc., Johnson & Johnson, Astellas Pharma Inc., and Novartis AG dominate the market, offering advanced hormonal therapies like enzalutamide, abiraterone acetate, and apalutamide. These companies leverage their strong R&D capabilities and extensive global reach to maintain competitive advantages. For instance, Novartis AG is conducting a phase III trial for Pluvicto (lutetium Lu 177 vipivotide tetraxetan) in hormone-sensitive prostate cancer patients with up to five oligometastases. Collaboration and partnerships are prevalent, with firms joining forces to accelerate drug development and improve market penetration in emerging regions. Additionally, many companies are focusing on precision medicine, incorporating biomarker-driven therapies to enhance treatment outcomes. The market also sees growing competition from emerging biotech firms, introducing novel therapeutic options. Regulatory approvals and clinical trial successes remain critical factors influencing competitive dynamics, making the market highly dynamic and innovation-driven.
Recent Developments:
- In August 2023, Eli Lilly completed a series of strategic acquisitions, including Versanis Bio, Sigilon Therapeutics, and DICE Therapeutics. These acquisitions strengthened their position in obesity treatment, autoimmune diseases, and chronic conditions.
- In July 2023, Gilead Sciences extended its technological capabilities through an $800 million service agreement with Cognizant, focusing on digital transformation and IT infrastructure enhancement.
- In October 2023, GSK achieved a significant milestone by launching Arexvy, becoming the first company globally to introduce a vaccine for respiratory syncytial virus (RSV).
- In March 2024, Johnson & Johnson expanded its biologics capabilities through the $2.0 billion acquisition of Ambrx Biopharma, strengthening their position in next-generation antibody-drug conjugates.
- In October 2023, Merck formed a groundbreaking collaboration with Daiichi Sankyo, focusing on three DXd antibody-drug conjugate candidates. This partnership aims to advance cancer treatment options.
- In August 2023, Novartis enhanced its kidney disease portfolio by acquiring Chinook Therapeutics in a deal worth up to $3.5 billion, strengthening their presence in rare kidney disease treatments.
Market Concentration & Characteristics:
The hormone-sensitive prostate cancer (HSPC) market exhibits a moderate to high level of concentration, with a few dominant players such as Pfizer Inc., Johnson & Johnson, Novartis AG, and Astellas Pharma Inc. holding significant market shares. These companies benefit from established portfolios of next-generation hormonal therapies and strong global distribution networks. The market’s competitive landscape is further characterized by frequent innovations, driven by substantial investments in research and development. Smaller biotech firms are emerging with novel therapeutic approaches, contributing to a dynamic and innovation-centric environment. The market is highly regulated, with stringent approval processes shaping the entry of new drugs. Collaboration between pharmaceutical giants and research organizations is a defining characteristic, ensuring continuous advancements in treatment protocols. Furthermore, geographic disparities in access and adoption rates underscore the need for equitable distribution, with emerging regions presenting untapped growth opportunities for key players.
Report Coverage:
The research report offers an in-depth analysis based on By Treatment Type, By Diagnosis Method, By Stage of Cancer and By Patient Age Group. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of combination therapies is expected to enhance patient outcomes and drive market growth.
- Advancements in biomarker-driven treatments will enable more personalized and effective therapeutic options.
- Emerging markets in Asia-Pacific and Latin America will witness rapid growth due to improving healthcare infrastructure and awareness.
- Integration of digital health tools, such as remote monitoring and telemedicine, will expand access to care and improve treatment adherence.
- Continuous research and development investments will lead to the introduction of next-generation hormonal agents.
- Expanding regulatory approvals for novel therapies will accelerate their availability across diverse regions.
- Partnerships between global pharmaceutical companies and local providers will bridge gaps in affordability and accessibility.
- Increasing use of genetic profiling and precision medicine will streamline patient stratification and optimize treatment plans.
- Rising prevalence of prostate cancer, particularly in aging populations, will sustain demand for innovative solutions.
- Focus on reducing side effects and therapy resistance will drive the development of safer and more effective treatments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Hormonal Therapies
Continuous innovation in hormonal therapies, such as the development of next-generation agents like abiraterone acetate and enzalutamide, has significantly improved survival rates and expanded treatment options for hormone-sensitive prostate cancer patients.
Rising Incidence and Early Detection
The global increase in prostate cancer cases, particularly among aging populations, combined with heightened awareness and widespread PSA screening, has led to earlier diagnosis and a greater pool of patients eligible for hormone-sensitive treatments.
Integration of Precision Medicine and Biomarker-Driven Approaches
The adoption of biomarker-driven strategies and genetic profiling enables more personalized treatment plans, improving therapeutic outcomes and reducing unnecessary side effects, which drives demand for advanced therapies.
Expanding Access and Healthcare Infrastructure in Emerging Markets
Significant investments in healthcare infrastructure and awareness campaigns in Asia-Pacific and Latin America are increasing access to advanced therapies, fueling rapid market growth in these regions.
Increased R&D and Combination Therapy Development
Pharmaceutical companies are investing heavily in research and clinical trials to develop combination regimens and novel agents, enhancing efficacy and addressing therapy resistance, which propels market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Hormone Sensitive Prostate Cancer Market by 2032?
What is the estimated CAGR for the market during 2024–2032?
What are the major drivers of the market?
Which region dominates the Hormone Sensitive Prostate Cancer Market?
What are the main challenges facing the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Treatment Type
- 1.2.1 Hormonal Therapy
- 1.2.2 Chemotherapy
- 1.2.3 Radiation Therapy
- 1.2.4 Immunotherapy
- 1.3 By Stage of Cancer
- 1.3.1 Localized
- 1.3.2 Locally Advanced
- 1.3.3 Metastatic
- 1.4 By Diagnosis Method
- 1.4.1 Biopsy
- 1.4.2 Imaging Tests
- 1.4.3 Blood Tests
- 1.4.4 Urine Tests
- 1.5 By Patient Age Group
- 1.5.1 Under 50
- 1.5.2 50-65
- 1.5.3 Over 65
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,442.5 million → 2032: USD 22,026.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hormone Sensitive Prostate Cancer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hormone Sensitive Prostate Cancer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hormone Sensitive Prostate Cancer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hormone Sensitive Prostate Cancer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hormone Sensitive Prostate Cancer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hormone Sensitive Prostate Cancer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hormone Sensitive Prostate Cancer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hormone Sensitive Prostate Cancer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,442.5 million → 2032: USD 22,026.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hormone Sensitive Prostate Cancer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Treatment Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hormonal Therapy
- 12.3.7.2 Chemotherapy
- 12.3.7.3 Radiation Therapy
- 12.3.7.4 Immunotherapy
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Stage of Cancer - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Localized
- 12.4.7.2 Locally Advanced
- 12.4.7.3 Metastatic
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Diagnosis Method - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Biopsy
- 12.5.7.2 Imaging Tests
- 12.5.7.3 Blood Tests
- 12.5.7.4 Urine Tests
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Patient Age Group - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Under 50
- 12.6.7.2 50-65
- 12.6.7.3 Over 65
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hormone Sensitive Prostate Cancer Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hormone Sensitive Prostate Cancer Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hormone Sensitive Prostate Cancer Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pfizer
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Johnson & Johnson
- 17.4 Novartis
- 17.5 AstraZeneca
- 17.6 Bayer
- 17.7 Amgen
- 17.8 Eli Lilly
- 17.9 GSK
- 17.10 Sanofi
- 17.11 Merck
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
