
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| In-Vitro Fertilization Market Size 2024 | USD 26,001.26 million |
| In-Vitro Fertilization Market, CAGR | 6.52% |
| In-Vitro Fertilization MarketSize 2032 | USD 42,986.00 million |
Market Overview:
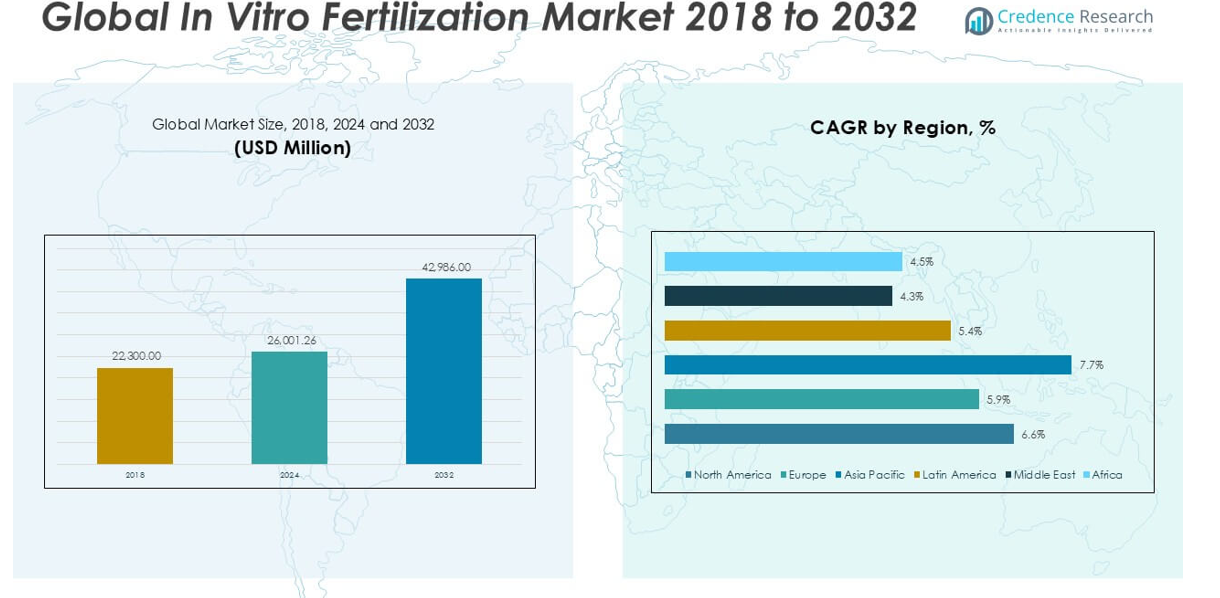
The In Vitro Fertilization market size was valued at USD 22,300.00 million in 2018, reached USD 26,001.26 million in 2024, and is anticipated to reach USD 42,986.00 million by 2032, at a CAGR of 6.52% during the forecast period.
The In Vitro Fertilization (IVF) market is led by key players such as Bayer AG, Cook Medical LLC, EMD Serono, Inc., Ferring B.V., FUJIFILM Irvine Scientific, Genea Biomedx, Merck KGaA, The Cooper Companies, Inc., Thermo Fisher Scientific, Inc., and Vitrolife. These companies drive market growth through technological advancements, extensive product portfolios, and global expansion strategies. North America and Europe are the leading regions, with Europe holding the largest market share of approximately 37.7% due to supportive regulations, public funding, and the presence of well-established fertility clinics. North America closely follows, supported by advanced healthcare infrastructure and rising infertility rates.
Market Insights
- The In Vitro Fertilization (IVF) market was valued at USD 22,300.00 million in 2018, reached USD 26,001.26 million in 2024, and is expected to reach USD 42,986.00 million by 2032, growing at a CAGR of 6.52%.
- Rising infertility rates, lifestyle changes, delayed parenthood, and increased awareness of assisted reproductive technologies are driving market growth.
- The market is witnessing trends such as growing adoption of advanced IVF equipment, increasing preference for frozen embryo transfers, and the rising popularity of fertility preservation.
- The competitive landscape features key players like Bayer AG, Merck KGaA, Thermo Fisher Scientific, and Vitrolife, with Europe holding the largest regional share at around 37.7% and the equipment segment leading among instruments.
- High treatment costs, limited access in low-income regions, and ethical concerns regarding embryo handling are key market restraints affecting broader adoption.
Market Segmentation Analysis:
By Instrument:
In the In Vitro Fertilization (IVF) market, the equipment segment dominates with a significant market share, driven by the increasing adoption of advanced technologies such as micromanipulator systems and incubators that enhance embryo handling and culture conditions. Within equipment, sperm analyzer systems and imaging systems are gaining preference for improving diagnostic precision. Culture media, particularly embryo culture media and cryopreservation media, also capture substantial demand due to their critical role in embryo viability and success rates. The rising demand for disposable devices supports the need for contamination-free processes, further contributing to market growth across IVF laboratories and clinics.
- For instance, Vitrolife’s EmbryoScope+ time-lapse system has been installed in over 950 clinics worldwide, enabling continuous embryo monitoring with reduced handling.
By Procedure Type
The fresh non-donor procedure type holds the largest market share in the In Vitro Fertilization market, primarily due to its higher success rates and preference among patients using their own gametes. This segment benefits from improved embryo implantation outcomes and reduced ethical concerns compared to donor procedures. However, the frozen donor and frozen non-donor segments are expanding steadily, supported by advancements in cryopreservation techniques that enhance embryo survival rates post-thaw. Increasing patient awareness and the convenience of scheduling embryo transfers are further driving the demand for frozen procedures across fertility clinics.
- For instance, CooperSurgical’s CryoKit system supports over 2,000 successful embryo freezing cycles annually across multiple fertility centers in the United States.
By Providers
Fertility clinics lead the provider segment in the In Vitro Fertilization market, accounting for the majority of procedures performed globally. These clinics offer specialized IVF services, advanced equipment, and tailored treatment plans, attracting a large patient base. The growth of fertility clinics is supported by rising infertility rates, increasing medical tourism, and improved success rates of assisted reproductive technologies. Hospitals and other settings hold a smaller but growing share, especially in developing regions where access to specialized clinics is limited. Their growth is driven by the integration of reproductive services within broader healthcare facilities.
Market Overview
Rising Infertility Rates Globally
The increasing prevalence of infertility is a major growth driver for the In Vitro Fertilization (IVF) market. Factors such as delayed parenthood, lifestyle disorders, stress, and rising incidences of conditions like polycystic ovary syndrome (PCOS) and endometriosis contribute to declining fertility rates worldwide. This trend is prompting more couples to seek assisted reproductive technologies like IVF. The market is further supported by growing societal acceptance and greater awareness regarding infertility treatments, encouraging early diagnosis and intervention, which is accelerating the demand for IVF procedures globally.
- For instance, the EMD Serono division of Merck KGaA supports over 1,400 fertility clinics across more than 50 countries with tailored IVF medications and protocols to manage complex infertility cases.
Technological Advancements in IVF Procedures
Ongoing advancements in IVF technologies are significantly boosting market growth. Innovations such as time-lapse imaging, preimplantation genetic testing (PGT), and improved cryopreservation techniques are enhancing embryo selection, increasing pregnancy success rates, and reducing multiple pregnancy risks. The introduction of sophisticated equipment, including automated sperm analyzers and micromanipulation systems, has improved the precision and reliability of IVF procedures. These technological improvements not only enhance clinical outcomes but also expand the accessibility and safety of IVF treatments, driving wider adoption among healthcare providers and patients.
- For instance, Thermo Fisher Scientific’s Ion ReproSeq PGT kit enables genetic screening for up to 24 chromosomes in a single-day workflow, significantly improving diagnostic speed and accuracy.
Government Support and Favorable Reimbursement Policies
Supportive government initiatives and expanding insurance coverage are positively influencing the IVF market. Many countries are providing financial subsidies, favorable reimbursement frameworks, and public awareness campaigns to address declining birth rates and demographic challenges. In regions such as Europe and parts of Asia-Pacific, government-backed programs significantly reduce the financial burden of IVF treatments, making them more accessible to a broader patient population. These supportive measures are driving the overall uptake of IVF services and contributing to sustained market expansion.
Key Trends & Opportunities
Growing Adoption of Fertility Preservation Techniques
The rising trend of fertility preservation, particularly through egg and embryo freezing, is creating new opportunities in the IVF market. Increasing awareness about elective fertility preservation among women delaying parenthood for personal or professional reasons is boosting demand. Advancements in cryopreservation technology now enable higher survival rates for frozen eggs and embryos, encouraging more individuals to opt for these services. This trend is also gaining momentum among cancer patients seeking to preserve fertility before undergoing treatments like chemotherapy, thereby expanding the potential user base for IVF services.
- For instance, Boston IVF has performed over 9,000 egg freezing cycles, offering fertility preservation to both elective and medical patients, including those undergoing cancer treatment.
Expansion of Medical Tourism for IVF Treatments
Medical tourism is emerging as a significant growth opportunity for the IVF market. Many patients from developed countries are traveling to regions such as Asia-Pacific and Eastern Europe to access high-quality IVF treatments at lower costs. Favorable regulatory environments, availability of skilled professionals, and competitive pricing in these destinations are driving cross-border fertility treatments. Additionally, clinics offering customized treatment packages and minimal waiting times are attracting international patients, thereby contributing to the globalization and expansion of the IVF industry.
- For instance, TFP Thames Valley Fertility in the UK has reported treating over 500 international IVF patients annually, with specialized travel support services to accommodate medical tourists efficiently.
Key Challenges
High Cost of IVF Procedures
The high cost associated with IVF treatments remains a significant barrier to market growth, particularly in developing countries. Expenses related to multiple treatment cycles, medications, advanced technologies, and laboratory charges make IVF unaffordable for a large section of the population. Limited reimbursement policies and out-of-pocket payment requirements further restrict access to these procedures. This financial challenge continues to limit market penetration, especially among middle and lower-income groups, despite rising demand and broader awareness of fertility treatment options.
Ethical and Legal Concerns
Ethical and legal challenges present notable obstacles in the IVF market. Issues surrounding embryo disposal, third-party reproduction, and surrogacy continue to generate ethical debates and regulatory scrutiny in various countries. Restrictions on donor anonymity, cross-border embryo transfers, and commercialization of gametes further complicate the legal landscape. Such ethical dilemmas and fragmented regulatory frameworks can hinder the growth of IVF services and delay technological adoption, particularly in regions with stringent cultural or religious beliefs regarding assisted reproduction.
Medical Complications and Procedure Risks
The potential health risks associated with IVF procedures pose a significant challenge to market growth. IVF increases the chances of multiple pregnancies, which can lead to complications such as preterm birth, low birth weight, and gestational diabetes. Patients may also face side effects from hormone treatments and the risk of ovarian hyperstimulation syndrome (OHSS). These medical concerns may deter some individuals from pursuing IVF and prompt stricter clinical regulations, which can slow down procedural advancements and limit patient acceptance.
Regional Analysis
North America
North America held a significant position in the In Vitro Fertilization (IVF) market, valued at USD 6,665.47 million in 2018, growing to USD 7,673.62 million in 2024, and projected to reach USD 12,764.91 million by 2032 at a CAGR of 6.6%. The region accounted for a substantial market share driven by advanced healthcare infrastructure, supportive reimbursement policies, and high awareness levels. The increasing prevalence of infertility and delayed parenthood significantly support market expansion. The growing demand for technologically advanced IVF solutions further strengthens North America’s leadership, with the United States contributing prominently to regional growth.
Europe
Europe commanded a leading share in the In Vitro Fertilization market with a valuation of USD 8,630.10 million in 2018, rising to USD 9,796.57 million in 2024, and expected to reach USD 15,508.17 million by 2032, growing at a CAGR of 5.9%. Europe holds the largest market share due to favorable government regulations, public funding, and broad acceptance of assisted reproductive technologies. Countries like the UK, France, and Germany contribute heavily to the regional dominance. Increased medical tourism and the availability of advanced IVF centers further support Europe's sustained market leadership.
Asia Pacific
Asia Pacific is the fastest-growing region in the In Vitro Fertilization market, with a market size of USD 5,240.50 million in 2018, projected to reach USD 6,392.30 million in 2024 and USD 11,576.94 million by 2032, registering a CAGR of 7.7%. The region's market share is rapidly expanding, driven by rising infertility rates, increasing medical tourism, and growing acceptance of IVF treatments. China, Japan, and India are key contributors to growth due to improving healthcare infrastructure and affordability. Advancements in fertility technology and growing awareness continue to attract significant patient volumes to the region.
Latin America
Latin America’s In Vitro Fertilization market reached USD 1,090.47 million in 2018, is estimated at USD 1,255.60 million in 2024, and is projected to grow to USD 1,902.99 million by 2032 at a CAGR of 5.4%. The region holds a moderate market share, supported by increasing demand for IVF procedures and improving healthcare accessibility in countries like Brazil and Mexico. The market benefits from rising awareness of fertility treatments and affordable IVF services compared to developed regions. Continued efforts to enhance clinical standards and investments in fertility centers are expected to sustain regional market growth.
Middle East
The Middle East In Vitro Fertilization market was valued at USD 472.76 million in 2018, estimated to reach USD 488.65 million in 2024, and projected to grow to USD 678.90 million by 2032 at a CAGR of 4.3%. Although the region holds a smaller market share, increasing infertility rates and gradual social acceptance of IVF treatments are driving growth. Countries like the UAE and Saudi Arabia are investing in advanced reproductive technologies, boosting regional capabilities. Expanding medical tourism and growing government initiatives to support fertility care contribute to the steady development of the IVF market in the Middle East.
Africa
Africa’s In Vitro Fertilization market was valued at USD 200.70 million in 2018, estimated at USD 394.52 million in 2024, and is anticipated to reach USD 554.09 million by 2032, growing at a CAGR of 4.5%. Africa holds the smallest market share but shows promising growth potential with increasing awareness of infertility treatments and improving access to healthcare facilities. The growing middle-class population and efforts to establish fertility clinics in key countries like South Africa and Nigeria are driving demand. However, high treatment costs and limited availability of advanced IVF centers continue to challenge broader market penetration.
Market Segmentations:
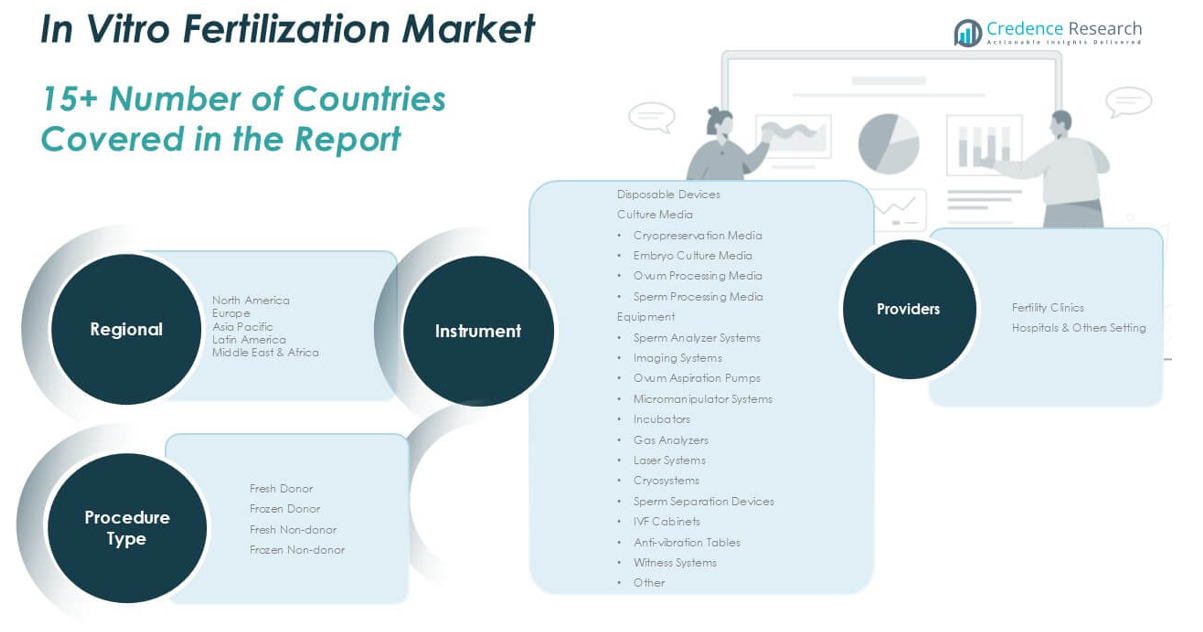
By Instrument
- Disposable Devices
- Culture Media
- Cryopreservation Media
- Embryo Culture Media
- Ovum Processing Media
- Sperm Processing Media
- Equipment
- Sperm Analyzer Systems
- Imaging Systems
- Ovum Aspiration Pumps
- Micromanipulator Systems
- Incubators
- Gas Analyzers
- Laser Systems
- Cryosystems
- Sperm Separation Devices
- IVF Cabinets
- Anti-vibration Tables
- Witness Systems
- Other
By Procedure Type
- Fresh Donor
- Frozen Donor
- Fresh Non-Donor
- Frozen Non-Donor
By Providers
- Fertility Clinics
- Hospitals & Other Settings
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the In Vitro Fertilization (IVF) market is characterized by the presence of several established players focusing on product innovation, strategic collaborations, and global expansion to strengthen their market position. Companies such as Bayer AG, Merck KGaA, Thermo Fisher Scientific, and FUJIFILM Irvine Scientific dominate the market with comprehensive product portfolios and strong distribution networks. Key players are actively investing in advanced IVF technologies, including time-lapse imaging and genetic screening, to improve success rates and patient outcomes. Partnerships between fertility clinics and technology providers are becoming increasingly common to enhance service offerings and procedural efficiency. Emerging players and specialized IVF clinics are contributing to regional growth by offering cost-effective and personalized treatment options. The market is witnessing consolidation through mergers and acquisitions, which enables companies to broaden their geographic reach and technological capabilities. Continuous advancements in equipment and culture media remain central to maintaining competitive differentiation in this rapidly evolving industry.
Key Player Analysis
- Bayer AG
- Cook Medical LLC
- EMD Serono, Inc.
- Ferring B.V.
- FUJIFILM Irvine Scientific (FUJIFILM Holdings Corporation)
- Genea Biomedx
- EMD Serono, Inc. (Merck KGaA)
- Merck KGaA (Germany)
- The Cooper Companies, Inc.
- Thermo Fisher Scientific, Inc.
- Vitrolife
- Boston IVF
- Nova IVF
- RMA Network (Reproductive Medicine Associates)
- TFP Thames Valley Fertility
- Fortis Healthcare
- S. Fertility
Recent Developments
- In June 2023, FUJIFILM Irvine Scientific, Inc. expanded its Presagen’s Life Whisperer platform capabilities to help with clinical decision-making in IVF.
- In May 2023, Merck KGaA introduced Fertility Counts to address societal, economic, and social challenges associated with low birth rates in the Asia Pacific (APAC) region.
- In May 2023, Ovation Fertility combined with US Fertility to created fertility platform offering advanced fertility care and IVF services in the U.S.
- In April 2023, Boston IVF signed 3 years supply chain solutions agreement with Cryoport, Inc. to support the reproductive material shipment across the U.S.
- In 2023, Hamilton Thorne Nederland BV completed the acquisition of Gynetics MP NV and Gynetics S, BV, expanding its operations into more profitable dealings within the mature European ART market.
- In 2023, Esco acquired CMT Materials, LLC and its affiliate Engineered Syntactic Systems, LLC, thereby including the critical equipment for the development and production of materials in order to further enhance the basket of products offered by Esco.
Market Concentration & Characteristics
The In Vitro Fertilization Market shows a moderate to high level of concentration, with a few dominant players holding significant market shares. It is characterized by strong competition driven by technological advancements, product diversification, and strategic collaborations. Leading companies continuously invest in research to improve success rates and procedural efficiency. The market exhibits high entry barriers due to strict regulatory requirements, high initial investment costs, and the need for specialized expertise. It reflects a combination of innovation-driven growth and steady demand from an expanding patient base. It benefits from growing acceptance of assisted reproductive technologies and the rising number of specialized fertility clinics worldwide.
Report Coverage
The research report offers an in-depth analysis based on Instrument, Procedure Type, Providers and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The In Vitro Fertilization market is expected to grow steadily, driven by increasing infertility rates worldwide.
- Advancements in IVF technologies will continue to improve success rates and patient outcomes.
- Demand for fertility preservation, including egg and embryo freezing, is likely to rise significantly.
- Medical tourism for affordable and quality IVF treatments is expected to expand across emerging regions.
- The use of genetic screening and time-lapse imaging in IVF procedures will become more widespread.
- Fertility clinics will continue to dominate the provider segment due to their specialized services and advanced infrastructure.
- Growing awareness and social acceptance of assisted reproductive technologies will support market growth.
- Government support and favorable reimbursement policies in several countries are likely to increase access to IVF treatments.
- The market will face challenges from high treatment costs and limited availability in low-income regions.
- Ethical and regulatory considerations will continue to shape market dynamics and influence treatment accessibility.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Infertility Rates Globally
Increasing prevalence of infertility due to lifestyle changes, delayed parenthood, and medical conditions such as PCOS and endometriosis is driving more couples to seek IVF treatments, expanding the market.
Technological Advancements in IVF Procedures
Innovations like time-lapse imaging, preimplantation genetic testing, and improved cryopreservation techniques are enhancing success rates and safety, making IVF more attractive and accessible.
Government Support and Favorable Reimbursement Policies
Financial subsidies, public funding, and insurance coverage in regions like Europe and parts of Asia-Pacific are reducing the financial burden of IVF, increasing patient access and market growth.
Growing Adoption of Fertility Preservation Techniques
Rising awareness and advancements in egg and embryo freezing are enabling more individuals, including cancer patients and those delaying parenthood, to preserve fertility, boosting demand for IVF services.
Expansion of Medical Tourism for IVF Treatments
Patients from developed countries are increasingly traveling to regions with high-quality, lower-cost IVF services, such as Asia-Pacific and Eastern Europe, driving global market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the In Vitro Fertilization Market?
What are the key segments within the In Vitro Fertilization Market?
What are some challenges faced by the In Vitro Fertilization Market?
Who are the major players in the In Vitro Fertilization Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Providers
- 1.2.1 Fertility Clinics
- 1.2.2 Hospitals & Other Settings
- 1.3 By Instrument
- 1.3.1 Disposable Devices
- 1.3.2 Culture Media
- 1.3.3 Equipment
- 1.4 By Procedure Type
- 1.4.1 Fresh Donor
- 1.4.2 Frozen Donor
- 1.4.3 Fresh Non-Donor
- 1.4.4 Frozen Non-Donor
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 26,001.26 million → 2032: USD 42,986.00 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global In-Vitro Fertilization Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global In-Vitro Fertilization Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global In-Vitro Fertilization Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global In-Vitro Fertilization Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global In-Vitro Fertilization Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global In-Vitro Fertilization Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global In-Vitro Fertilization Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global In-Vitro Fertilization Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 26,001.26 million → 2032: USD 42,986.00 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global In-Vitro Fertilization Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Providers - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fertility Clinics
- 12.3.7.2 Hospitals & Other Settings
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Instrument - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Disposable Devices
- 12.4.7.2 Culture Media
- 12.4.7.3 Equipment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Procedure Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fresh Donor
- 12.5.7.2 Frozen Donor
- 12.5.7.3 Fresh Non-Donor
- 12.5.7.4 Frozen Non-Donor
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global In-Vitro Fertilization Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global In-Vitro Fertilization Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global In-Vitro Fertilization Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Bayer AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Merck KGaA
- 17.4 Thermo Fisher Scientific, Inc.
- 17.5 Vitrolife
- 17.6 FUJIFILM Irvine Scientific
- 17.7 The Cooper Companies, Inc.
- 17.8 Cook Medical LLC
- 17.9 Ferring B.V.
- 17.10 Genea Biomedx
- 17.11 Boston IVF
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

