
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
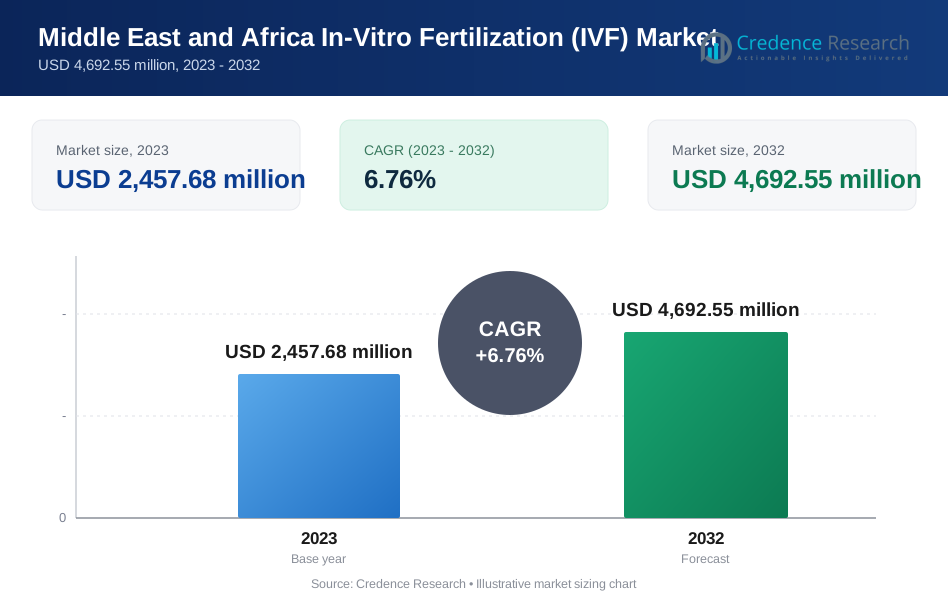
| Middle East and Africa In-Vitro Fertilization (IVF) Market 2023 | USD 2,457.68 million |
| Middle East and Africa In-Vitro Fertilization (IVF) Market, CAGR | 6.76% |
| Middle East and Africa In-Vitro Fertilization (IVF) Market Size 2032 | USD 4,692.55 million |
Market Overview:
The In-Vitro Fertilization (IVF) market in the Middle East and Africa (MEA) region is poised for significant growth, with projections indicating a rise from USD 2,457.68 million in 2023 to an estimated USD 4,692.55 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 6.76%. This growth is primarily driven by several key factors, including the escalating rates of infertility in the region due to various social, economic, and lifestyle factors. Moreover, increased investments in healthcare infrastructure, coupled with heightened awareness about infertility treatments, are propelling the adoption of IVF procedures, contributing to market expansion.
Rising disposable incomes, particularly in countries within the Gulf Cooperation Council (GCC), play a pivotal role in driving the growth of the IVF market in the MEA region. As more couples gain financial stability, they are increasingly able to pursue advanced fertility treatments like IVF. Additionally, the relaxation of regulations surrounding IVF procedures in certain countries, alongside growing government support for infertility treatments, creates a conducive environment for market expansion. Technological advancements in IVF, such as improved embryo selection techniques and preimplantation genetic diagnosis (PGD), further contribute to higher success rates, instilling greater confidence in IVF as a viable treatment option.
Emerging trends in the IVF market within the MEA region include the growth of fertility tourism, with patients from neighboring countries seeking treatment in more advanced facilities, and the integration of telemedicine into IVF services, enhancing patient accessibility and convenience. Moreover, there is a growing focus on personalized medicine in IVF, aiming to tailor treatment plans based on individual patient factors and genetic information. As the market continues to evolve, opportunities lie in expanding clinic networks to underserved regions, investing in advanced IVF technologies to improve success rates, and developing cost-effective treatment packages to broaden patient access. Strategic partnerships between fertility clinics, healthcare providers, and insurance companies can further enhance patient access to financing and comprehensive care, driving continued growth in the IVF market within the MEA region.
Market Drivers:
Increasing Incidence of Infertility:
A significant driver of the IVF market in the Middle East and Africa (MEA) region is the escalating incidence of infertility. For instance, factors such as delayed childbearing, environmental pollution, and shifting lifestyle patterns contribute to this trend. Over time, the prevalence of primary infertility in men and women in the MEA region has seen an increase, with rates of change of 40.9 and 19.0, respectively. As infertility rates rise, more couples are turning to assisted reproductive technologies like IVF as a solution to overcome fertility challenges and fulfill their desire for parenthood.
Growing Awareness and Acceptance of IVF Treatments: Traditionally, cultural stigmas and societal taboos surrounding infertility treatments may have hindered couples in the MEA region from considering IVF. However, there is a noticeable shift towards greater awareness and acceptance of IVF as a viable option for achieving pregnancy. For instance, educational initiatives, coupled with increased media coverage, are fostering a more open and informed discourse regarding fertility treatments, leading to higher acceptance rates.
Rising Disposable Income and Government Support:
The increasing disposable income levels across the MEA region empower couples to pursue IVF treatment. Moreover, supportive government policies and financial assistance programs, including insurance coverage for fertility treatments, are expanding access to IVF services for a broader population. These factors contribute to the growing affordability and accessibility of IVF treatments in the region.
Advancements in IVF Technology:
Continuous advancements in IVF technology play a pivotal role in driving market growth. Innovations such as improved embryo selection techniques, preimplantation genetic screening (PGS), and advanced vitrification methods enhance the efficacy and success rates of IVF procedures. These technological advancements offer couples undergoing IVF a higher probability of successful conception and healthier pregnancy outcomes.
Development of Fertility Clinics and Infrastructure:
The MEA region is witnessing a proliferation of fertility clinics and specialized healthcare facilities offering IVF services. This expansion in infrastructure enhances access to qualified medical professionals and state-of-the-art equipment, thereby bolstering the IVF market. Furthermore, investments in healthcare infrastructure by governments and private entities contribute to creating a supportive environment for fertility treatments, driving market growth in the region.
Market Trends:
- Rising Demand for Fertility Treatments: Social factors like later childbearing, increasing awareness of infertility solutions, and decreasing societal stigma surrounding fertility treatments are contributing to a surge in demand for IVF procedures across the MEA region. For instance, the infertility rate in the MENA region is around 15%, significantly higher than the 10% global average. This high infertility rate, coupled with social factors like later childbearing and increasing awareness of infertility solutions, is driving the demand for IVF treatments. The number of IVF cycles in Egypt alone is expected to rise almost 30% this decade, hitting almost 206k by 2030.
- Growing Number of Fertility Clinics and Specialists: To cater to the rising demand, there is a notable increase in the number of fertility clinics and qualified specialists in the MEA region. This improved access to specialists and facilities is making IVF procedures more readily available to couples struggling with infertility. For instance, there is no definitive data available for the exact number of fertility clinics and specialists in the MEA region. This indicates a notable increase in the number of fertility clinics and qualified specialists in the region.
- Government Initiatives and Favorable Regulations: Supportive government policies and regulations in some MEA countries are fostering a more favorable environment for IVF treatments. This includes initiatives to raise awareness, improve access to fertility services, and potentially even offer financial support for these procedures. For instance, the new changes in IVF laws are expected to further boost the IVF market. One of the most fundamental changes introduced by the new IVF law for fertility patients relates to the freezing of human embryos as well as unfertilised eggs and sperm. This, along with other supportive government policies and regulations, is fostering a more favorable environment for IVF treatments in the MEA region.
- Technological Advancements and Improved Success Rates: Advancements in medical technology, such as improved embryo selection techniques and preimplantation genetic diagnosis (PGD), are leading to higher success rates for IVF procedures. This is making IVF a more attractive option for couples seeking fertility solutions.
- Fertility Tourism: The MEA region is increasingly becoming a destination for fertility tourism, attracting patients from other countries seeking affordable and high-quality IVF treatments. This trend is driven by factors such as lower costs compared to developed nations and the availability of advanced medical expertise.
Market Restraints and Challenges:
- High Cost of IVF Treatment: IVF treatment remains a costly endeavor in many MEA countries. Factors like medication expenses, laboratory fees, and doctor consultations contribute to the overall cost. This can be a significant barrier for a large portion of the population, particularly those with limited financial resources. Limited insurance coverage for IVF procedures further exacerbates the issue.
- Ethical and Religious Concerns: Certain religious and cultural beliefs in some parts of the MEA region can create ethical and religious concerns surrounding IVF. These concerns might involve the use of donor eggs or sperm, the issue of preimplantation genetic diagnosis (PGD), and the status of frozen embryos. Addressing these concerns through open communication, educational initiatives, and fostering dialogue with religious leaders can be crucial.
- Lack of Awareness and Stigma: Limited awareness about infertility and IVF treatment options remains a challenge in some regions of the MEA. Social stigma associated with infertility can further discourage individuals from seeking help. Educational campaigns and raising awareness through various channels can play a significant role in normalizing infertility and promoting IVF as a viable treatment option.
- Limited Access to Qualified Professionals and Advanced Facilities: The availability of qualified medical professionals with expertise in IVF procedures can be limited in certain areas within the MEA region. Additionally, the accessibility of advanced IVF facilities with the latest technology might be restricted, particularly in remote areas. Investments in healthcare infrastructure, training programs for specialists, and ensuring wider geographical distribution of qualified professionals and advanced facilities are crucial for market growth.
- Stringent Regulations and Legal Frameworks: Strict regulations and legal frameworks governing IVF practices can pose challenges for some countries in the MEA region. These regulations might encompass limitations on embryo selection, gestational surrogacy, or the use of donor gametes. Streamlining regulations while ensuring ethical practices and patient safety can promote responsible growth in the IVF market.
Recent Developments:
- May 2023: AIVF, the developer of AI-based solutions for IVF clinics, and Genea Biomedx launched an integrated system. The new integrated solution provides widespread access to individualized, improved IVF care by connecting Genea Biomedx's Geri time-lapse incubator with AIVF's innovative EMA AI platform.
- June 2022: Oma Fertility emerged from stealth and introduced a first-of-its-kind network of fertility clinics, offering families science-forward, AI-informed fertility treatments, paving the way for a new standard in IVF success rates.
Segmentation Analysis:
By Cycle Type:
- Fresh IVF Cycles: This segment currently holds the largest market share and is expected to maintain its lead throughout the forecast period. Fresh IVF cycles involve using eggs retrieved during the current menstrual cycle and fertilizing them with sperm for implantation.
- Thawed IVF Cycles: This segment is expected to show significant growth due to advancements in cryopreservation techniques that allow for successful freezing and thawing of eggs and embryos. Thawed cycles offer convenience and flexibility for patients who have undergone egg or embryo banking.
- Donor Egg IVF Cycles: The rising incidence of infertility due to factors like age and medical conditions is driving the demand for donor egg IVF cycles. This segment is expected to grow steadily as more couples seek alternative solutions for achieving pregnancy.
Segments:
By Product:
- Equipment
- Reagents and Media
- Accessories
By Cycle:
- Fresh non-donor cycle
- Frozen non-donor IVF cycle
- Frozen donor IVF cycle
- Fresh donor IVF cycle
By End User:
- Fertility Clinics
- Hospitals & Surgical Centers
- Cryobank and Research Institutes
By Type:
- Conventional IVF
- IVF with ICSI
- IVF with Donor Eggs
Key player:
- Coopersurgical Inc.
- Vitrolife AB
- Cook Medical Inc.
- Thermo Fisher Scientific Inc.
- Irvine Scientific
- Rocket Medical PLC.
- Merck KGaA
- Genea Limited
- IVFtech APS
- The Baker Company, Inc.
Regional Analysis:
Rising disposable incomes and increasing awareness are significant drivers behind the growing demand for in vitro fertilization (IVF) procedures in the Middle East and Africa (MEA) region. With growing prosperity, particularly in Gulf countries, more couples are financially able to pursue IVF treatment. Furthermore, heightened awareness about infertility issues and advancements in IVF technology are contributing to the increasing acceptance and demand for these procedures among couples facing fertility challenges.
Future Outlook:
- Rising Demand for Fertility Treatments: An expected rise in age at childbearing and growing awareness of IVF procedures will likely lead to an increased demand for fertility treatments across the region.
- Government Initiatives and Improved Healthcare Infrastructure: Supportive government policies and investments in improving healthcare infrastructure are expected to make IVF more accessible to a wider population in the Middle East and Africa.
- Increasing Disposable Income and Insurance Coverage: Rising disposable incomes and a growing trend of insurance coverage for fertility treatments are likely to contribute to a higher patient pool seeking IVF services.
- Technological Advancements in IVF Procedures: Continuous advancements in IVF technology, such as preimplantation genetic testing (PGT) and improved cryopreservation techniques, are expected to enhance success rates and attract more patients.
- Growing Popularity of Egg and Sperm Donation: The increasing acceptance of egg and sperm donation will expand treatment options for couples facing infertility challenges.
- Rise of Fertility Tourism: The Middle East and Africa may witness an increase in fertility tourism, as some countries offer competitive costs and advanced IVF procedures compared to other regions.
- Focus on Personalized Medicine and Tailored IVF Protocols: A growing emphasis on personalized medicine will lead to the development of customized IVF protocols for improved treatment effectiveness.
- Increasing Emphasis on Ethical Considerations and Regulations: Stricter regulations and a growing focus on ethical considerations surrounding IVF practices are expected to ensure patient safety and well-being.
- Potential Impact of Economic Fluctuations and Political Instability: Economic fluctuations and political instability in certain regions may pose challenges to market growth.
- Growing Competition Among IVF Service Providers: An increase in competition among IVF service providers is likely to lead to price pressures and a wider range of service options for patients.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What factors are driving the growth of the IVF market in the Middle East and Africa (MEA) region?
How significant is the projected market growth for the MEA IVF market?
What role do government initiatives and regulations play in shaping the MEA IVF market?
How are technological advancements impacting the MEA IVF market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East and Africa In-Vitro Fertilization (IVF) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East and Africa In-Vitro Fertilization (IVF) Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,457.68 million → 2032: USD 4,692.55 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East and Africa In-Vitro Fertilization (IVF) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East and Africa In-Vitro Fertilization (IVF) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East and Africa In-Vitro Fertilization (IVF) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East and Africa In-Vitro Fertilization (IVF) Market Drivers
- 3.3 Middle East and Africa In-Vitro Fertilization (IVF) Market Restraints & Challenges
- 3.4 Middle East and Africa In-Vitro Fertilization (IVF) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East and Africa In-Vitro Fertilization (IVF) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East and Africa In-Vitro Fertilization (IVF) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East and Africa In-Vitro Fertilization (IVF) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East and Africa In-Vitro Fertilization (IVF) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East and Africa In-Vitro Fertilization (IVF) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East and Africa In-Vitro Fertilization (IVF) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East and Africa In-Vitro Fertilization (IVF) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East and Africa In-Vitro Fertilization (IVF) Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East and Africa In-Vitro Fertilization (IVF) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East and Africa In-Vitro Fertilization (IVF) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East and Africa In-Vitro Fertilization (IVF) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East and Africa In-Vitro Fertilization (IVF) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East and Africa In-Vitro Fertilization (IVF) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East and Africa In-Vitro Fertilization (IVF) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East and Africa In-Vitro Fertilization (IVF) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East and Africa In-Vitro Fertilization (IVF) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East and Africa In-Vitro Fertilization (IVF) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East and Africa In-Vitro Fertilization (IVF) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East and Africa In-Vitro Fertilization (IVF) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
