
Indoor Humidifier Market Overview:
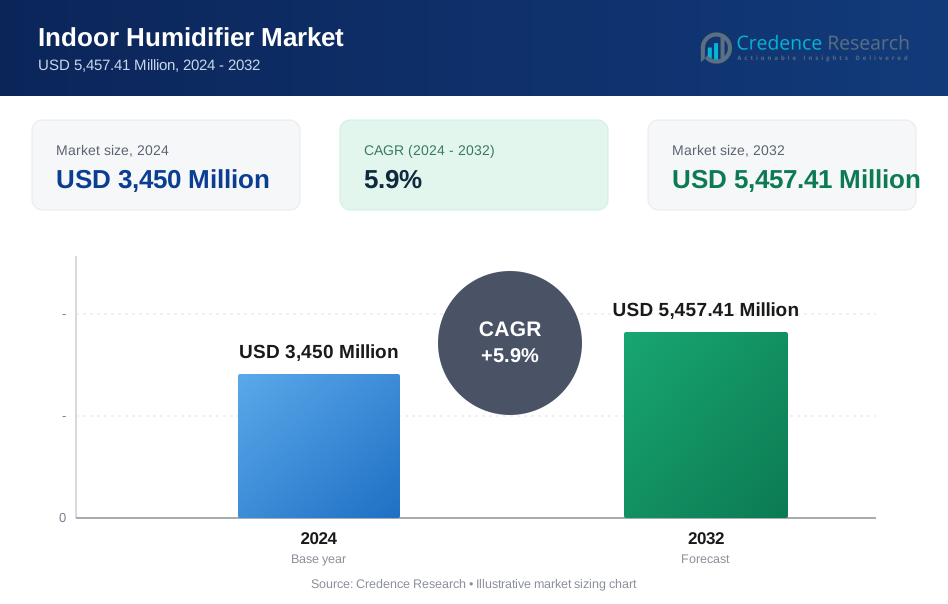
Indoor Humidifier market size was valued USD 3,450 Million in 2024 and is anticipated to reach USD 5,457.41 Million by 2032, at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Indoor Humidifier Market Size 2024 | USD 3,450 million |
| Indoor Humidifier Market, CAGR | 5.9% |
| Indoor Humidifier Market Size 2032 | USD 5,457.41 million |
Indoor Humidifier Market Insights
- Market overview highlights increasing demand from residential and commercial users as consumers prioritize indoor comfort, respiratory wellness, and energy-efficient air-quality devices, with evaporative humidifiers holding 36.8% share as the dominant product segment.
- Market drivers include rising awareness of indoor air quality, growth in healthcare and data-center infrastructure, and wider adoption of smart, ultrasonic, and IoT-enabled humidifier systems that enhance convenience, automation, and performance.
- Competitive analysis shows strong participation from global players focusing on product innovation, durability, filtration safety, and connectivity features, while regional manufacturers compete through affordable models and localized distribution networks.
- Regional analysis indicates North America leads with 34.6% share, followed by Europe at 27.8% and Asia Pacific at 24.3%, while Latin America and Middle East & Africa collectively contribute niche but expanding demand supported by commercial and healthcare investments.

Indoor Humidifier Market Segmentation Analysis:
By Product Type
The Indoor Humidifier market by product type is led by evaporative humidifiers, which accounted for 36.8% market share in 2024 due to their energy efficiency, low maintenance requirements, and suitability for continuous residential and commercial use. Ultrasonic systems also experience strong adoption driven by their quiet operation and compact design, particularly in premium home and healthcare environments. Warm mist humidifiers and vaporizers remain relevant in cold-climate and wellness-focused households, while steam-to-steam humidifiers show growing traction in industrial and institutional settings where precise humidity regulation and hygiene standards are critical drivers of adoption.
- For instance, AIRx and other filter suppliers publicly specify that evaporative humidifier filters can last for an entire heating season with routine cleaning and proper water quality.
By Industry Vertical
The healthcare segment dominated the Indoor Humidifier market by industry vertical with 29.4% market share in 2024, supported by stringent air-quality control needs across hospitals, laboratories, and pharmaceutical facilities to maintain patient safety and equipment stability. The food & beverages segment follows closely, driven by preservation, packaging, and production-environment humidity requirements. IT and data centers adopt humidifiers to prevent electrostatic discharge and equipment failure, while textiles, automotive, and paper & pulps industries deploy humidity control to improve material stability, manufacturing efficiency, and product quality across temperature-sensitive production processes.
- For instance, Condair and similar suppliers provide steam and hygienic humidification systems that are installed in operating rooms and isolation wards to maintain controlled humidity and reduce airborne contaminants.
By Application
The residential segment held the dominant position in the Indoor Humidifier market by application with 42.7% market share in 2024, fueled by rising consumer awareness of indoor air quality, respiratory wellness, and comfort enhancement in urban households. Commercial applications, including offices, retail spaces, hospitality, and institutions, continue to expand as businesses prioritize employee health and environmental control. The industrial segment demonstrates steady growth driven by process-critical humidity management across manufacturing, warehousing, and controlled-environment operations, where humidity stabilization directly supports productivity, material integrity, and equipment reliability.
Key Growth Drivers
Rising Focus on Indoor Air Quality and Health Wellness
Growing consumer awareness regarding respiratory health, allergy prevention, and overall indoor environmental comfort is a major driver for the Indoor Humidifier market. Increasing urbanization and prolonged indoor living have amplified concerns related to dry air, sinus irritation, skin dehydration, and sleep discomfort, prompting households to adopt humidifiers as essential home wellness appliances. Healthcare professionals increasingly recommend controlled humidity environments for asthma and chronic respiratory patients, further strengthening adoption. In addition, the expanding elderly population and rising pediatric care concerns are boosting demand for safe, energy-efficient humidification solutions in homes, clinics, and elderly care facilities. Marketing campaigns emphasizing wellness, comfort, and lifestyle enhancement have also shifted humidifiers from seasonal devices to year-round utility products, thereby supporting sustained market growth.
- For instance, manufacturers such as Dyson and Levoit market humidifiers with integrated air-quality sensors and app-based controls, highlighting benefits like easier breathing, improved sleep, and reduced dryness in bedrooms and nurseries
Expansion of Commercial and Industrial Applications
The market experiences strong growth from commercial and industrial sectors where humidity control plays a critical role in process efficiency, equipment reliability, and environmental stability. Offices, hospitality facilities, retail spaces, and data centers increasingly deploy centralized humidification systems to support employee comfort, productivity, and equipment protection. In industrial environments such as pharmaceuticals, food processing, textiles, and electronics manufacturing, humidifiers help reduce electrostatic discharge, material shrinkage, and quality degradation, resulting in operational consistency and product integrity. The growing trend of smart infrastructure, along with modernization of manufacturing plants and logistics hubs, further accelerates installations of automated humidity-management systems. Additionally, regulatory emphasis on workplace environmental standards and controlled-atmosphere facilities continues to drive investment in advanced humidification technologies across multiple industrial segments.
- For instance, large office and hospitality facilities increasingly deploy building management systems (BMS) that control both temperature and humidity to support occupant comfort and productivity.
Technological Advancements and Product Innovation
Continuous innovation in design, automation, and energy efficiency significantly contributes to the growth of the Indoor Humidifier market. Manufacturers are increasingly introducing ultrasonic, evaporative, and hybrid models with advanced features such as automatic humidity sensing, IoT connectivity, noise-reduction technology, and antimicrobial filtration components. Smart home integration through mobile apps and voice-assistant platforms enhances user convenience and encourages adoption among tech-savvy consumers. Innovations in water purification and leak-prevention systems improve operational safety and durability, making humidifiers more suitable for long-term residential and commercial use. Additionally, compact modular designs and refill-friendly tank structures support ease of maintenance. These advancements not only enhance performance but also differentiate premium offerings, enabling manufacturers to target higher-value consumer segments and strengthen product penetration across global markets.
Key Trends & Opportunities
Growing Adoption of Smart and Connected Humidifier Systems
A key trend in the Indoor Humidifier market is the increasing adoption of smart and connected devices that offer automated humidity control and enhanced user experience. Integration with home automation ecosystems, mobile app monitoring, and AI-based environment optimization enables users to maintain ideal comfort conditions with minimal manual intervention. Connected humidifiers also provide maintenance alerts, filter-replacement notifications, and energy-usage insights, appealing to urban consumers and premium lifestyle households. In commercial facilities and healthcare institutions, cloud-enabled humidity management supports centralized monitoring, operational efficiency, and preventive maintenance scheduling. This trend creates strong opportunities for manufacturers to introduce subscription-based filter services, remote diagnostics, and data-driven performance optimization platforms, thereby expanding revenue potential beyond hardware sales.
- For instance, Dyson’s Purifier Humidify+Cool series uses onboard sensors and an app (MyDyson) to automatically adjust humidity and provide filter-life and usage insights.
Sustainability-Focused Product Development and Energy Efficiency Demand
Increasing emphasis on sustainability presents significant opportunities in the Indoor Humidifier market, as consumers and enterprises prioritize energy-efficient and environmentally responsible solutions. Manufacturers are investing in eco-friendly materials, low-power consumption technologies, and water-saving mechanisms to align with global sustainability goals. Demand is rising for filter-free humidifiers, recyclable components, and long-life product designs that minimize waste and maintenance costs. In industrial and commercial environments, energy-optimized systems support operational cost reduction and carbon-reduction initiatives, encouraging replacements of older, high-consumption humidification units. Government incentives for energy-efficient infrastructure and green building certifications further strengthen market opportunities for sustainable humidifier technologies across residential, institutional, and industrial applications.
- For instance, Rumidifier Home Comforts Inc. offers patented room humidifiers that use no electricity, instead leveraging existing HVAC airflow through floor or wall vents to add moisture, positioning them as eco-friendly, zero‑energy products.
Key Challenges
Maintenance Complexity and Operational Hygiene Concerns
One of the major challenges in the Indoor Humidifier market relates to maintenance requirements and hygiene management. Improper cleaning or delayed filter replacement can result in bacterial buildup, mold formation, and mineral residue discharge, leading to potential health risks and performance degradation. Users often perceive maintenance processes as time-consuming or complicated, which affects long-term product usage and repeat purchases. In commercial and healthcare environments, regulatory hygiene standards require frequent servicing and monitoring, increasing operational burden and maintenance costs. Manufacturers face the challenge of designing systems that balance convenience, sanitation, and durability while maintaining affordability. Addressing user education, maintenance automation, and self-cleaning technology remains critical to improving customer confidence and sustaining product adoption.
High Initial Costs and Energy Consumption in Large-Scale Installations
Despite growing demand, high upfront costs and energy consumption remain significant challenges, particularly for industrial and commercial humidification systems. Centralized or process-grade humidifiers require capital investment in equipment, installation, plumbing, and control systems, which can limit adoption among small and medium enterprises. Rising electricity costs and operational expenses further influence purchasing decisions, prompting buyers to delay upgrades or rely on conventional alternatives. Additionally, budget-constrained residential consumers may prefer low-cost seasonal devices instead of advanced premium models. Manufacturers must balance cost optimization with performance innovation while demonstrating clear return-on-investment benefits to end users. Competitive pricing strategies, financing models, and efficiency-driven product engineering will be essential to overcoming these economic adoption barriers.
Regional Analysis
North America
North America held a market share of 34.6% in the Indoor Humidifier market in 2024, driven by high residential adoption, strong consumer awareness of indoor air quality, and widespread use of HVAC-integrated humidity control systems. The United States leads demand due to cold climatic conditions in northern states, increasing prevalence of respiratory ailments, and strong penetration of smart home appliances. Healthcare, commercial offices, and data centers further contribute to uptake as humidity stabilization supports equipment protection and occupant comfort. Growing preference for energy-efficient ultrasonic and evaporative models, along with premium wellness-oriented humidifiers, continues to strengthen regional market growth.
Europe
Europe accounted for 27.8% market share in the Indoor Humidifier market in 2024, supported by cold climatic conditions, advanced building infrastructure, and strong regulatory emphasis on healthy indoor environments. Demand remains high across residential apartments, hospitals, pharmaceuticals, and industrial processing facilities, particularly in Germany, the United Kingdom, France, and the Nordic countries. The region also benefits from rising investments in HVAC modernization and humidity-controlled manufacturing environments. Consumer focus on wellness, comfort living, and energy-efficient appliances fuels adoption of ultrasonic and evaporative systems, while commercial facilities increasingly deploy centralized humidification solutions to enhance occupant comfort and operational reliability.
Asia Pacific
Asia Pacific emerged as the fastest-growing region with a 24.3% market share in 2024, driven by rapid urbanization, expanding residential construction, and increasing consumer awareness of indoor comfort and respiratory health. China, Japan, South Korea, and India represent major demand centers, supported by rising disposable incomes and growing adoption of smart and compact home appliances. Industrial sectors such as electronics, textiles, pharmaceuticals, and food processing significantly contribute to regional growth due to humidity-sensitive production processes. The expanding healthcare infrastructure, coupled with the rising penetration of energy-efficient ultrasonic and evaporative humidifiers, continues to create strong market opportunities across the region.
Latin America
Latin America captured 7.6% market share in the Indoor Humidifier market in 2024, with growth primarily concentrated in Brazil, Mexico, Chile, and Argentina. Rising awareness of indoor comfort, increasing adoption of air-quality enhancing devices, and gradual expansion of urban residential developments support market demand. Commercial offices, healthcare facilities, and hospitality environments are progressively integrating humidity control systems to improve comfort and protect sensitive equipment. Although price sensitivity remains a key restraint, improving availability of mid-range and compact humidifier models, along with growing retail and e-commerce penetration, is expected to strengthen market adoption across both residential and light-commercial applications.
Middle East & Africa
The Middle East & Africa region accounted for 5.7% market share in the Indoor Humidifier market in 2024, driven by growing demand from commercial buildings, healthcare facilities, and industrial environments requiring controlled humidity conditions. The UAE, Saudi Arabia, and South Africa lead adoption, supported by expanding infrastructure projects and modernization of hospitality, retail, and institutional spaces. While residential usage remains comparatively limited, increasing indoor comfort awareness and premium lifestyle adoption trends are gradually supporting household demand. Industrial sectors such as pharmaceuticals, packaging, and data centers further contribute to installations as humidity stabilization enhances product quality, operational efficiency, and equipment reliability.
Indoor Humidifier Market Segmentations:
By Product Type
- Vaporizers
- Ultrasonic Systems
- Warm Mist Humidifiers
- Evaporative Humidifiers
- Steam-to-Steam Humidifiers
By Industry Vertical
- Healthcare
- Retail
- Food & Beverages
- Paper & Pulps
- IT
- Automotive
- Textiles
By Application
- Residential
- Commercial
- Industrial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Indoor Humidifier market is characterized by the strong presence of global appliance manufacturers, HVAC solution providers, and specialty air-quality technology companies focusing on product differentiation, energy efficiency, and smart-connected features. Key players include Honeywell International Inc., Koninklijke Philips N.V., Mitsubishi Heavy Industries Ltd., Armstrong International Inc., Carel Industries S.p.A., Munters Ltd., Boneco AG, Vornado Air LLC, United Technologies Corp., and Procter & Gamble Company. These companies compete through innovations such as ultrasonic and evaporative technologies, low-noise operation, antimicrobial filtration, and IoT-enabled humidity control systems. Strategic initiatives including product launches, partnerships with HVAC integrators, and expansion into healthcare and commercial segments strengthen their market footprint. Many players emphasize sustainability, compact design, and user-friendly maintenance to enhance customer adoption. In addition, manufacturers increasingly target premium residential wellness markets and industrial humidity-critical environments, while regional players focus on price-effective models to address emerging-market demand and strengthen competitive positioning.
Key Player Analysis
- Vornado Air LLC
- Boneco AG
- Honeywell International Inc.
- Mitsubishi Heavy Industries, Ltd.
- Carel INDUSTRIES S.p.A.
- Procter & Gamble Company
- Koninklijke Philips N.V.
- Armstrong International, Inc.
- Munters, Ltd.
- United Technologies Corp.
Recent Developments
- In September 2025, Dreo launched its new range of Smart Humidifier models (409S 3L, 717S 8L, and 774S 10L) as part of its 2025 Winter Launch Event, expanding its indoor humidifier portfolio
- In June 2025, Portronics launched Magma, a compact indoor device combining a built-in humidifier and night lamp, targeting improved comfort and ambiance for indoor spaces.
- In March 2025, Madison IAQ LLC (doing business as Madison Air) disclosed its intention to acquire a North America–based provider of humidification products, enhancing its residential humidification and indoor air quality offerings.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Industry Vertical Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as consumers increasingly prioritize indoor air quality, wellness, and comfort across residential and commercial environments.
- Smart and connected humidifier systems will gain wider adoption as IoT integration, automation, and remote monitoring features enhance user convenience and control.
- Energy-efficient and low-maintenance models will see rising demand as manufacturers focus on sustainability, reduced power consumption, and eco-friendly product designs.
- Healthcare, pharmaceuticals, data centers, and electronics manufacturing will continue to drive industrial-grade humidifier installations for process stability and equipment protection.
- Premium residential humidifiers with silent operation, antimicrobial features, and advanced filtration will attract urban and wellness-focused consumer segments.
- Technological innovation in ultrasonic, evaporative, and hybrid designs will strengthen product performance, durability, and operating efficiency.
- Distribution expansion through e-commerce platforms and omnichannel retail networks will enhance product accessibility in emerging and developed markets.
- Upgrading and retrofitting of HVAC systems in commercial buildings will create strong opportunities for centralized humidification solutions.
- Manufacturers will increasingly adopt modular and compact product architectures to support space-constrained urban households and institutional facilities.
- Growing regulatory focus on indoor environmental quality standards will encourage large-scale adoption of controlled-humidity solutions across multiple end-use sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Indoor Humidifier Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Indoor Humidifier Market projected to grow between 2024 and 2032?
Which Indoor Humidifier Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Indoor Humidifier Market?
Who are the leading companies in the Indoor Humidifier Market?
Which region commanded the largest share of the Indoor Humidifier Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Indoor Humidifier Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Indoor Humidifier Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,450 Million → 2032: USD 5,457.41 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Indoor Humidifier Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Indoor Humidifier Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Indoor Humidifier Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Indoor Humidifier Market Drivers
- 3.3 Indoor Humidifier Market Restraints & Challenges
- 3.4 Indoor Humidifier Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Indoor Humidifier Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Indoor Humidifier Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Indoor Humidifier category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Indoor Humidifier Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Indoor Humidifier Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Indoor Humidifier market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Indoor Humidifier Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Indoor Humidifier Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Indoor Humidifier Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Indoor Humidifier (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Indoor Humidifier Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Indoor Humidifier Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Indoor Humidifier Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Indoor Humidifier Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Indoor Humidifier Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Indoor Humidifier Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Indoor Humidifier Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Indoor Humidifier Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Indoor Humidifier Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
