
Market overview
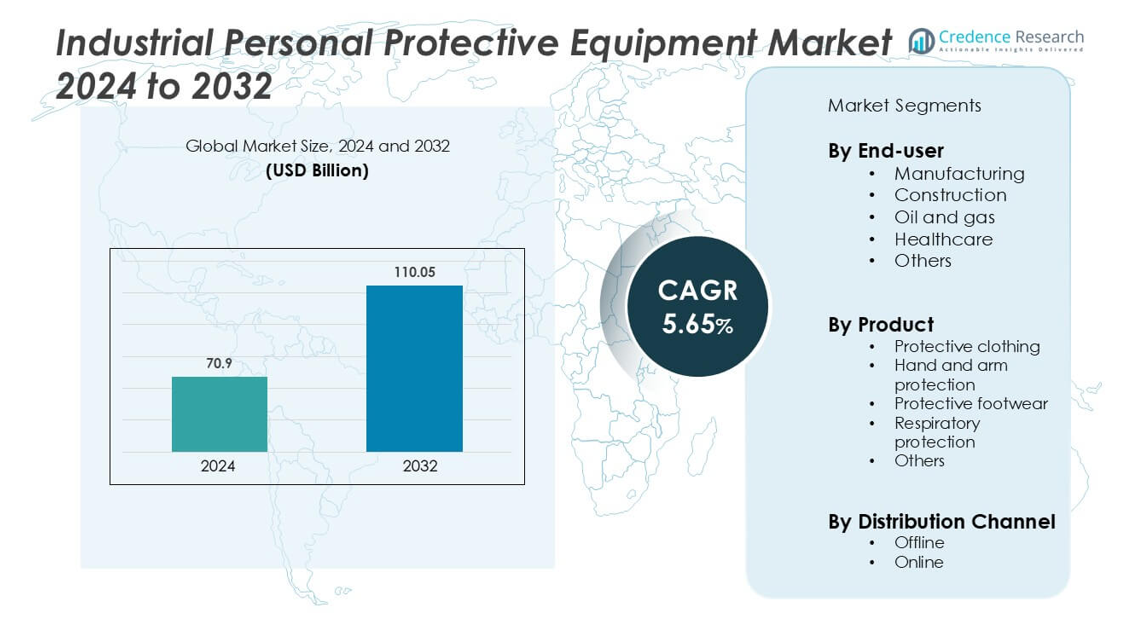
Industrial Personal Protective Equipment Market size was valued USD 70.9 billion in 2024 and is anticipated to reach USD 110.05 billion by 2032, at a CAGR of 5.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Personal Protective Equipment Market Size 2024 | USD 70.9 billion |
| Industrial Personal Protective Equipment Market, CAGR | 5.65% |
| Industrial Personal Protective Equipment Market Size 2032 | USD 110.05 billion |
The industrial personal protective equipment (PPE) market is highly competitive, led by prominent players such as DuPont, MSA Safety, Ansell Ltd., Kimberly-Clark Worldwide, Delta Plus Group, Uvex Group, Lakeland Inc., and Mallcom Limited. These companies maintain a strong global presence through advanced product portfolios, continuous innovation, and extensive distribution networks. They focus on developing technologically enhanced and ergonomically designed PPE to meet evolving safety standards across industries. North America dominates the global market, accounting for approximately 30% of total market share, driven by stringent occupational safety regulations, rapid adoption of smart PPE solutions, and high investment in industrial safety compliance.
Market Insights
- The global industrial personal protective equipment (PPE) market is valued at over USD 70.9 billion and is projected to grow at a CAGR of around 5.65% during the forecast period, driven by increasing emphasis on worker safety and regulatory compliance.
- Rising industrialization, infrastructure expansion, and stricter workplace safety mandates across manufacturing and construction sectors are major drivers boosting PPE demand globally.
- Key market trends include the adoption of smart and sustainable PPE solutions, integration of IoT-enabled monitoring devices, and the growing shift toward eco-friendly, recyclable materials.
- The market is highly competitive, with major players such as 3M, DuPont, MSA Safety, Ansell Ltd., and Delta Plus Group focusing on innovation, product diversification, and regional expansion to strengthen their market presence.
- Regionally, North America holds about 30% of the market share, while Asia-Pacific leads in growth, and the manufacturing segment remains the largest end-user category worldwide.
Market Segmentation Analysis:
By End-user
The manufacturing sector dominates the industrial personal protective equipment (PPE) market, accounting for the largest share due to stringent workplace safety regulations and high adoption of protective gear in assembly lines and heavy machinery operations. Rising automation and the need for worker safety in hazardous environments continue to drive demand. The construction segment follows closely, fueled by rapid urbanization and infrastructure projects. Meanwhile, the oil and gas and healthcare sectors contribute steadily, supported by regulatory compliance and growing awareness of occupational safety standards.
- For instance, the overall number of distinct PPE products offered by 3M is much larger. Across all industries, the 3M India website lists over 2,000 safety-related items.
By Product
Protective clothing represents the dominant product sub-segment, capturing a significant share of the industrial PPE market owing to its essential role in safeguarding workers against chemical, thermal, and mechanical hazards. Demand is further strengthened by regulatory mandates and technological innovations in flame-resistant and high-visibility fabrics. Hand and arm protection, along with protective footwear, also hold considerable market presence, driven by the need for enhanced dexterity and comfort. Growth in respiratory protection is accelerating, particularly in sectors exposed to airborne contaminants and industrial dust.
- For instance, Ansell did report selling its 500 millionth pair of HyFlex® gloves. However, this milestone was reached in November 2011, marking the 15th anniversary of the Hy Flex ® brand.
By Distribution Channel
The offline distribution channel remains the dominant segment, accounting for the majority of market share due to established supplier relationships, bulk purchasing preferences, and immediate product availability. Industrial buyers often rely on direct sales and specialized distributors for technical consultation and product assurance. However, the online channel is expanding rapidly, supported by the increasing digitalization of procurement processes, broader product accessibility, and competitive pricing. The convenience of e-commerce platforms and the rise of B2B marketplaces are expected to accelerate this segment’s growth trajectory.
Key Growth Drivers
Stringent Workplace Safety Regulations
The enforcement of strict occupational health and safety standards across industries is a major driver for the industrial personal protective equipment (PPE) market. Regulatory bodies such as OSHA, NIOSH, and the European Agency for Safety and Health at Work mandate the use of PPE to reduce workplace injuries and fatalities. Companies are increasingly investing in advanced protective solutions to ensure compliance and minimize liability risks. Regular audits and safety certifications have further increased product demand. Moreover, the growing emphasis on worker welfare and corporate safety culture has encouraged continuous product upgrades, such as ergonomically designed helmets and flame-resistant clothing, fostering sustained market expansion.
- For instance, 3M developed the SecureFit™ X5000-series safety helmet whose patented Pressure Diffusion Technology reduces forehead pressure by up to 20% compared with prior models.
Rising Industrialization and Infrastructure Development
Rapid industrialization and infrastructure growth, particularly in emerging economies, are significantly boosting the demand for PPE. The expansion of manufacturing, construction, and oil and gas sectors has led to higher employment in hazardous environments, necessitating protective gear. Mega infrastructure projects and industrial corridors in Asia-Pacific and the Middle East are major contributors to market growth. Additionally, the increasing number of small and medium enterprises (SMEs) adopting safety measures to align with international standards has widened product penetration. Continuous investments in industrial development, combined with government initiatives promoting worker safety, further strengthen the market’s growth outlook.
- For instance, DuPont launched its Nomex® Global Portfolio for manufacturing, oil & gas and utilities across Asia-Pacific, emphasising flame-resistant and arc-rated protection with global standards certification and deployment across more than one million garments annually in the region.
Technological Advancements in PPE Design and Materials
Innovation in PPE materials and smart technology integration is transforming the market landscape. Manufacturers are developing lightweight, durable, and breathable materials that enhance comfort without compromising protection. The introduction of smart PPE-featuring sensors for real-time monitoring of worker health and environmental hazards-has significantly improved workplace safety outcomes. Technologies like IoT connectivity and AI-based hazard detection are gaining traction in industries with high exposure risks. Furthermore, advancements in antimicrobial fabrics and sustainable materials align with growing environmental and health awareness, driving replacement demand and product differentiation. These innovations are reshaping user perception, making PPE more functional, efficient, and desirable.
Key Trends and Opportunities
Increasing Adoption of Sustainable and Eco-Friendly PPE
Sustainability has become a central trend in the PPE market, with growing demand for environmentally responsible products. Manufacturers are shifting toward biodegradable, recyclable, and reusable materials to reduce waste and carbon footprints. The adoption of sustainable production practices-such as waterless dyeing and the use of organic fibers-is gaining momentum, particularly in Europe and North America. This shift not only aligns with global ESG commitments but also appeals to eco-conscious end-users. Companies adopting sustainable PPE solutions can strengthen brand image while meeting compliance with evolving environmental regulations. The integration of circular economy principles presents substantial opportunities for innovation and long-term growth.
- For instance, Ansell operates the RightCycle™ Program to recycle eligible, non-hazardous PPE. In October 2025, Ansell reported that the program has successfully diverted approximately 7 million pounds of waste from landfills since 2011, which is approximately 3,175 metric tons. This lifetime figure is very close to the one cited in the claim, which suggests a misunderstanding of the timeframe.
Expansion of Digital and E-Commerce Distribution Channels
The rise of digitalization has opened new growth avenues for PPE suppliers. Online distribution channels and B2B e-commerce platforms offer greater product accessibility, price transparency, and convenience for industrial buyers. This shift is particularly evident among small and mid-sized enterprises seeking cost-effective procurement solutions. Digital platforms enable real-time inventory tracking, product customization, and global reach, significantly enhancing supply chain efficiency. Moreover, data analytics and AI-driven recommendations are being leveraged to match products with specific industry needs. As remote work and digital procurement become standard business practices, online sales are expected to play a pivotal role in shaping future market dynamics.
- For instance, 3M launched its Connected Safety system which allows tagging of PPE items via RFID or barcodes, storing equipment history and training records in the cloud for hundreds of thousands of assets.
Key Challenges
Fluctuating Raw Material Prices
Volatile raw material costs remain a major challenge for PPE manufacturers. The production of protective clothing, gloves, and footwear relies heavily on materials such as rubber, leather, plastics, and synthetic fibers, all of which are subject to price instability driven by global supply chain disruptions and crude oil fluctuations. This volatility directly impacts profit margins and product pricing. Additionally, geopolitical tensions and transportation bottlenecks have exacerbated material shortages, delaying production timelines. To mitigate these effects, companies are exploring local sourcing, material substitution, and long-term supplier contracts. However, maintaining consistent quality and affordability remains a persistent challenge for industry players.
Counterfeit and Substandard Products
The growing influx of counterfeit PPE poses a serious threat to market credibility and user safety. Low-quality imitations not only fail to meet regulatory standards but also endanger workers and undermine consumer trust. Online marketplaces, while expanding accessibility, have inadvertently facilitated the distribution of unverified products. This issue is particularly prevalent in price-sensitive markets with weak enforcement mechanisms. To counter this challenge, regulatory agencies and manufacturers are intensifying efforts to implement traceability systems, certification labels, and awareness campaigns. Despite these measures, the proliferation of counterfeit products continues to hinder legitimate market growth and compromise occupational safety outcomes.
Regional Analysis
North America
North America holds a significant share of the global industrial personal protective equipment (PPE) market, accounting for over 30% of total revenue. The region’s dominance stems from strict occupational safety regulations enforced by OSHA and growing awareness of workplace hazards. The United States leads the market with robust demand from manufacturing, oil and gas, and healthcare sectors. High adoption of technologically advanced PPE, including smart wearables and respiratory protection, further strengthens market growth. Additionally, strong supply chain infrastructure and continuous product innovation by key players sustain the region’s leadership position.
Europe
Europe represents a substantial portion of the global industrial PPE market, capturing around 25% of total market share. The region’s growth is driven by stringent European Union safety directives and high emphasis on worker health protection. Countries such as Germany, the U.K., and France are key contributors due to their developed industrial bases and advanced manufacturing sectors. The increasing adoption of sustainable and eco-friendly PPE materials aligns with the region’s environmental regulations. Continuous investments in R&D and the rise of automation across industries further enhance product demand and market competitiveness.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the industrial PPE market, accounting for approximately 28% of global revenue. Rapid industrialization, expanding manufacturing activities, and infrastructure development in countries such as China, India, and Japan drive significant demand. Governments across the region are enforcing stricter workplace safety regulations, further boosting market penetration. The rise of local PPE manufacturers offering cost-effective solutions also enhances accessibility. Additionally, increasing foreign investments in construction and energy sectors are stimulating sustained growth. Technological advancements and expanding e-commerce distribution channels contribute to the region’s accelerating market share.
Latin America
Latin America holds a moderate share of the industrial PPE market, representing nearly 10% of global revenue. Growth is primarily driven by expanding construction, mining, and oil and gas industries, particularly in Brazil and Mexico. Increasing awareness of workplace safety and gradual enforcement of regulatory standards are improving PPE adoption rates. However, price sensitivity and limited access to advanced protective equipment remain challenges. Market players are focusing on strategic partnerships and local production to enhance affordability and distribution. As industrial activities expand, the region is expected to witness steady, long-term market development.
Middle East & Africa
The Middle East and Africa account for roughly 7% of the global industrial PPE market share, supported by strong demand from oil and gas, construction, and mining sectors. Countries such as Saudi Arabia, the UAE, and South Africa are major contributors due to large-scale industrial projects and increased safety investments. Growing awareness of occupational health standards and workforce protection initiatives by regional governments further stimulate demand. However, limited local manufacturing capacity and reliance on imports constrain growth potential. Despite these challenges, infrastructure expansion and energy diversification projects continue to drive regional market opportunities.
Market Segmentations
By End-user
- Manufacturing
- Construction
- Oil and gas
- Healthcare
- Others
By Product
- Protective clothing
- Hand and arm protection
- Protective footwear
- Respiratory protection
- Others
By Distribution Channel
- Offline
- Online
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the industrial personal protective equipment (PPE) market is characterized by the presence of several global and regional players competing through product innovation, technological advancement, and strategic partnerships. Major companies such as DuPont, MSA Safety, Ansell Ltd., and Kimberly-Clark Worldwide dominate the market with extensive product portfolios and strong distribution networks. These players focus on developing advanced, comfortable, and durable protective gear integrated with smart technologies for enhanced safety monitoring. European manufacturers like Delta Plus Group and Uvex Group emphasize ergonomic design and sustainability, while Asian firms such as Mallcom Limited and Supermax Corporation Berhad expand market reach through cost-effective offerings. Strategic mergers, acquisitions, and collaborations are common, enabling companies to diversify product lines and strengthen geographic presence. The growing importance of regulatory compliance and workplace safety standards continues to intensify competition, compelling manufacturers to invest in research, quality assurance, and digital sales channels.
Key Player Analysis
- DuPont (U.S.)
- Ansell Ltd. (Australia)
- Delta Plus Group (France)
- Kimberly-Clark Worldwide, Inc. (U.S.)
- Uvex Group (Germany)
- Mallcom (India) Limited (India)
- Avon Rubber p.l.c. (U.K.)
- Lakeland Inc. (U.S.)
- Alpha ProTech (Canada)
- COFRA S.r.l. (Italy)
Recent Developments
- In May 2024, Supermax Corporation Berhad completed the acquisition of Supermax Healthcare Canada Inc. By this acquisition, Supermax Healthcare Canada Inc. became a fully-owned subsidiary of Supermax. Such development strategies would help the company enhance its product portfolio in the PPE market.
- In February 2024 Ansell Ltd. introduced a new highly textured glove called MICROFLEX Mega Texture 93-256 to the market. This orange-colored disposable nitrile glove provides a reliable grip and long-lasting protection for industrial workers. It is particularly well-suited for automotive shop employees needing a sturdy glove with tear resistance, high visibility, and excellent gripping capabilities.
- In March 2023, Ansell opened its Greenfield Manufacturing Plant in India, investing USD 80 million in the plant. The new facility aims to provide the most innovative and highest-quality surgical gloves to healthcare professionals across the country
Report Coverage
The research report offers an in-depth analysis based on End-User, Product, Distribution channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The industrial personal protective equipment market will continue expanding due to increasing emphasis on workplace safety across industries.
- Technological innovations such as smart PPE and IoT-enabled monitoring systems will enhance product functionality and adoption.
- Sustainability initiatives will drive the development of eco-friendly and recyclable protective equipment.
- Demand from emerging economies will rise with accelerating industrialization and infrastructure projects.
- Online distribution channels will gain stronger traction as digital procurement becomes mainstream.
- Manufacturers will prioritize ergonomic design and comfort to improve worker compliance and efficiency.
- Strategic collaborations and mergers will increase to expand global reach and diversify product portfolios.
- Automation and robotics in manufacturing will influence PPE design to address new safety challenges.
- Stringent regulatory standards will continue to shape innovation and product certification requirements.
- Continuous R&D investment will remain vital for differentiation and maintaining competitiveness in the global market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Industrial Personal Protective Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Industrial Personal Protective Equipment Market projected to grow between 2025 and 2032?
Which Industrial Personal Protective Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Industrial Personal Protective Equipment Market?
Who are the leading companies in the Industrial Personal Protective Equipment Market?
Which region commanded the largest share of the Industrial Personal Protective Equipment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 70.9 billion → 2032: USD 110.05 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Industrial Personal Protective Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Industrial Personal Protective Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Industrial Personal Protective Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Industrial Personal Protective Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Industrial Personal Protective Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Industrial Personal Protective Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Industrial Personal Protective Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Industrial Personal Protective Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 70.9 billion → 2032: USD 110.05 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Industrial Personal Protective Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Industrial Personal Protective Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Industrial Personal Protective Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Industrial Personal Protective Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

