
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
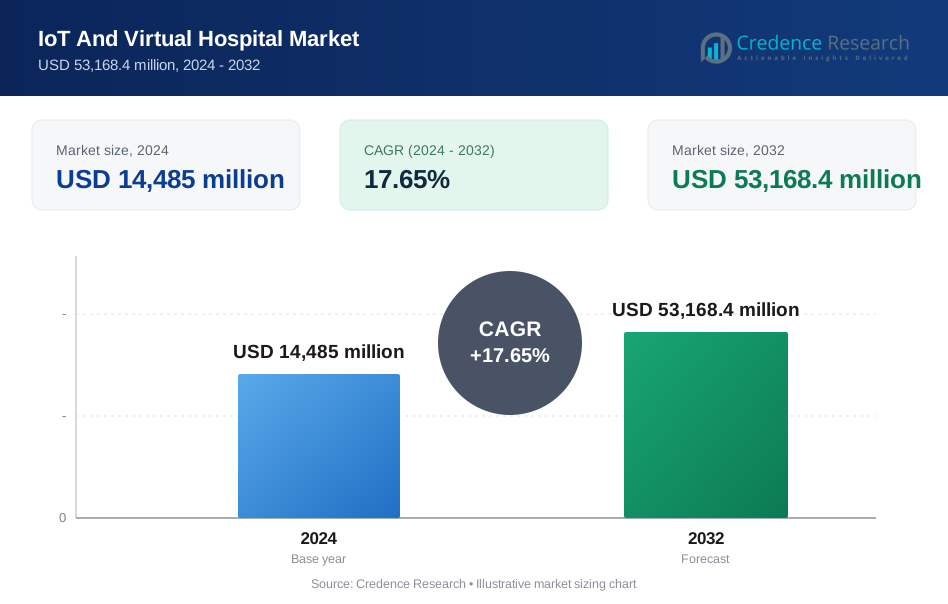
| IoT and Virtual Hospital Market Size 2024 | USD 14,485 Million |
| IoT and Virtual Hospital Market, CAGR | 17.65% |
| IoT and Virtual Hospital Market Size 2032 | USD 53,168.4 Million |
Market Overview
The IoT and Virtual Hospital market is projected to grow from USD 14,485 million in 2024 to USD 53,168.4 million by 2032, representing a compound annual growth rate (CAGR) of 17.65%.
The IoT and Virtual Hospital market is driven by increasing demand for remote patient monitoring and telehealth solutions, which enhance healthcare accessibility and efficiency. Technological advancements in IoT devices facilitate real-time data collection and analysis, improving patient outcomes. The rising prevalence of chronic diseases further fuels the need for innovative healthcare solutions. Additionally, growing investments in healthcare IT infrastructure and a shift towards value-based care models are shaping market trends. As healthcare providers adopt virtual hospital systems, the integration of IoT technologies continues to transform patient care delivery and operational efficiency in the healthcare sector.
The IoT and virtual hospital market is experiencing significant growth across various regions, with North America and Europe leading in adoption due to advanced healthcare infrastructure and technology integration. Key players driving innovation in this market include Oracle, IBM, and Medtronic, which focus on developing cutting-edge solutions to enhance patient care. In Asia-Pacific, increasing investments in telemedicine and remote monitoring technologies are expanding market opportunities. As healthcare providers prioritize digital transformation, the presence of major companies like Siemens and GE Healthcare further strengthens the competitive landscape, ensuring a diverse range of offerings to meet evolving consumer needs.
Market Drivers
Rising Demand for Remote Patient Monitoring
The increasing prevalence of chronic diseases drives the demand for remote patient monitoring through IoT devices. These technologies enable continuous tracking of vital signs and health metrics, facilitating timely interventions and enhancing patient outcomes. For instance, remote patient monitoring devices enable healthcare professionals to examine and track a patient’s chronic or acute problems away from a clinic or hospital, encouraging regular interaction and understanding of a patient’s health. Additionally, remote monitoring is vital for elderly care, ensuring the safety and well-being of seniors living independently. IoT-enabled virtual hospitals also expand access to healthcare services for geographically dispersed populations, allowing individuals in remote or underserved areas to receive essential medical attention.
Increasing Adoption of Telehealth
Telehealth is gaining traction as a convenient and accessible healthcare solution, significantly reducing the need for in-person visits. This adoption is largely facilitated by IoT devices and virtual platforms, which streamline patient-provider interactions. For instance, telehealth utilization rapidly expanded during the onset of the COVID-19 pandemic and continues to provide critical access to healthcare services. Furthermore, telehealth services contribute to cost-effectiveness by decreasing hospital admissions and emergency room visits, ultimately lowering healthcare expenses for both providers and patients.
Advancements in Technology
Recent advancements in technology are transforming the healthcare landscape, particularly through the development of smaller, more affordable, and reliable IoT devices. These innovations simplify the integration of IoT technology into healthcare settings. Moreover, advancements in data analytics empower healthcare providers to derive valuable insights from the vast amounts of data generated by IoT devices, enabling more informed decision-making and improved patient care.
Growing Healthcare Costs and Government Initiatives
The escalating costs of healthcare necessitate efficient solutions, and IoT and virtual hospitals offer potential cost reductions by enhancing operational efficiency, minimizing waste, and preventing avoidable hospitalizations. Government initiatives play a crucial role in this landscape, as policymakers around the globe support the adoption of IoT technologies and virtual hospitals through funding and regulatory frameworks. This concerted effort promotes a shift towards more effective and sustainable healthcare delivery systems.
Market Trends
Integration with AI and Cloud-Based Solutions
The integration of artificial intelligence (AI) and machine learning (ML) with IoT devices is revolutionizing healthcare through enhanced predictive analytics and personalized care. AI algorithms can analyze vast amounts of data collected from IoT devices, identifying health risks and optimizing treatment plans tailored to individual patients. For instance, according to a survey by Google Cloud, AI tools have been used to analyze electronic health records and medical imaging, leading to improved disease classification and prognosis. This proactive approach enables healthcare providers to intervene early, improving patient outcomes significantly. Additionally, AI-powered virtual assistants offer personalized recommendations, guiding patients in their care journey. Simultaneously, cloud-based solutions play a crucial role in this transformation, providing scalability and flexibility that healthcare providers need to adapt to evolving demands. With robust data security measures, cloud platforms protect sensitive patient information, ensuring compliance with privacy regulations. The synergy between AI and cloud technologies fosters an agile healthcare environment where providers can respond efficiently to patient needs while maintaining high standards of data protection.
Wearable Technology and Remote Surgery
Wearable technology is another trend significantly impacting the IoT and virtual hospital market. Devices such as smartwatches and fitness trackers enable continuous monitoring of vital signs and physical activity, enhancing patient engagement and adherence to treatment plans. This real-time data empowers patients to take an active role in their health management, leading to better adherence to prescribed regimens. Furthermore, the emergence of remote surgery is facilitated by IoT-enabled devices and high-speed networks, making certain procedures more feasible from afar. This innovation improves access to care, particularly for patients in remote or underserved areas, bridging the gap between healthcare providers and those in need. The focus on interoperability and standardization further enhances these trends, as seamless data exchange between different IoT devices and healthcare systems becomes essential. Regulatory developments also play a vital role in ensuring that these advancements are safe and effective, providing a framework for compliance and security in the rapidly evolving landscape of IoT-enabled healthcare solutions. Overall, these trends collectively contribute to a more interconnected and responsive healthcare ecosystem.
Market Challenges Analysis
Data Privacy, Security, and Interoperability Challenges
The IoT and virtual hospital market faces significant challenges related to data privacy and security, particularly concerning the sensitive patient information collected by IoT devices. Protecting this data from unauthorized access and breaches is paramount, especially given the increasing frequency of cybersecurity threats, such as ransomware attacks and data theft targeting healthcare organizations. For instance, a survey conducted by a leading cybersecurity firm revealed that a substantial number of healthcare organizations experienced data breaches in the past year, highlighting the urgent need for robust security measures. Moreover, ensuring seamless data exchange between various IoT devices and healthcare systems poses a complex challenge. The absence of standardized protocols and data formats can hinder the adoption and integration of these solutions, creating inefficiencies in patient care and data management. As the interconnectedness of healthcare systems grows, addressing these privacy and interoperability concerns becomes critical to maintaining patient trust and ensuring optimal care delivery.
Regulatory Compliance, Cost, and Adoption Barriers
Regulatory compliance is another major hurdle for healthcare providers as they navigate a complex web of regulations pertaining to data privacy, patient safety, and device certification. The evolving regulatory landscape makes it difficult for organizations to keep pace with the latest requirements, potentially exposing them to penalties and compliance issues. Financial constraints also play a significant role in the adoption of IoT and virtual hospital solutions, as initial implementation costs for hardware, software, and infrastructure can be substantial. Demonstrating a clear return on investment remains a challenge, especially when the benefits of these technologies may not be immediately apparent. Additionally, healthcare providers often exhibit resistance to change, which can slow down the integration of new technologies. Training the workforce to effectively use IoT and virtual hospital solutions requires significant time and resources, further complicating the transition. Addressing these multifaceted challenges will be essential for fostering the widespread adoption of IoT-enabled healthcare innovations, ultimately enhancing patient care and operational efficiency.
Market Segmentation Analysis:
By Component:
The IoT and virtual hospital market is primarily segmented by component, encompassing hardware, software and services, and connectivity devices. Hardware dominates this market segment, including IoT devices such as sensors, wearables, and medical equipment that enable continuous monitoring and data collection. These devices are critical for real-time health assessments and facilitate remote patient care. Software and services, which include applications for data analytics, patient management, and telehealth solutions, are essential for interpreting the vast amounts of data generated by hardware. As healthcare providers increasingly adopt digital solutions, this segment is expected to witness substantial growth. Connectivity devices, such as routers and gateways, ensure reliable communication between various components, enabling seamless data exchange across healthcare systems. Together, these components create a comprehensive ecosystem that enhances patient care, streamlines operations, and supports the transition to more connected healthcare environments.
By Application The application segment of the IoT and virtual hospital market includes remote patient monitoring, telemedicine, store and forward telemedicine, mHealth, and others. Remote patient monitoring is gaining traction as it allows healthcare providers to track patients’ vital signs and health metrics outside traditional clinical settings, improving chronic disease management. Telemedicine facilitates real-time consultations between patients and providers, enhancing accessibility and convenience. Store and forward telemedicine allows healthcare professionals to share patient data asynchronously, improving diagnostic capabilities. mHealth applications leverage mobile technology to engage patients in their healthcare, promoting adherence to treatment plans. The diverse applications within this segment highlight the versatility of IoT and virtual hospitals, catering to a wide range of healthcare needs. As demand for these applications grows, driven by the need for efficient and accessible healthcare solutions, the market is poised for significant expansion.
Segments:
Based on Component:
- Hardware
- Software and Services
- Connectivity Devices
Based on Application:
- Remote Patient Monitoring
- Telemedicine
- Store and Forward Telemedicine
- mHealth
- Others
Based on End User:
- Hospitals and Surgical Centers
- Clinical Research Organizations
- Government and Defense Organizations
- Research and Diagnostics Laboratories
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American region holds a dominant position in the IoT and virtual hospital market, accounting for approximately 40% of the global market share. This significant presence is driven by advanced healthcare infrastructure, widespread adoption of technology, and increasing investment in digital health solutions. The United States, in particular, leads the way with robust government initiatives supporting telehealth and remote monitoring technologies. Healthcare providers are increasingly leveraging IoT devices to enhance patient care, streamline operations, and reduce costs. Additionally, the rise of chronic diseases and an aging population are prompting healthcare systems to adopt more effective and efficient solutions, further fueling market growth in this region.
Asia-Pacific
In the Asia-Pacific region, the IoT and virtual hospital market is experiencing rapid expansion, capturing around 25% of the global market share. Countries like China and India are at the forefront, driven by rising healthcare demands and a growing population. The increasing penetration of mobile technology and internet connectivity is facilitating the adoption of telemedicine and remote monitoring solutions. Moreover, government initiatives aimed at improving healthcare access in rural areas are significantly contributing to market growth. The emphasis on affordable healthcare solutions and the integration of technology in healthcare delivery systems are propelling the acceptance of IoT and virtual hospitals. As these trends continue, the Asia-Pacific region is expected to witness substantial advancements in healthcare technology, enhancing patient outcomes and operational efficiency.
Key Player Analysis
- Oracle
- IBM
- Medtronic
- Siemens
- Microsoft
- Koninklijke Philips
- Cerner
- GE Healthcare
- Allscripts
- McKesson
Competitive Analysis
The IoT and virtual hospital market is characterized by intense competition among leading players such as Microsoft, IBM, Oracle, GE Healthcare, Siemens, Cerner, Allscripts, McKesson, Koninklijke Philips, and Medtronic. These companies are at the forefront of technological innovation, focusing on developing integrated solutions that enhance patient care and streamline healthcare operations. They leverage advanced analytics, artificial intelligence, and cloud computing to deliver efficient remote monitoring, telemedicine, and data management solutions. Strategic partnerships and collaborations are common, allowing these firms to expand their market reach and improve service offerings. Additionally, ongoing investments in research and development enable them to address emerging healthcare challenges and meet evolving regulatory standards. This dynamic environment fosters competition, driving advancements that improve patient outcomes and operational efficiencies in virtual healthcare delivery systems.
Recent Developments
- In September 2024, Oracle Health continues to deliver electronic health record (EHR) innovations that help clinicians streamline routine tasks and deliver more efficient, informed patient care.
- In June 2024, IBM, Cleveland Clinic, and the Hartree Centre announced a collaboration to advance healthcare and biomedical science through advanced computing technologies, including AI and quantum computing.
- In April 2024, Medtronic unveiled the future of AI in GI with the launch of ColonPRO™, the latest generation software for the GI Genius™ intelligent endoscopy system.
- In January 2024, Siemens delivered innovations in immersive engineering and artificial intelligence to enable the industrial metaverse at CES 2024.
- In March 2024, Microsoft announced new collaborations with healthcare organizations and partners to make the promise of AI in healthcare real.
Market Concentration & Characteristics
The IoT and virtual hospital market exhibits a moderate level of market concentration, with several key players dominating the landscape while numerous smaller firms contribute to its diversity. Leading companies, such as Microsoft, IBM, and GE Healthcare, leverage their technological expertise and substantial resources to drive innovation and enhance service offerings. This concentration enables these firms to achieve economies of scale, improving efficiency and reducing costs. Key characteristics of the market include a strong emphasis on interoperability, ensuring seamless integration of IoT devices with existing healthcare systems. Additionally, the market is marked by rapid technological advancements, including the integration of artificial intelligence and machine learning for predictive analytics. As healthcare providers increasingly adopt virtual solutions, there is a growing focus on data security and regulatory compliance to protect sensitive patient information. Overall, the IoT and virtual hospital market is evolving rapidly, characterized by innovation, collaboration, and an increasing demand for efficient healthcare solutions.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The IoT and virtual hospital market is expected to experience substantial growth driven by rising demand for remote healthcare solutions.
- Advancements in AI and machine learning will enhance predictive analytics, improving patient outcomes.
- Increased adoption of wearable technology will enable continuous monitoring and better patient engagement.
- Cloud-based solutions will gain traction, offering scalability and flexibility for healthcare providers.
- Greater emphasis on data security and privacy will shape the development of IoT healthcare solutions.
- Regulatory frameworks will evolve to better accommodate the integration of IoT technologies in healthcare.
- Telemedicine services will expand, providing convenient access to healthcare for diverse populations.
- The market will see innovations in interoperability standards, facilitating seamless data exchange between systems.
- Collaborative partnerships among tech companies and healthcare providers will drive further advancements.
- Growing consumer acceptance of virtual healthcare options will solidify the role of IoT in mainstream healthcare delivery.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the IoT And Virtual Hospital Market?
What factors are driving the growth of the IoT And Virtual Hospital Market?
What are the key segments within the IoT And Virtual Hospital Market?
What are some challenges faced by the IoT And Virtual Hospital Market?
Who are the major players in the IoT And Virtual Hospital Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 IoT And Virtual Hospital Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global IoT And Virtual Hospital Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 14,485 million → 2032: USD 53,168.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 IoT And Virtual Hospital Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. IoT And Virtual Hospital Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 IoT And Virtual Hospital Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 IoT And Virtual Hospital Market Drivers
- 3.3 IoT And Virtual Hospital Market Restraints & Challenges
- 3.4 IoT And Virtual Hospital Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 IoT And Virtual Hospital Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 IoT And Virtual Hospital Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, IoT And Virtual Hospital category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 IoT And Virtual Hospital Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. IoT And Virtual Hospital Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the IoT And Virtual Hospital market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 IoT And Virtual Hospital Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 IoT And Virtual Hospital Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 IoT And Virtual Hospital Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in IoT And Virtual Hospital (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New IoT And Virtual Hospital Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global IoT And Virtual Hospital Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America IoT And Virtual Hospital Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe IoT And Virtual Hospital Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific IoT And Virtual Hospital Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America IoT And Virtual Hospital Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East IoT And Virtual Hospital Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa IoT And Virtual Hospital Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. IoT And Virtual Hospital Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
