
Market Definition
The Japanese micronutrients market encompasses the sector involved in the production, distribution, and application of essential trace elements, including minerals and vitamins, that are critical for the healthy growth and development of crops. These micronutrients are utilized in agriculture to address specific nutrient deficiencies in soils and plants, ensuring optimal crop yield, quality, and overall resilience. The market includes various micronutrient products, such as fertilizers and soil amendments, designed to enhance the nutrient content of agricultural land, promoting sustainable farming practices. The industry is characterized by ongoing research, product innovation, and the adoption of advanced agricultural technologies to maximize the efficiency of micronutrient utilization, minimize environmental impact, and support the evolving needs of the agricultural sector in Japan.
Market Overview
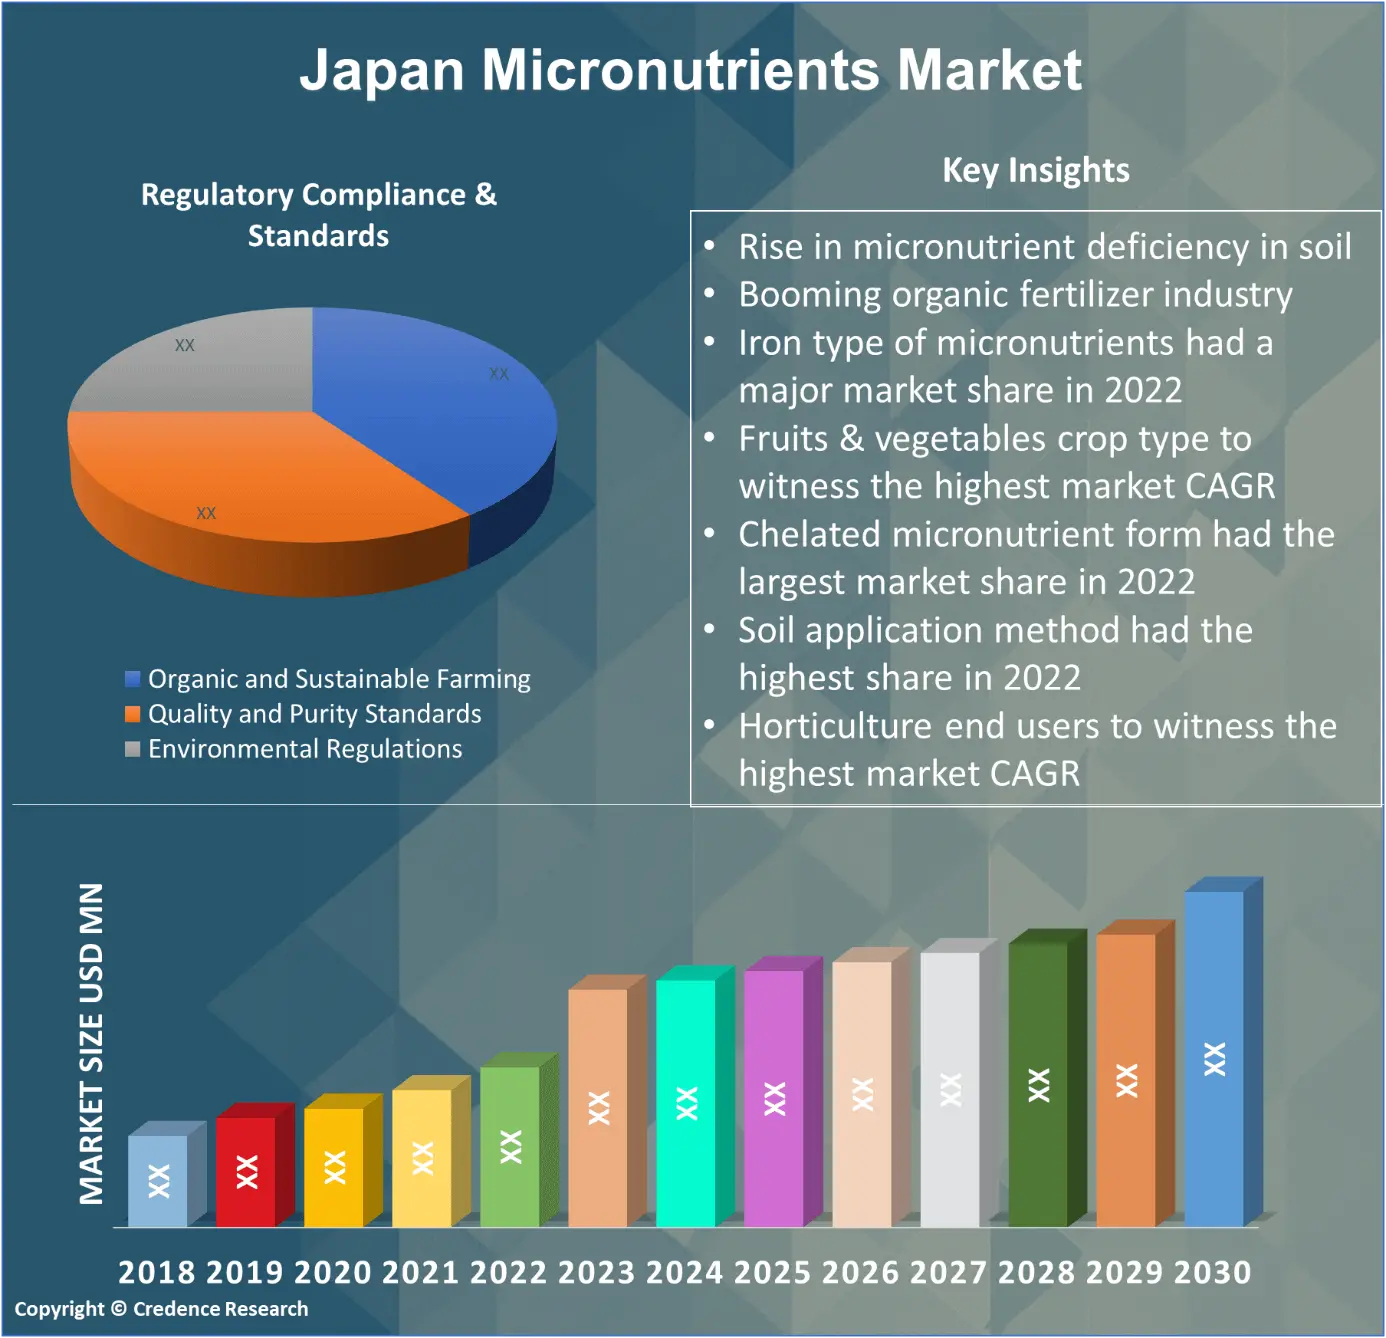
The Japan micronutrient market has witnessed rapid growth in recent years and is expected to grow at a CAGR of 7.8% between 2023 and 2030. The market was valued at USD XX million in 2022 and is expected to reach USD XX million in 2030.
Micronutrients, including essential minerals and vitamins, are important in enhancing soil fertility and promoting healthy crop growth. In recent years, there has been an increasing awareness of the importance of micronutrients in addressing soil nutrient deficiencies and optimizing crop yield and quality. Government initiatives and subsidies support the use of micronutrients, further encouraging their adoption in Japanese agriculture.
The market is characterized by a focus on sustainability, with a growing emphasis on organic and eco-friendly farming practices, driving rapid demand for micronutrients compliant with these standards. Precision farming technologies, such as precision irrigation and data-driven nutrient management, are gaining prominence, enabling efficient and precise micronutrient applications. With diverse soil types and climatic conditions across Japan, customized solutions for specific crops and microclimates are essential.
Market Insights
- The Japanese demand for micronutrients market was valued at USD XX million in 2022 and is expected to reach USD XX million in 2030, growing at a CAGR of 7.8% between 2023 and 2030.
- The iron segment is the market leader by the type of micronutrients, accounting for more than 25% of total value in 2022, while the zinc segment is likely to grow rapidly throughout the projection period.
- The cereals dominate the market need for micronutrients in terms of crop type, accounting for more than 30% in 2022.
- The soil application method segment accounted for the largest market share of over 22% in 2022 and is anticipated to register the highest CAGR over the estimated period.
- The chelated micronutrients segment dominated the market with 28% of the total revenue share by form of micronutrients. In contrast, the liquid micronutrients category will expand fastest in the upcoming years.
- The horticulture end user is predicted to grow fastest over the projection period, while the agriculture segment had a market share of more than 32% in 2022.
- The organic & sustainable farming category is the market leader in regulatory compliance and standards, accounting for more than 38% of total value in 2022, while the quality & purity standards segment is expected to grow fastest over the forecasted period.
- Japan has been embracing precision agriculture practices, using technology and data-driven approaches to optimize the application of micronutrients and improve resource use efficiency in farming.
- Continuous product innovation is a key market trend, with companies developing new formulations and delivery methods for micronutrient fertilizers to ensure better crop nutrient uptake.
- Agriculture in Japan is seeing a notable shift towards customized nutrient solutions, where micronutrient applications are customized to specific crops and soil conditions for optimal results.
Segmentation by Type of Micronutrients
- The zinc segment will exhibit the highest CAGR in the projected period. Zinc micronutrients are gaining wider significance in promoting crop health and yield.
- In 2022, the iron micronutrient segment held the largest market share, accounting for over 25%. Iron micronutrients are widely used to address iron deficiencies in various crops.
Segmentation by Crop Type
- Cereals emerge as the dominant crop type category, representing more than 30% of the market demand for micronutrients in 2022. Cereals commonly benefit from micronutrient applications to enhance yield and grain quality.
- The fruits & vegetables segment caters to the remaining requirements in the micronutrient market. Micronutrient applications in this segment aim to improve the nutritional quality and appearance of fruits and vegetables.
Segmentation by Form of Micronutrients
- The liquid micronutrients segment is expected to grow significantly over the forecast period. Liquid micronutrient formulations are mainly preferred for their ease of application and rapid nutrient absorption.
- Chelated micronutrients lead the market share, accounting for over 28% in 2022. Chelates are largely favored for their stability and improved nutrient availability to plants.
Segmentation by End User
- The horticulture segment is expected to record the highest CAGR during the projection period. Horticulturists rely on micronutrients to optimize the growth and quality of ornamental plants, flowers, and specialty crops.
- Agriculture holds the largest market share, representing nearly 32% in 2022. Micronutrient applications in traditional agriculture aim to enhance crop yields and overall productivity.
Segmentation by Application Method
- The fertigation segment is projected to achieve the highest CAGR in the estimated period. Fertigation, which involves the incorporation of micronutrients into irrigation systems, is gaining prominence for precise nutrient delivery.
- Soil application currently leads with a market share of nearly 22% in 2022. Soil applications are majorly preferred for introducing micronutrients to the root zone of crops.
Segmentation by Regulatory Compliance & Standards
- Organic & sustainable farming leads the market demands for micronutrients, representing more than 38% in 2022. Micronutrient products compliant with organic and sustainable farming practices are in high demand, aligning with the trend towards eco-friendly agriculture.
- Quality & purity standards address the remaining market demand for micronutrients. Ensuring the quality and purity of micronutrient products is critical to meeting regulatory requirements and ensuring the effectiveness of these essential nutrients in crop production.
Key Highlights of the Report
The Japan micronutrient market is segmented by type of micronutrients, crop type, form of micronutrients, application method, end user, regulatory compliance & standards. The zinc micronutrient segment is projected to exhibit the highest CAGR, underlining the increasing importance of zinc in crop health and yield enhancement. Cereals represent the dominant crop type category, benefiting from micronutrient applications to boost yield and quality. Liquid micronutrients are gaining prominence owing to their ease of application and rapid nutrient absorption. Fertigation, incorporating micronutrients into irrigation systems, is a growing application method for precise nutrient delivery. The horticulture segment is expected to record the highest CAGR by the end user, as horticulturists rely on micronutrients for ornamental and specialty crop growth. Micronutrients compliant with organic and sustainable farming practices are in higher demand, aligning with eco-friendly agriculture trends.
The growing awareness of the critical role of micronutrients in crop health, the pressing need to address soil nutrient deficiencies, government initiatives promoting micronutrient use, and the adoption of precision farming technologies that optimize nutrient application are driving the growth of the Japanese micronutrients market. However, the market faces restraints in the form of stringent regulatory standards and compliance, the diverse and complex agricultural landscape in Japan, which demands region-specific solutions, and the challenge of customizing micronutrient formulations to meet varying crop and microclimate requirements.
What Are The Main Drivers Of The Japan Micronutrients Market?
The Japan micronutrients market growth is primarily driven by the increasing recognition of the crucial role of micronutrients in promoting healthy crop growth and addressing nutrient deficiencies in soil. Factors such as soil degradation, micronutrient deficiencies, and a growing emphasis on sustainable and high-quality crop production have spurred market demand for micronutrient-rich fertilizers. Increasing government initiatives, subsidies, and the adoption of advanced agricultural technologies further promote the use of micronutrients in Japan. Emerging precision farming techniques and innovative fertilizers enhance nutrient efficiency, supporting Japanese farmers in achieving higher crop yields and quality.
What Are The Major Challenges Faced By The Japan Micronutrients Market?
The Japanese micronutrient market faces several key challenges, including stringent regulatory standards and compliance requirements, which demand rigorous testing and quality assurance, increasing the cost and time associated with product development and marketing. Besides, the market must address the unique complexities of Japanese agriculture, including limited arable land, changing weather patterns, and varying soil types, making it challenging to implement a uniform approach to micronutrient application. Economic factors, such as fluctuating commodity prices, further affect the purchasing power of farmers and their willingness to invest in micronutrient products.
What Are The Growth Opportunities In The Japan Micronutrients Market?
The Japan micronutrient market offers substantial growth opportunities, including expanding micronutrient applications in niche crops, such as high-value fruits and vegetables, and the flourishing greenhouse and controlled environment agriculture sector. The market can benefit from further technological advancements, particularly in precision farming and data-driven nutrient management, which optimize micronutrients and minimize waste. Collaboration with research institutions and partnerships with agricultural associations provide avenues for knowledge sharing and developing best practices in micronutrient use. Moreover, addressing the specific nutritional requirements of various crops and developing customized nutrient solutions can open new market segments and cater to the evolving needs of Japanese agriculture.
Market Drivers
Several factors drive the micronutrient market in Japan. The following are the key drivers of the micronutrient market in Japan:
Increased Government Initiatives and Subsidies
The Japanese government has actively promoted micronutrients in agriculture through various initiatives and subsidy programs. These government-backed schemes aim to encourage farmers to adopt micronutrient-rich fertilizers and raise awareness about their benefits. Financial incentives in the form of subsidies and grants make these products more accessible to farmers, reducing the cost barriers associated with their use.
Moreover, the government conducts educational programs and provides resources to educate farmers about the advantages of using micronutrients and best practices for their application. These initiatives have not only increased awareness but have also helped in changing farmer behavior, contributing to the widespread adoption of micronutrient fertilizers in Japanese agriculture.
Market Restraints
The micronutrient market faces challenges that may hinder its growth in Japan. These include the following:
Varied Soil Conditions and Climate
Diverse soil types and climate conditions characterize the Japanese agricultural landscape due to its geographical diversity. From Hokkaido's cold, northern regions to the subtropical climate of Okinawa, the soil properties and weather patterns vary significantly. This diversity presents a challenge for uniform micronutrient application and necessitates region-specific solutions. Tailoring micronutrient products to suit the specific needs of various crops and microclimates can be resource-intensive and complex. It also requires additional research & development efforts, further complicating the supply chain. Consequently, addressing the unique complexities of Japanese agriculture, including limited arable land, changing weather patterns, and varying soil types, poses a notable challenge for the micronutrient market.
Opportunities
The micronutrient market offers major growth opportunities in Japan. These include the following:
Growing Adoption of Precision Farming Technologies
The rising adoption of precision farming technologies in Japan presents a significant opportunity for agricultural micronutrient market developments. Precision agriculture involves using advanced technologies such as GPS-guided tractors, drones, and sensors to monitor and manage crop fields accurately. These technologies enable farmers to analyze soil conditions, crop health, and nutrient levels with precision.
Farmers can optimize micronutrient dosage and timing by integrating micronutrient treatments into precision farming practices, ensuring effective crop nutrient utilization. The precise application of micronutrients customized to specific soil and crop requirements not only enhances crop yield and quality but also minimizes waste, making it a compelling opportunity for micronutrient manufacturers and suppliers in the Japanese market.
Competitive Landscape
Key Players
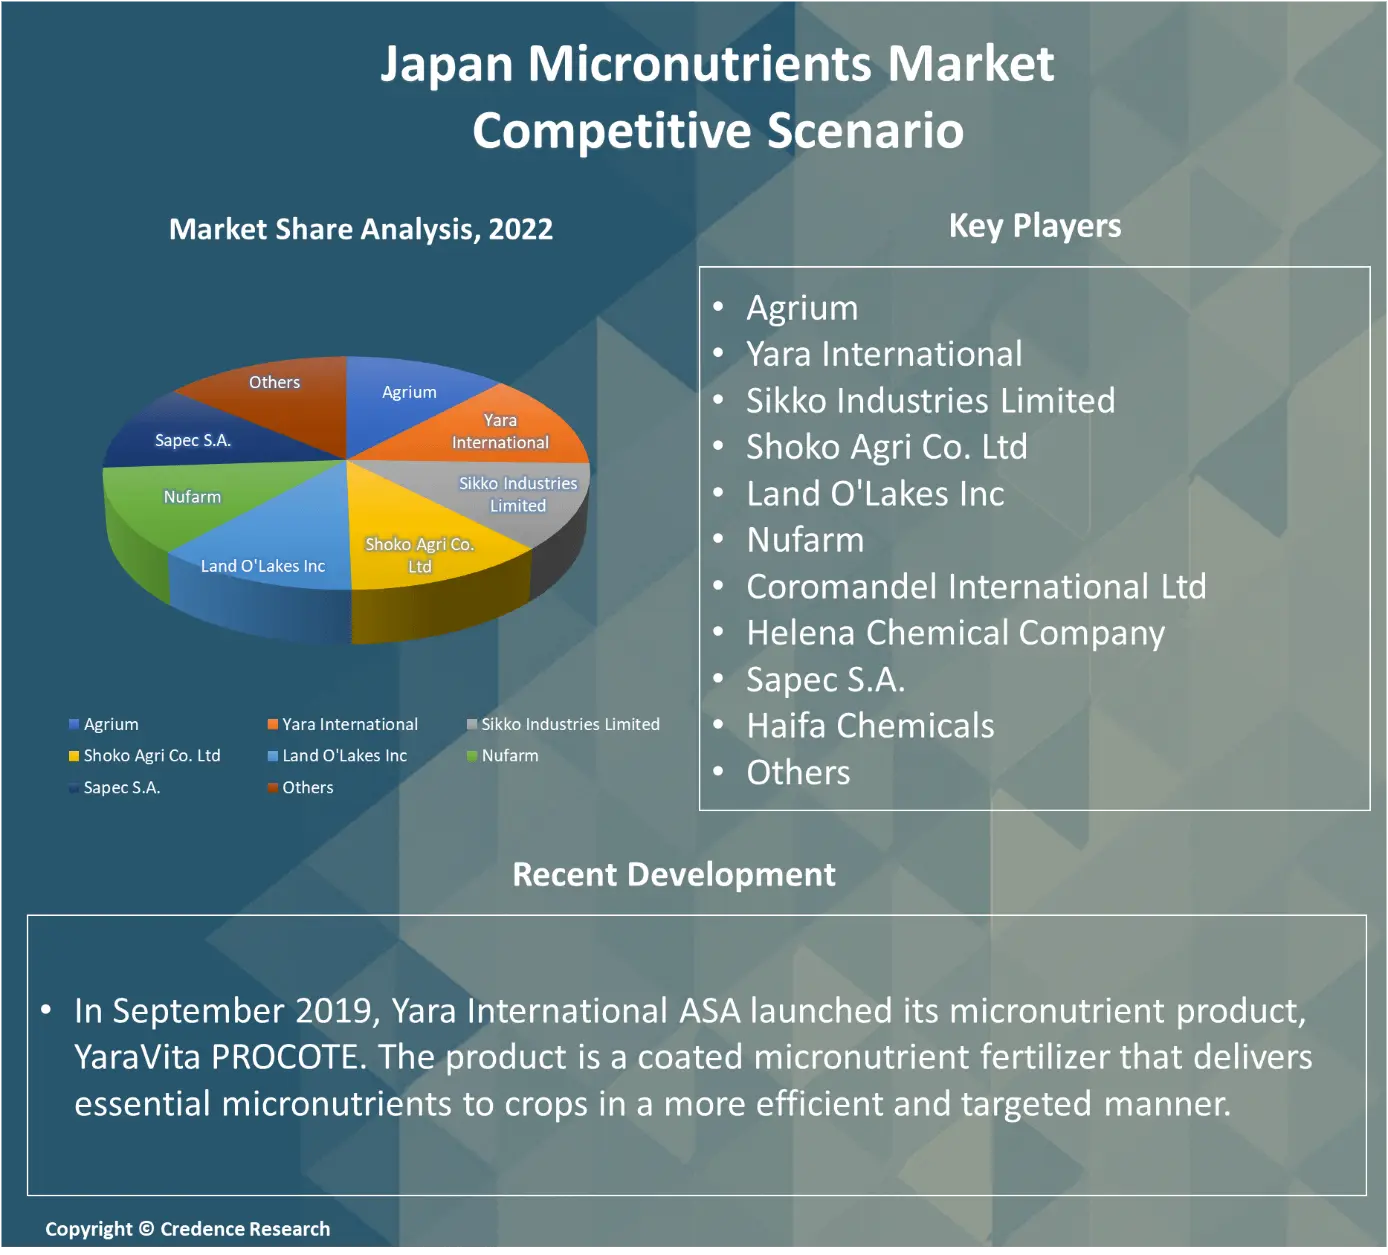
The competitive landscape of the Japanese micronutrient market is marked by the presence of numerous domestic and international players. The following are some of the top market players and their market shares:
- Agrium
- Yara International
- Sikko Industries Limited
- Shoko Agri Co. Ltd
- Land O'Lakes Inc
- Nufarm
- Coromandel International Ltd
- Helena Chemical Company
- Sapec S.A.
- Haifa Chemicals
- Others
These leading companies actively focus on product innovation and development, with a strong emphasis on formulating micronutrient solutions that cater to the specific nutritional needs of different crops. They also invest in precision agriculture technologies to offer data-driven nutrient management solutions, enhancing the efficiency of micronutrient applications. Moreover, partnerships with agricultural research institutions and government agencies are common market strategies, enabling knowledge sharing and the development of best practices.
In February 2019, Haifa Group introduced NutriNet, an innovative digital tool for growers & agronomy professionals to improve the process of establishing customized fertilization programs. This tool can help integrate data on crops, soil type, water analysis, irrigation system configuration, and other grower preferences, which would assist in farmer decision-making.
Summary of Key Findings
- The Japanese agricultural micronutrient market has witnessed a growing demand for micronutrient fertilizers due to their role in enhancing crop yields, improving product quality, and addressing soil nutrient deficiencies.
- Market segmented by type of micronutrients, crop type, form of micronutrients, application method, end user, regulatory compliance & standards.
- The widespread use of precision farming equipment, such as variable rate technology (VRT), has enabled Japanese farmers to administer micronutrients more precisely, minimizing waste and environmental effects.
- Soil testing and analysis services have gained importance as they help farmers assess nutrient deficiencies and make informed decisions on using micronutrients to enhance crop health and productivity.
- Urban and vertical farming practices in Japan are incorporating micronutrient applications to maximize yield and crop quality in limited spaces, contributing to the growth of the market.
- Weather fluctuations and climate change challenges in Japan are leading to increased adoption of micronutrients as part of climate-resilient agriculture practices.
Future Outlook
- Digital platforms and apps that provide recommendations for micronutrient applications based on real-time data are becoming more prevalent in Japan, helping farmers make data-driven decisions.
- Advances in biotechnology and crop genetics will likely influence the development of micronutrient-rich crop varieties.
- Greenhouse and controlled environment agriculture, gaining popularity in Japan, often relies on micronutrients to optimize crop growth and health in controlled conditions.
Segmentation
- By Type of Micronutrients
- Iron
- Zinc
- Manganese
- Copper
- Boron
- Molybdenum
- Chlorine
- Others
- By Crop Type
- Cereals
- Fruits and Vegetables
- Oilseeds and Pulses
- Horticulture and Ornamental Plants
- Others
- By Form of Micronutrients
- Chelated Micronutrients
- Non-Chelated Micronutrients
- Liquid Micronutrients
- Powder or Granular Micronutrients
- Soluble Powders
- Others
- By End User
- Agriculture
- Horticulture
- Food and Beverage Industry
- Nutraceuticals and Supplements
- Others
- By Application Method
- Soil Application
- Foliar Spray
- Fertigation
- Seed Treatment
- Hydroponics and Soilless Systems
- Others
- By Regulatory Compliance & Standards
- Organic and Sustainable Farming
- Quality and Purity Standards
- Environmental Regulations

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increased Government Initiatives and Subsidies
The Japanese government actively promotes the use of micronutrients in agriculture through subsidies, grants, and educational programs, making these products more accessible and encouraging widespread adoption among farmers.
Growing Emphasis on Sustainable and Organic Farming
Rising consumer and regulatory focus on sustainability and eco-friendly practices is driving demand for micronutrient products that comply with organic and sustainable farming standards, especially as Japanese agriculture shifts toward environmentally responsible methods.
Adoption of Precision Farming Technologies
The integration of advanced technologies such as GPS-guided equipment, sensors, and data-driven nutrient management enables precise application of micronutrients, improving crop yields and resource efficiency while minimizing environmental impact.
Addressing Soil Nutrient Deficiencies and Degradation
Increasing awareness of soil degradation and micronutrient deficiencies in Japanese farmland is prompting farmers to use specialized micronutrient fertilizers to restore soil health and optimize crop productivity.
Product Innovation and Customization
Ongoing research and development efforts are leading to new formulations and delivery methods for micronutrients, including customized solutions tailored to specific crops and microclimates, supporting the diverse needs of Japanese agriculture.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the expected growth rate of the Japan micronutrient market between 2023 and 2030?
Which segment is leading the market share in terms of type of micronutrients?
Which form of micronutrient segment governs demand for the Japanese micronutrient market?
Which application method segment will post the highest CAGR in the forecast period?
Who are the major players in the Japanese micronutrient market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Crop Type
- 1.2.1 Cereals
- 1.2.2 Fruits and Vegetables
- 1.2.3 Oilseeds and Pulses
- 1.2.4 Horticulture and Ornamental Plants
- 1.3 By Application Method
- 1.3.1 Soil Application
- 1.3.2 Foliar Spray
- 1.3.3 Fertigation
- 1.3.4 Seed Treatment
- 1.4 By Form of Micronutrients
- 1.4.1 Chelated Micronutrients
- 1.4.2 Non-Chelated Micronutrients
- 1.4.3 Liquid Micronutrients
- 1.4.4 Powder or Granular Micronutrients
- 1.5 By Type of Micronutrients
- 1.5.1 Iron
- 1.5.2 Zinc
- 1.5.3 Manganese
- 1.5.4 Copper
- 1.5.5 Boron
- 1.5.6 Molybdenum
- 1.5.7 Chlorine
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Micronutrient Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Micronutrient Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Micronutrient Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Micronutrient Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Micronutrient Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Micronutrient Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Micronutrient Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Micronutrient Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Micronutrient Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Crop Type - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cereals
- 12.3.7.2 Fruits and Vegetables
- 12.3.7.3 Oilseeds and Pulses
- 12.3.7.4 Horticulture and Ornamental Plants
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application Method - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Soil Application
- 12.4.7.2 Foliar Spray
- 12.4.7.3 Fertigation
- 12.4.7.4 Seed Treatment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Form of Micronutrients - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Chelated Micronutrients
- 12.5.7.2 Non-Chelated Micronutrients
- 12.5.7.3 Liquid Micronutrients
- 12.5.7.4 Powder or Granular Micronutrients
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Type of Micronutrients - Market Size and Forecast
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast
- 12.6.4 Volume Forecast
- 12.6.5 Base-Year Market Share
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Iron
- 12.6.7.2 Zinc
- 12.6.7.3 Manganese
- 12.6.7.4 Copper
- 12.6.7.5 Boron
- 12.6.7.6 Molybdenum
- 12.6.7.7 Chlorine
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Micronutrient End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Japan Micronutrient Geographic Market Outlook
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Japan Micronutrient Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Japan Micronutrient Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Agrium
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Yara International
- 18.4 Sikko Industries Limited
- 18.5 Shoko Agri Co. Ltd
- 18.6 Land O'Lakes Inc
- 18.7 Nufarm
- 18.8 Coromandel International Ltd
- 18.9 Helena Chemical Company
- 18.10 Sapec S.A.
- 18.11 Haifa Chemicals
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

