
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Laparoscopic Devices Market Size 2024 | USD 7690 million |
| Laparoscopic Devices Market, CAGR | 8.7% |
| Laparoscopic Devices Market Size 2032 | USD 15495.42 million |
Market Overview:
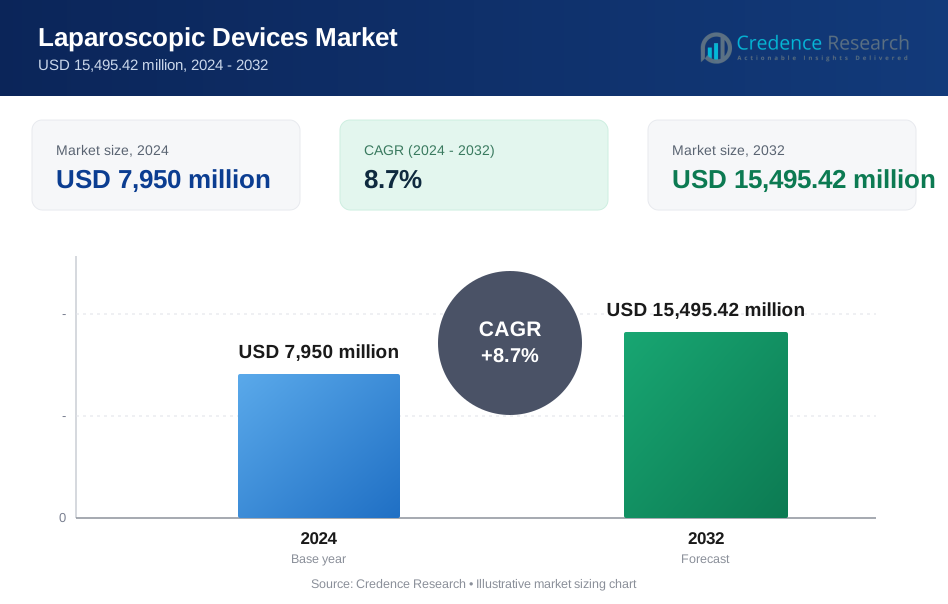
The Global Laparoscopic devices Market size was valued at USD 7950 million in 2024 and is anticipated to reach USD 15495.42 million by 2032, at a CAGR of 8.7% during the forecast period (2024-2032).
Key market drivers include the growing prevalence of obesity, colorectal diseases, and gynecological disorders, which have fueled the demand for laparoscopic procedures. Technological advancements, such as high-definition imaging systems, energy-efficient instruments, and improved suturing devices, are improving surgical outcomes and driving market growth. Moreover, a rising geriatric population, which is more prone to chronic diseases requiring surgical intervention, is boosting the adoption of laparoscopic devices. The increasing focus on cost-effective healthcare solutions, along with government initiatives promoting minimally invasive surgeries, further supports market expansion. However, high device costs and a lack of skilled professionals in developing regions may pose challenges to growth. The growing adoption of disposable laparoscopic instruments to reduce infection risks and cross-contamination is also shaping market trends. Furthermore, the integration of artificial intelligence (AI) and machine learning in surgical robotics is enhancing precision and efficiency in laparoscopic procedures.
Regionally, North America holds the largest share of the laparoscopic devices market due to the strong presence of key market players, advanced healthcare infrastructure, and a high volume of laparoscopic procedures. Europe follows closely, driven by increasing adoption in hospitals and favorable reimbursement policies. The Asia-Pacific region is expected to witness the highest CAGR due to the rising demand for advanced surgical techniques, increasing healthcare expenditure, and a growing patient pool. In contrast, the Middle East, Africa, and Latin America are experiencing gradual growth, primarily driven by improving healthcare facilities and government initiatives promoting laparoscopic procedures. The increasing penetration of international medical device manufacturers in emerging economies is strengthening regional market growth. Additionally, the expansion of telemedicine and remote surgical training programs is improving the accessibility of laparoscopic procedures in underserved regions.
Market Insights:
- The laparoscopic devices market was valued at USD 7,950 million in 2024 and is projected to reach USD 15,495.42 million by 2032, growing at a CAGR of 8.7%.
- Increasing cases of obesity, colorectal diseases, and gynecological disorders are fueling demand for laparoscopic procedures globally.
- Technological advancements, including robotic-assisted surgery, AI integration, and high-definition imaging, are improving surgical precision and efficiency.
- Disposable laparoscopic instruments are gaining traction due to their role in reducing infection risks and cross-contamination.
- North America holds 40% of the market share, followed by Europe at 30%, while Asia-Pacific is expected to witness the highest CAGR.
- Expanding healthcare infrastructure and rising medical tourism in emerging markets are creating new growth opportunities for laparoscopic device manufacturers.
- Government support for minimally invasive surgeries and increasing investments in training programs are accelerating the adoption of laparoscopic technologies.
Market Drivers:
Rising Prevalence of Chronic Diseases and Lifestyle Disorders:
The increasing incidence of chronic diseases such as obesity, colorectal cancer, and gynecological disorders is a significant driver for the laparoscopic devices market. A growing number of patients require minimally invasive surgical procedures to manage these conditions, leading to higher demand for advanced laparoscopic instruments. Obesity-related surgeries, including bariatric procedures, have witnessed substantial growth, particularly in developed regions, due to rising obesity rates and associated health complications. For instance, according to a report by the American College of Cardiology, in the United States, all four major cardiovascular risk factors are predicted to surge from 2025 to 2060, with diabetes expected to rise significantly. Similarly, the growing prevalence of colorectal diseases and endometriosis has driven the adoption of laparoscopic procedures, as they offer reduced recovery time and fewer post-operative complications compared to open surgeries.
Advancements in Laparoscopic Technologies:
Technological innovations in laparoscopic devices are enhancing the precision, efficiency, and safety of minimally invasive procedures. The integration of high-definition imaging systems, 3D visualization, and energy-efficient instruments has improved surgical accuracy and outcomes. Robotic-assisted laparoscopic surgeries are also gaining traction, allowing for greater precision and control, reducing human error, and enabling complex procedures to be performed with minimal invasiveness. For instance, the American Heart Association reports that cardiovascular diseases accounted for a substantial number of deaths worldwide in 2020, highlighting the need for advanced surgical techniques. Additionally, the development of disposable laparoscopic instruments is addressing concerns related to cross-contamination and infection risks, further driving market adoption. The incorporation of artificial intelligence (AI) and machine learning in laparoscopic procedures is another emerging trend, enabling automated assistance for surgeons and improving overall surgical efficiency.
Growing Demand for Minimally Invasive Procedures:
The increasing preference for minimally invasive surgeries is significantly driving the laparoscopic devices market. Patients and healthcare providers favor laparoscopic techniques due to benefits such as reduced hospital stays, faster recovery, minimal scarring, and lower post-operative complications. As healthcare costs rise globally, hospitals and surgical centers are adopting cost-effective solutions like laparoscopic procedures to optimize resource utilization and enhance patient outcomes. For instance, the Aesthetic Society reports that Americans spent a substantial amount on aesthetic procedures overall in 2022, reflecting an increase from the previous year. Furthermore, the growing availability of laparoscopic training programs and simulation-based learning is increasing the number of skilled professionals capable of performing minimally invasive surgeries, further boosting market demand.
Expanding Healthcare Infrastructure in Emerging Markets:
The rapid expansion of healthcare infrastructure, particularly in emerging economies, is fostering market growth. Governments and private healthcare organizations are investing in advanced medical facilities and laparoscopic equipment to enhance surgical capabilities. The Asia-Pacific region, in particular, is witnessing a surge in demand for laparoscopic devices due to increasing healthcare expenditures, rising medical tourism, and improving accessibility to advanced surgical procedures. For instance, India's Ministry of Health and Family Welfare has created the Ayushman Bharat Digital Mission to establish a health ecosystem that digitally connects hospitals, clinics, insurers, doctors, labs, and pharmacies. Additionally, favorable reimbursement policies and initiatives promoting minimally invasive surgeries are encouraging hospitals and surgical centers to adopt laparoscopic technologies. As the global healthcare landscape continues to evolve, the laparoscopic devices market is poised for sustained expansion.
Market Trends:
Integration of Robotic-Assisted Laparoscopic Surgery:
The adoption of robotic-assisted laparoscopic surgery is gaining momentum, enhancing precision, flexibility, and control during procedures. Robotic systems provide surgeons with better visualization, increased dexterity, and reduced hand tremors, leading to improved patient outcomes. The growing acceptance of robotic platforms, such as the da Vinci Surgical System, is driving advancements in minimally invasive procedures. For instance, a study conducted by Johns Hopkins University researchers demonstrated that their Smart Tissue Autonomous Robot (STAR) successfully performed laparoscopic surgery on a pig without human intervention, showcasing the potential for fully automated surgical procedures. As hospitals and surgical centers invest in robotic-assisted technologies, the demand for compatible laparoscopic instruments continues to rise.
Advancements in Imaging and Visualization Technologies:
High-definition (HD) and 3D imaging systems are transforming laparoscopic surgeries by providing clearer, more detailed views of internal organs. For instance, a study using the VISERA ELITE II 3D/HD platform, developed by Olympus, showed improved depth perception and spatial awareness during laparoscopic procedures for hepatocellular carcinoma patients. The integration of fluorescence imaging and augmented reality (AR) in laparoscopic procedures is further improving surgical accuracy. These advancements help surgeons navigate complex anatomical structures with greater confidence, reducing the risk of complications. As imaging technologies evolve, their widespread adoption in minimally invasive surgeries is expected to fuel market growth.
Growing Adoption of Disposable Laparoscopic Instruments:
The increasing focus on infection control and patient safety has led to a rise in the use of disposable laparoscopic instruments. Single-use devices minimize the risk of cross-contamination, ensuring higher standards of sterility in surgical environments. For instance, the Frimley Health NHS Foundation Trust in the UK has reported a significant increase in the adoption of laparoscopic techniques for colorectal cancer procedures. Additionally, disposable instruments reduce costs associated with sterilization and maintenance, making them a preferred choice for healthcare facilities. The demand for cost-effective and efficient laparoscopic tools is driving innovation in this segment.
Expansion of Laparoscopic Procedures in Emerging Markets:
Emerging economies are witnessing a growing demand for laparoscopic surgeries due to rising healthcare investments and increasing awareness of minimally invasive techniques. For instance, in India, the integration of VR and telesurgery technologies is driving the rapid growth of the laparoscopic devices market, as reported by the International Diabetes Federation. Governments and private healthcare providers are enhancing surgical infrastructure, making laparoscopic procedures more accessible. Medical tourism in countries such as India, Thailand, and Brazil is also contributing to market expansion, as international patients seek affordable, high-quality surgical treatments. This trend is expected to drive further adoption of laparoscopic devices globally.
Market Challenges Analysis:
High Cost of Laparoscopic Devices and Procedures:
The high cost associated with laparoscopic devices and robotic-assisted surgical systems remains a significant challenge for market growth. Advanced laparoscopic instruments, including high-definition imaging systems, robotic platforms, and energy-based devices, require substantial investment, making them less accessible to smaller hospitals and surgical centers, particularly in developing regions. Additionally, the maintenance and operational costs of these devices further add to the financial burden on healthcare institutions. Many healthcare providers in cost-sensitive markets struggle to adopt laparoscopic techniques due to budget constraints and limited reimbursement policies, which may hinder market expansion. The financial constraints also affect the adoption rate of newer technologies, slowing market penetration in price-sensitive regions. Furthermore, the high initial investment in robotic-assisted laparoscopic systems restricts their deployment to only well-funded hospitals and specialty clinics. Increasing competition among market players to offer cost-effective solutions and favorable financing options will be critical in addressing this challenge.
Shortage of Skilled Professionals and Technical Limitations:
The effective use of laparoscopic devices requires specialized training and expertise, creating a gap in skilled professionals, especially in emerging economies. The lack of adequately trained surgeons and support staff limits the widespread adoption of minimally invasive procedures. Furthermore, while technological advancements have improved laparoscopic surgeries, certain limitations persist, such as restricted tactile feedback and complex learning curves associated with robotic-assisted systems. In addition, technical issues such as device malfunctions, ergonomic challenges for surgeons, and complications in performing intricate procedures pose further obstacles. The shortage of laparoscopic training centers and simulation programs in developing regions contributes to the limited availability of skilled professionals. Enhancing accessibility to hands-on training, remote learning solutions, and AI-assisted guidance systems can help bridge this skill gap. Moreover, continuous innovation in laparoscopic device design, improving ergonomics, and enhancing haptic feedback in robotic surgery are essential to overcoming these technical challenges.
Market Opportunities:
The laparoscopic devices market presents significant growth opportunities driven by the increasing adoption of minimally invasive surgical techniques across various medical fields. The rising preference for laparoscopic procedures in bariatric, gynecological, urological, and colorectal surgeries is creating strong demand for advanced instruments and robotic-assisted technologies. As patient awareness of the benefits of minimally invasive surgeries-such as reduced post-operative pain, shorter hospital stays, and faster recovery times-continues to grow, healthcare facilities are expanding their laparoscopic capabilities. Additionally, the growing geriatric population, which is more prone to chronic conditions requiring surgical interventions, is further driving the need for efficient and precise laparoscopic solutions. The continuous advancements in imaging technologies, including 3D visualization and fluorescence-guided laparoscopy, are also enhancing procedural accuracy, creating lucrative opportunities for market expansion.
Emerging economies offer substantial potential for market growth due to increasing healthcare investments, improving medical infrastructure, and rising demand for advanced surgical techniques. Governments and private healthcare providers in regions such as Asia-Pacific, Latin America, and the Middle East are actively promoting the adoption of minimally invasive surgeries, leading to a higher demand for laparoscopic devices. Additionally, the expansion of medical tourism in these regions is driving the need for cost-effective, high-quality surgical procedures, further supporting market growth. The integration of artificial intelligence (AI) and machine learning in laparoscopic surgery, enabling real-time decision-making and robotic-assisted precision, is also opening new avenues for innovation. As research and development efforts continue to focus on improving laparoscopic device performance, affordability, and accessibility, the market is poised for long-term expansion.
Market Segmentation Analysis:
By Product
The laparoscopic devices market is segmented based on product types, including laparoscopes, insufflators, energy devices, trocars, closure devices, and robotic-assisted systems. Laparoscopes, including traditional and high-definition variants, hold a significant share due to their essential role in providing visualization during procedures. Robotic-assisted systems are witnessing rapid adoption, driven by advancements in precision and minimally invasive capabilities. The increasing preference for single-use instruments to reduce infection risks is further influencing product demand.
By Application
Laparoscopic devices are widely used in various surgical applications, including bariatric, gynecological, colorectal, urological, and general surgeries. Bariatric surgery accounts for a substantial market share due to the rising prevalence of obesity and associated health conditions. Gynecological and colorectal procedures also contribute significantly to market growth, as laparoscopic techniques offer reduced recovery times and improved patient outcomes. The expanding scope of laparoscopic applications in oncological and hepatobiliary surgeries is further driving segment expansion.
By End-Use
Hospitals, ambulatory surgical centers (ASCs), and specialty clinics represent the primary end-users of laparoscopic devices. Hospitals dominate the segment due to their higher patient volume, availability of advanced surgical infrastructure, and greater adoption of robotic-assisted systems. ASCs are witnessing increasing adoption of laparoscopic procedures, driven by cost efficiency and shorter patient stays. The growing number of specialty clinics focusing on minimally invasive procedures is also contributing to market growth.
Segmentations:
By Product
- Energy Systems
- Trocars
- Suction/ Irrigation Device
- Closure Devices
- Laparoscopes
- Hand Access Instruments
By Application
- Bariatric Surgery
- Urological Surgery
- Gynecological Surgery
- General Surgery
- Others
By End Use
- Clinics
- Hospitals
- Ambulatory Surgical Centers
By Region
- North America
- The US
- Canada
- Mexico
- Europe
- Germany
- France
- The UKUK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a market share of 40%, making it the leading region in the laparoscopic devices market. The strong presence of key market players, advanced healthcare infrastructure, and high adoption rates of minimally invasive surgeries drive market growth. The increasing prevalence of obesity and colorectal diseases has fueled demand for laparoscopic procedures, particularly in the United States. Technological advancements, including robotic-assisted laparoscopic systems, are widely integrated into healthcare facilities, further expanding market potential. Favorable reimbursement policies and increasing investments in research and development contribute to sustained market growth. The rising number of outpatient surgical procedures performed in ambulatory surgical centers is also enhancing the accessibility of laparoscopic techniques. The demand for single-use laparoscopic instruments is also increasing in this region due to stricter infection control regulations.
Europe
Europe accounts for 30% of the laparoscopic devices market, driven by a well-established healthcare system and a growing emphasis on minimally invasive surgical techniques. The region’s increasing adoption of robotic-assisted laparoscopy, particularly in Germany, France, and the United Kingdom, is supporting market expansion. Government initiatives promoting cost-effective surgical solutions and favorable insurance coverage further strengthen market growth. The rising incidence of gynecological and gastrointestinal disorders has led to a higher demand for laparoscopic procedures across hospitals and specialty clinics. Ongoing technological advancements in imaging systems and energy-based instruments are enhancing surgical outcomes, reinforcing the region’s market position. The growing focus on sustainable and reusable laparoscopic instruments is shaping purchasing decisions among healthcare providers in Europe.
Asia-Pacific
Asia-Pacific holds a 20% market share and is expected to register the highest CAGR during the forecast period. The rapid expansion of healthcare infrastructure, increasing medical tourism, and rising healthcare expenditures are driving market growth. Countries such as China, India, and Japan are witnessing a surge in laparoscopic procedures due to a growing patient population and increasing awareness of minimally invasive techniques. Government initiatives aimed at improving surgical accessibility and investments in laparoscopic training programs are further accelerating market expansion. The increasing adoption of robotic-assisted surgeries and disposable laparoscopic instruments is shaping market trends in this region. The rising number of international collaborations between medical device manufacturers and regional healthcare providers is further enhancing market accessibility.
Key Player Analysis:
- Karl Storz SE & CO. Kg
- Medtronic
- Johnson and Johnson
- Olympus Corporation
- CONMED Corporation
- B. Braun Melsungen AG
- The Cooper Companies Inc.
- Richard Wolf GmbH
- Microline Surgical
- BD
- Welfare Medical Ltd
- DEAM
Competitive Analysis:
The laparoscopic devices market is highly competitive, with key players focusing on technological advancements, product innovation, and strategic collaborations to strengthen their market position. Leading companies, including Medtronic, Stryker, Johnson & Johnson, and Karl Storz, dominate the industry with a strong portfolio of advanced laparoscopic instruments and robotic-assisted systems. For instance, Medtronic introduced new AI capabilities with its Touch Surgery Live Stream, featuring 14 advanced algorithms for enhanced post-operative analysis and AI insights in laparoscopic and robotic-assisted surgeries. These players invest significantly in research and development to introduce high-precision devices, energy-efficient instruments, and improved imaging technologies. Emerging companies and regional players are expanding their presence through cost-effective solutions and specialized laparoscopic devices catering to specific surgical needs. Strategic mergers, acquisitions, and partnerships are reshaping the competitive landscape, enabling companies to enhance their product offerings and global reach. Additionally, the growing demand for disposable laparoscopic instruments and AI-integrated robotic systems is intensifying competition, driving innovation and market expansion.
Recent Developments:
- In May 2024, Medtronic launched an advanced 4K imaging system for laparoscopic procedures, enhancing visualization and precision during minimally invasive surgeries.
- In May 2024, B. Braun Melsungen AG opened a new factory in Switzerland to expand production capabilities for advanced medical devices, including laparoscopic instruments.
- In November 2023, The Cooper Companies Inc. acquired select Cook Medical assets for $300 million, primarily focused on obstetrics, doppler monitoring, and gynecology surgery markets, strengthening Cooper Surgical's position in minimally invasive medical devices.
- In November 2023, Microline Surgical acquired the rights to certain laparoscopic instrumentation assets from RETRACTION Limited, including the REVEEL branded products used for liver retraction in laparoscopic surgeries.
Market Concentration & Characteristics:
The laparoscopic devices market is moderately concentrated, with a mix of global leaders and emerging players competing to enhance technological advancements and market share. Established companies such as Medtronic, Stryker, and Johnson & Johnson dominate the industry, leveraging strong distribution networks, extensive research and development, and innovative product portfolios. The market is characterized by rapid technological evolution, with increasing adoption of robotic-assisted laparoscopic systems, high-definition imaging solutions, and energy-efficient instruments. Growing demand for minimally invasive procedures, coupled with the shift toward disposable and single-use laparoscopic instruments, is influencing product development strategies. Competitive pricing, regulatory compliance, and intellectual property protection play crucial roles in market dynamics. Additionally, regional manufacturers are gaining traction by offering cost-effective solutions and expanding their presence in emerging economies. Continuous advancements in artificial intelligence and automation are further shaping the market, enhancing precision, efficiency, and overall surgical outcomes.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The increasing adoption of robotic-assisted laparoscopic surgery will enhance precision, reduce complications, and improve patient outcomes.
- Advancements in imaging technologies, including 3D visualization and fluorescence-guided laparoscopy, will drive the demand for high-definition laparoscopic systems.
- The rising preference for minimally invasive procedures will continue to fuel the demand for advanced laparoscopic instruments across multiple surgical applications.
- The integration of artificial intelligence (AI) and machine learning in laparoscopic devices will enhance real-time decision-making and surgical accuracy.
- The growing adoption of disposable laparoscopic instruments will strengthen infection control measures and reduce cross-contamination risks in healthcare settings.
- Increasing healthcare investments in emerging economies will expand market opportunities and improve accessibility to laparoscopic procedures.
- Strategic mergers, acquisitions, and collaborations among key market players will drive innovation and accelerate the development of next-generation laparoscopic technologies.
- The expansion of outpatient surgical centers and ambulatory care facilities will boost the demand for cost-effective and efficient laparoscopic devices.
- Government initiatives supporting minimally invasive surgeries and favorable reimbursement policies will encourage greater adoption of laparoscopic techniques.
- Continuous research and development in energy-based laparoscopic devices will improve procedural efficiency, reduce operating time, and enhance overall surgical performance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases and Lifestyle Disorders
Increasing rates of obesity, colorectal cancer, and gynecological disorders are driving demand for minimally invasive laparoscopic procedures, as these conditions often require surgical intervention that benefits from reduced recovery times and fewer complications.
Technological Advancements in Laparoscopic Devices
Innovations such as high-definition imaging, robotic-assisted systems, and AI integration are improving surgical precision, efficiency, and safety, making laparoscopic procedures more attractive to both surgeons and patients.
Growing Demand for Minimally Invasive Procedures
Patients and healthcare providers are increasingly favoring laparoscopic techniques due to benefits like shorter hospital stays, minimal scarring, and lower post-operative risks, which is accelerating the adoption of advanced laparoscopic devices.
Expansion of Healthcare Infrastructure in Emerging Markets
Rapid investments in healthcare facilities, particularly in Asia-Pacific and other emerging regions, are increasing access to advanced surgical technologies and driving the uptake of laparoscopic devices.
Government Initiatives and Favorable Reimbursement Policies
Supportive government policies and improved insurance coverage for minimally invasive surgeries are encouraging hospitals and surgical centers to invest in laparoscopic technologies, further boosting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of laparoscopic devices in 2024, and what is the expected growth by 2032?
What are the key factors driving the growth of the laparoscopic devices market?
What challenges does the laparoscopic devices market face?
How is technology influencing the laparoscopic devices market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Clinics
- 1.3 By Product
- 1.3.1 Energy Systems
- 1.3.2 Trocars
- 1.3.3 Suction/Irrigation Device
- 1.3.4 Closure Devices
- 1.3.5 Laparoscopes
- 1.3.6 Hand Access Instruments
- 1.4 By Application
- 1.4.1 Bariatric Surgery
- 1.4.2 Urological Surgery
- 1.4.3 Gynecological Surgery
- 1.4.4 General Surgery
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,950 million → 2032: USD 15,495.42 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laparoscopic Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laparoscopic Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laparoscopic Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laparoscopic Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laparoscopic Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laparoscopic Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laparoscopic Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laparoscopic Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,950 million → 2032: USD 15,495.42 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laparoscopic Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Clinics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Energy Systems
- 12.4.7.2 Trocars
- 12.4.7.3 Suction/Irrigation Device
- 12.4.7.4 Closure Devices
- 12.4.7.5 Laparoscopes
- 12.4.7.6 Hand Access Instruments
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Bariatric Surgery
- 12.5.7.2 Urological Surgery
- 12.5.7.3 Gynecological Surgery
- 12.5.7.4 General Surgery
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laparoscopic Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Laparoscopic Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Laparoscopic Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Laparoscopic Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Johnson & Johnson
- 18.4 Olympus Corporation
- 18.5 Karl Storz SE & Co. KG
- 18.6 CONMED Corporation
- 18.7 B. Braun Melsungen AG
- 18.8 The Cooper Companies Inc.
- 18.9 Richard Wolf GmbH
- 18.10 Microline Surgical
- 18.11 BD
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

