
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Marine Fin Stabilizers Market Size 2024 | USD 5879 million |
| Marine Fin Stabilizers Market, CAGR | 12.63% |
| Marine Fin Stabilizers Market Size 2032 | USD 15224.2 million |
Market Overview:
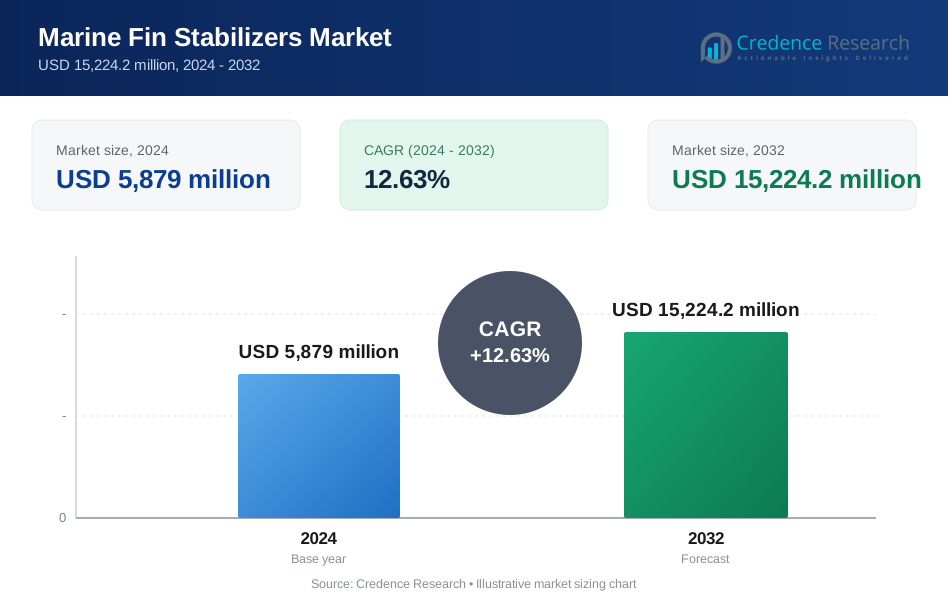
Marine Fin Stabilizers Market size was valued at USD 5879 million in 2024 and is anticipated to reach USD 15224.2 million by 2032, at a CAGR of 12.63% during the forecast period (2024-2032).
Market growth is primarily driven by the rising need for enhanced vessel stability and improved passenger comfort, particularly within the cruise, luxury yacht, and defense sectors. The surge in global maritime tourism, coupled with steady growth in seaborne trade, has heightened the importance of reliable stabilization systems. Additionally, stricter environmental regulations and the pursuit of greater fuel efficiency are encouraging the adoption of innovative, energy-saving stabilizer technologies. Recent advancements, such as retractable and zero-speed fin stabilizers, along with the integration of smart monitoring and control systems, are further supporting market expansion by improving operational performance and efficiency. The increasing focus on safety standards and regulatory compliance is also prompting vessel operators to upgrade and retrofit their fleets with advanced stabilizer solutions.
Regionally, the Asia-Pacific market leads in terms of both size and growth rate, propelled by the dominance of major shipbuilding nations like China, South Korea, and Japan. This region benefits from substantial investments in maritime infrastructure and fleet expansion. Europe and North America also represent significant markets, supported by established shipbuilding industries and strong demand for luxury and passenger vessels. Meanwhile, emerging regions such as the Middle East and Latin America are witnessing increased adoption of marine fin stabilizers due to expanding maritime tourism and offshore activities. The entry of new regional players and collaborative ventures with global technology providers are further accelerating market development in these areas. Overall, Asia-Pacific is expected to maintain its leading position, driven by ongoing economic growth and continued focus on maritime sector development.
Market Insights:
- The Marine Fin Stabilizers Market was valued at USD 5,879 million in 2024 and is projected to reach USD 15,224.2 million by 2032, reflecting strong growth prospects.
- Rising demand for vessel stability and passenger comfort in cruise, luxury yacht, and defense sectors drives market expansion.
- Global maritime tourism and seaborne trade growth increase the need for advanced and reliable stabilization systems.
- Stricter environmental regulations and the push for fuel efficiency encourage adoption of innovative, energy-saving stabilizer technologies.
- Technological advancements, such as retractable and zero-speed stabilizers with smart monitoring, enhance operational performance and efficiency.
- High initial costs, complex installation, and maintenance demands remain key challenges, especially for smaller operators and older fleets.
- Asia-Pacific leads the market with 44% share, driven by major shipbuilding nations, while Europe and North America also contribute significantly due to strong demand and established maritime industries.
Market Drivers:
Rising Demand for Enhanced Vessel Stability and Passenger Comfort
The Marine Fin Stabilizers Market benefits from the growing emphasis on vessel stability and passenger comfort, especially in cruise ships, luxury yachts, and naval vessels. Ship operators prioritize smooth sailing experiences to attract and retain customers. Passengers expect minimal rolling and pitching, which directly impacts satisfaction and safety. The market responds to these expectations by delivering advanced stabilizer systems that reduce motion and improve onboard comfort. Shipbuilders incorporate these technologies into new builds and retrofits to meet evolving customer requirements. It positions the market as a critical component in ensuring superior maritime experiences.
- For instance, Poseidon Expeditions’ 114-passenger Sea Spirit was retrofitted with Rolls Royce Zero Speed Stabilizers in 2019, enabling safe navigation through polar waters and reducing ship roll even when anchored or drifting.
Expansion of Maritime Tourism and Seaborne Trade Drives Adoption
Global maritime tourism and seaborne trade show steady growth, fueling the need for reliable stabilization solutions. The Marine Fin Stabilizers Market sees increased demand from commercial shipping, passenger ferries, and tourism vessels. Operators seek to minimize motion sickness and cargo shifting, which can cause operational delays and financial losses. The market addresses these challenges by offering efficient and customizable stabilizer products. Growth in international cruise tourism and luxury travel further amplifies the need for advanced stabilization technologies. It strengthens the market’s role in supporting the expanding maritime economy.
Regulatory Pressure and Environmental Compliance Accelerate Innovation
Stringent regulations on emissions and vessel safety push the Marine Fin Stabilizers Market toward innovation. Regulatory bodies enforce standards that require energy-efficient and environmentally friendly equipment. Shipowners respond by investing in advanced stabilizer systems that improve fuel efficiency and reduce environmental impact. The market develops solutions that help operators comply with international maritime regulations. It encourages the adoption of technologies that align with global sustainability goals. Compliance requirements drive continuous improvement and technological advancement in the market.
Technological Advancements and Integration of Smart Systems Enhance Value
The Marine Fin Stabilizers Market experiences rapid technological progress, including the development of retractable and zero-speed stabilizers. Manufacturers integrate smart monitoring and control systems, enabling real-time performance optimization. These innovations increase operational efficiency and reduce maintenance costs for shipowners. The market offers products that adapt to various vessel types and operational conditions. Enhanced automation and connectivity appeal to operators seeking modern, future-ready solutions. It positions the market at the forefront of maritime technology adoption.
- For instance, Quantum’s DYNA-FOIL™ system delivers a stabilizing moment at Zero Speed™ up to 150 kNm greater than standard fixed fins of the same size, as documented in Quantum’s technical specifications.
Market Trends:
Growing Adoption of Advanced and Zero-Speed Stabilizer Technologies
The Marine Fin Stabilizers Market witnesses a clear shift toward advanced and zero-speed stabilizer technologies. Shipowners and operators increasingly select systems that offer performance both underway and at anchor, reflecting the need for consistent comfort. It responds to this demand by expanding product portfolios with retractable, non-retractable, and zero-speed solutions. Manufacturers focus on compact designs and lightweight materials to support fuel efficiency and vessel versatility. The market also sees a rise in retrofitting activities, as older vessels require upgrades to meet modern standards. Shipyards and fleet operators value these technologies for their ability to enhance both safety and passenger experience. It positions advanced stabilizer solutions as a key differentiator in vessel design and operation.
- For instance, Quantum Marine Stabilizers’ F45 Hybrid Power System was installed on a 47-meter Feadship yacht in March 2024, where it demonstrated standby power consumption of less than 1 kW—a substantial reduction compared to traditional systems.
Integration of Smart Systems and Focus on Sustainability
Digitalization and sustainability emerge as defining trends in the Marine Fin Stabilizers Market. Operators seek stabilizer systems equipped with smart monitoring, predictive maintenance, and remote diagnostics capabilities. It drives manufacturers to develop products that integrate seamlessly with vessel management systems, improving operational efficiency and reducing downtime. The market also responds to regulatory and customer pressure for environmentally responsible solutions by prioritizing energy-efficient designs and recyclable materials. Shipbuilders and owners recognize the long-term value of systems that lower emissions and operating costs. It underscores the market’s commitment to innovation and environmental stewardship, shaping the direction of future product development.
- For instance, Quantum Marine Stabilizers’ e-FIN system features a purpose-built gearbox capable of handling up to 10 million cycles, underscoring its reliability and advanced engineering.
Market Challenges Analysis:
High Initial Costs and Complex Installation Processes
The Marine Fin Stabilizers Market faces significant challenges due to high initial investment requirements and complex installation processes. Many shipowners hesitate to adopt advanced stabilizer systems because of the substantial upfront costs involved in both equipment and integration. It often requires specialized expertise and extended downtime, which disrupts vessel operations and increases overall expenses. Smaller operators and older fleets find these barriers particularly difficult to overcome. The market must address these concerns by offering cost-effective solutions and streamlined installation services. It remains a critical hurdle for broader market penetration, especially in price-sensitive segments.
Maintenance Demands and Technological Compatibility Issues
Ongoing maintenance and compatibility with existing vessel systems present persistent challenges for the Marine Fin Stabilizers Market. Stabilizers require regular inspection and servicing to maintain optimal performance, which can lead to increased operational costs and logistical complexities. It can be difficult to integrate new stabilizer technologies with legacy onboard systems, causing delays and technical setbacks. Shipowners often struggle to find skilled technicians and reliable spare parts, especially for older models. The market must focus on enhancing product reliability and simplifying maintenance procedures. It needs to ensure seamless compatibility to support long-term adoption and customer satisfaction.
Market Opportunities:
Expansion into Emerging Markets and Retrofit Opportunities
The Marine Fin Stabilizers Market sees strong potential for growth in emerging markets, where investments in maritime infrastructure and fleet modernization continue to rise. Shipowners in regions such as Asia-Pacific, the Middle East, and Latin America increasingly seek advanced stabilization systems to enhance vessel safety and passenger comfort. It can capitalize on this trend by offering tailored solutions that address the specific needs of these markets. The growing demand for retrofitting older vessels with modern stabilizers creates a significant opportunity for manufacturers and service providers. Shipyards and operators recognize the value of upgrading existing fleets to meet evolving industry standards. It positions the market for sustained expansion as new and retrofit projects accelerate globally.
Innovation in Green Technologies and Smart Systems
The Marine Fin Stabilizers Market can leverage opportunities presented by the industry’s focus on sustainability and digitalization. Shipowners and operators prioritize energy-efficient and environmentally friendly stabilizer solutions to comply with tightening regulations and reduce operational costs. It can drive growth by developing products that incorporate smart monitoring, predictive maintenance, and seamless integration with digital vessel management systems. Manufacturers who invest in research and development of green technologies will gain a competitive edge. The market stands to benefit from partnerships and collaborations that foster innovation and technological advancement. It aligns with the broader maritime industry’s shift toward smarter, cleaner, and more efficient operations.
Market Segmentation Analysis:
By Product Type:
The Marine Fin Stabilizers Market segments by product type into retractable and non-retractable stabilizers. Retractable stabilizers lead the market due to their versatility and ability to improve hydrodynamic efficiency when not in use. Non-retractable stabilizers appeal to operators seeking robust, cost-effective solutions for continuous stabilization. It sees growing demand for zero-speed stabilizers, which enhance comfort at anchor and attract luxury yacht and cruise ship owners.
- For instance, the first Dyna-Foil™ system was installed on a 70m Benetti refit, enabling large vessels to achieve optimal roll reduction at all speeds without compromising hull design.
By Application:
This market divides by application into commercial, naval, and recreational vessels. Commercial vessels represent the largest share, driven by the need for cargo safety and operational efficiency. Naval vessels show strong demand for advanced stabilization to support mission-critical operations and crew safety. It also notes a surge in adoption within recreational vessels, where passenger comfort and premium onboard experiences are top priorities.
- For instance, the first of four such Navy craft delivered by Modutech Marine, Inc. is equipped with exactly three Seakeeper M26000 gyros.
By End-User:
The Marine Fin Stabilizers Market classifies end-users as shipbuilders, fleet operators, and retrofit service providers. Shipbuilders integrate advanced stabilizer systems into new builds to meet customer specifications and regulatory standards. Fleet operators prioritize retrofitting existing vessels to enhance performance and comply with evolving safety requirements. It highlights growing collaboration between manufacturers and service providers to deliver tailored solutions for diverse end-user needs.
Segmentations:
- By Product Type:
- Retractable Fin Stabilizers
- Non-Retractable Fin Stabilizers
- Zero-Speed Fin Stabilizers
- By Application:
- Fishing Vessels
- Passenger Vessels
- Naval and Coast Guard Vessels
- Merchant Vessels
- By End-User:
- Shipbuilders
- Fleet Operators
- Retrofit Service Providers
- Marine Research Institutions
- Government and Military Organizations
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
Asia-Pacific Leads with Shipbuilding Strength and Infrastructure Investments
Asia-Pacific holds 44% of the global Marine Fin Stabilizers Market, making it the dominant regional segment. China, South Korea, and Japan drive this leadership through their robust shipbuilding industries and significant investments in maritime infrastructure. The region’s focus on expanding fleets and upgrading vessel capabilities to meet international standards sustains strong demand for advanced stabilizer technologies. Rapid economic growth and rising disposable incomes support the expansion of cruise tourism and luxury yacht segments, further fueling market growth. Governments prioritize modernization of ports and maritime logistics, which boosts adoption of innovative marine equipment. The market expects Asia-Pacific to maintain its leading position through continued investment and technological advancement.
Europe Maintains Market Share with Innovation and Luxury Vessel Demand
Europe accounts for 28% of the Marine Fin Stabilizers Market, supported by its established shipbuilding sector and high demand for luxury vessels. Countries such as Germany, Italy, and the Netherlands serve as key hubs for the production of cruise ships, superyachts, and passenger ferries. The region thrives on a reputation for technological innovation and stringent regulatory standards, which drive adoption of energy-efficient and environmentally friendly stabilizer systems. The presence of leading manufacturers and a strong focus on research and development sustain Europe’s competitive edge. Growth in maritime tourism and increasing investments in fleet modernization further strengthen the market. Europe remains a critical region for both product innovation and premium vessel applications.
North America and Emerging Regions Show Steady Growth Potential
North America holds 19% of the Marine Fin Stabilizers Market, with the United States leading regional demand for advanced stabilization systems in both commercial and recreational vessels. The region benefits from a mature maritime industry and a focus on safety and operational efficiency. Investments in naval modernization and a strong market for cruise ships and yachts support steady growth. Emerging regions such as the Middle East and Latin America present new opportunities, driven by expanding maritime tourism and offshore energy projects. These markets attract attention from global manufacturers seeking to diversify and capture untapped potential. North America and emerging regions are positioned as important contributors to the market’s long-term expansion.
Key Player Analysis:
- ABT-TRAC
- Fincantieri S.p.A.
- Quantum Marine Stabilizers
- Naiad Dynamics
- Kongsberg Gruppen
- Wesmar Marine Electronics
- Twin Disc, Inc.
- Rolls-Royce Holdings plc SKF Group
- CMC Marine
- Humphree AB
- Mitsubishi Heavy Industries Marine Machinery & Equipment Co., Ltd.
Competitive Analysis:
The Marine Fin Stabilizers Market features a competitive landscape with several global and regional players vying for market share. Leading companies focus on technological innovation, product reliability, and customer support to strengthen their positions. It sees established firms investing in research and development to introduce advanced stabilizer systems with smart monitoring and energy-efficient features. New entrants target niche segments by offering customized solutions and competitive pricing. Strategic partnerships and collaborations help companies expand their geographic reach and service capabilities. The market values strong after-sales support and technical expertise, which influence customer loyalty and repeat business. It remains dynamic, with ongoing advancements and evolving customer needs shaping the competitive environment.
Recent Developments:
- In May 2025, SKF announced a partnership with Carnegie Clean Energy Limited to deliver wave energy technology solutions.
- In April 2025, ABT-TRAC introduced the 370 Rear Mount Dual Conversion Kit, designed as an upgrade for existing 370 Stabilizer Systems, aiming to reduce downtime and enhance vessel performance.
- In October 2024, Quantum Marine Stabilizers launched the e-FIN electric stabilizer at the Monaco Yacht Show.
Market Concentration & Characteristics:
The Marine Fin Stabilizers Market displays a moderate to high level of concentration, with a few major players holding significant market shares alongside several specialized regional manufacturers. It features strong barriers to entry due to high capital requirements, advanced technological expertise, and strict regulatory standards. Leading companies differentiate themselves through innovation, product customization, and comprehensive after-sales service. The market values reliability, efficiency, and adaptability to various vessel types. It responds quickly to evolving customer demands and regulatory changes, driving continuous product development. The presence of both global leaders and agile local firms ensures a competitive yet stable market environment.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for marine fin stabilizers will increase as the maritime tourism and global cruise sectors expand.
- The market will witness broader adoption of zero-speed and hybrid stabilizer systems, especially in luxury yachts and vessels that require comfort at anchor.
- Shipowners will focus on retrofitting older vessels with advanced stabilizer technologies to enhance operational efficiency and passenger safety.
- Technological advancements such as smart sensors, automated control systems, and predictive maintenance will influence new product development.
- Sustainability will remain a priority, with manufacturers introducing energy-efficient and environmentally responsible stabilizer solutions.
- The Asia-Pacific region will lead growth, supported by investments in shipbuilding, maritime infrastructure, and rising disposable incomes.
- Commercial shipping and cargo vessels will increase their use of fin stabilizers to reduce cargo loss and ensure stable operations in challenging sea conditions.
- Stricter safety and environmental regulations will drive the adoption of advanced stabilizer systems across various vessel categories.
- Integration of fin stabilizers with vessel management and automation platforms will become a standard industry practice.
- Competition will intensify, with established firms investing in innovation and new entrants pursuing niche applications and emerging regional markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Marine Fin Stabilizers Market?
What are the key segments within the Marine Fin Stabilizers Market?
What are some challenges faced by the Marine Fin Stabilizers Market?
Who are the major players in the Marine Fin Stabilizers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Marine Fin Stabilizers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Marine Fin Stabilizers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,879 million → 2032: USD 15,224.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Marine Fin Stabilizers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Marine Fin Stabilizers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Marine Fin Stabilizers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Marine Fin Stabilizers Market Drivers
- 3.3 Marine Fin Stabilizers Market Restraints & Challenges
- 3.4 Marine Fin Stabilizers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Marine Fin Stabilizers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Marine Fin Stabilizers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Marine Fin Stabilizers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Marine Fin Stabilizers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Marine Fin Stabilizers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Marine Fin Stabilizers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Marine Fin Stabilizers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Marine Fin Stabilizers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Marine Fin Stabilizers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Marine Fin Stabilizers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Marine Fin Stabilizers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Marine Fin Stabilizers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Marine Fin Stabilizers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Marine Fin Stabilizers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Marine Fin Stabilizers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Marine Fin Stabilizers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Marine Fin Stabilizers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Marine Fin Stabilizers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Marine Fin Stabilizers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
