
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
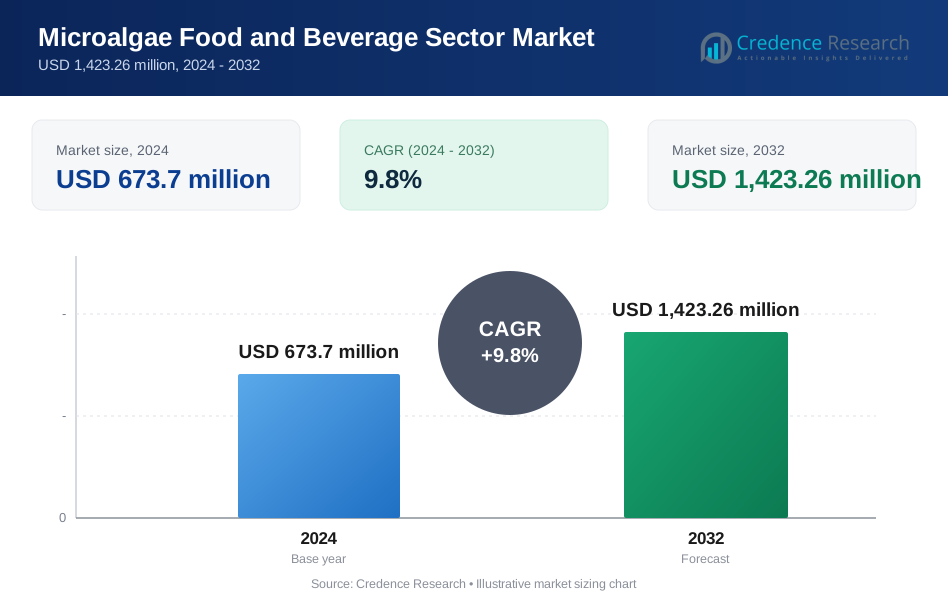
| Microalgae Food and Beverage Sector Market Size 2024 | USD 673.7 million |
| Microalgae Food and Beverage Sector Market, CAGR | 9.8% |
| Microalgae Food and Beverage Sector Market Size 2032 | USD 1423.26 million |
Market Overview:
The global Microalgae Food and Beverage Sector Market is projected to grow from USD 673.7 million in 2024 to an estimated USD 1423.26 million by 2032, with a compound annual growth rate (CAGR) of 9.8% from 2024 to 2032.
Key market drivers include the growing trend toward sustainable and eco-friendly food production, coupled with heightened demand for natural, nutrient-dense alternatives in food and beverages. Microalgae's versatility, including its application in protein powders, non-dairy beverages, snacks, and dietary supplements, has positioned it as an attractive solution for consumers seeking healthier options. Additionally, the global shift toward plant-based diets, driven by environmental and ethical concerns, has bolstered the adoption of microalgae-derived products. Technological advancements in cultivation and processing methods have also lowered production costs and enhanced product quality, further fueling market expansion.
Regionally, North America dominates the market due to widespread consumer awareness and robust investments in food innovation and sustainability. Europe follows closely, supported by stringent regulations promoting clean-label products and plant-based consumption. The Asia-Pacific region is witnessing rapid growth, driven by increasing health consciousness and demand for innovative food products in countries like China, Japan, and India. Furthermore, favorable government policies and growing interest in alternative protein sources have accelerated market penetration in emerging economies.
Market Drivers:
Growing Demand for Plant-Based Nutrition:
The global shift toward plant-based diets is a significant driver of the microalgae food and beverage market. Increasing consumer awareness of the health benefits associated with plant-based nutrition has boosted the demand for microalgae-derived products. These products are rich in essential nutrients such as proteins, omega-3 fatty acids, vitamins, and minerals, making them ideal for health-conscious consumers. For instance, microalgae like spirulina contain up to 70% protein by dry weight, which is higher than most plant-based sources. Additionally, the growing prevalence of food allergies and intolerances has fueled the adoption of microalgae as a sustainable and allergen-free alternative to conventional ingredients.
Sustainability and Environmental Concerns:
Microalgae production aligns with global efforts to address environmental challenges, including reducing greenhouse gas emissions and preserving natural resources. Microalgae cultivation requires significantly less water, land, and energy compared to traditional agriculture, making it a sustainable solution for the food and beverage industry. As consumers and corporations increasingly prioritize eco-friendly practices, the demand for microalgae-based products is expected to rise. The alignment of microalgae production with circular economy principles further strengthens its appeal in the global market. For example, the European Union's Horizon 2020 program has invested over €20 million in projects aimed at integrating microalgae cultivation into circular economy models.
Rising Interest in Functional Foods:
The expanding functional food and beverage segment has been a key growth driver for the microalgae market. Consumers are seeking products that not only meet dietary needs but also offer additional health benefits, such as improved immunity, cardiovascular health, and enhanced energy levels. Microalgae's bioactive compounds, including antioxidants and essential fatty acids, position it as an ideal ingredient for functional products, further driving its adoption across various food and beverage applications. For instance, astaxanthin, a powerful antioxidant found in microalgae, has been shown to support eye health and reduce inflammation.
Technological Advancements and Cost Efficiency:
Recent advancements in cultivation and processing technologies have significantly reduced production costs and improved the quality of microalgae-based ingredients. Innovations in strain development and bioprocessing techniques have enabled manufacturers to optimize yields and tailor products to specific consumer preferences. For example, advances in photobioreactor technology have increased the efficiency of microalgae cultivation, reducing costs by up to 50%. These developments have enhanced the scalability and accessibility of microalgae products, making them a competitive choice for mainstream food and beverage applications.
Market Trends:
Increased Demand for Nutrient-Rich and Functional Foods:
The microalgae food and beverage sector is experiencing a surge in demand driven by consumer preference for natural and nutrient-rich ingredients. Microalgae, celebrated for its dense nutritional profile, is increasingly being incorporated into everyday products such as snacks, smoothies, and non-dairy alternatives. For instance, spirulina, a type of microalgae, contains up to 60-70% protein by dry weight, which is higher than most plant-based sources. This trend reflects the growing awareness of the health benefits of plant-based foods, particularly among millennials and Gen Z consumers, who are driving the demand for innovative and functional food options.
Focus on Sustainability and Environmental Responsibility:
Sustainability remains at the forefront of industry trends, with microalgae emerging as a solution to environmental challenges. Its cultivation process, requiring minimal water, land, and energy, aligns with the global emphasis on reducing carbon footprints and promoting eco-friendly practices. For example, microalgae production requires up to 10 times less water than traditional agriculture, according to a study published in the Journal of Cleaner Production. As governments and organizations advocate for sustainable food systems, companies are integrating microalgae into their portfolios to meet regulatory standards and consumer expectations for environmentally responsible products.
Personalized Nutrition and Targeted Health Benefits:
The rise of personalized nutrition is further influencing the microalgae market. Advances in food science and technology have enabled manufacturers to tailor microalgae-based products to address specific health needs, such as immune support, heart health, or cognitive enhancement. As consumers increasingly seek functional foods that align with their unique dietary requirements, microalgae’s versatility and bioactive properties position it as a cornerstone ingredient in personalized nutrition solutions. For instance, the bioactive compound astaxanthin, found in microalgae, has been shown to support eye health and reduce inflammation.
Technological Innovation Driving Product Development:
Technological innovation is shaping the future of the microalgae sector. Breakthroughs in bioprocessing and cultivation methods have enhanced the scalability and cost-efficiency of microalgae production. For example, SunOleo, a French company, has developed an innovative photobioreactor that allows for large-scale microalgae cultivation in a controlled environment. These advancements have enabled producers to develop high-quality, flavor-neutral microalgae extracts, making them suitable for a broader range of food and beverage applications. As a result, microalgae is transitioning from niche health products to mainstream adoption, solidifying its role in the evolution of the global food industry.
Market Challenges Analysis:
High Production Costs:
The microalgae food and beverage sector face a significant obstacle in the high production costs associated with cultivating and processing microalgae. Advanced technologies, specialized facilities, and controlled environments are often required to ensure consistent quality and yield, making microalgae-derived products more expensive than conventional food ingredients. This cost barrier limits affordability for consumers and hinders widespread adoption, particularly in price-sensitive markets.
Technical Challenges in Product Development:
Integrating microalgae into diverse food and beverage formulations poses technical challenges. While microalgae is nutritionally rich, its distinct flavor and color can be difficult to mask, especially when targeting mainstream consumers. Overcoming these sensory barriers often requires additional processing or blending, which increases production costs and complicates manufacturing processes.
Regulatory and Compliance Hurdles:
Regulatory challenges represent a critical barrier for the microalgae market. Variations in food safety standards and approval processes across regions can delay product launches and increase compliance costs for manufacturers. Moreover, a lack of harmonized regulations regarding microalgae classification and labeling can create confusion and restrict market expansion, particularly for emerging players entering global markets.
Limited Consumer Awareness and Misconceptions:
Consumer awareness and education remain a significant challenge for the microalgae sector. While microalgae is gaining recognition as a superfood, many consumers are still unaware of its benefits and applications. Misconceptions regarding its taste, sourcing, and environmental impact may further deter potential customers. Addressing these gaps through targeted marketing campaigns, transparent communication of nutritional advantages, and clear sourcing practices is crucial for driving consumer acceptance and market growth.
Market Segmentation Analysis:
By Species Type
The microalgae food and beverage market are segmented by species type, with spirulina and chlorella being the most prominent. Spirulina is widely used due to its high protein content, antioxidants, and vitamins, making it a preferred choice for functional food and beverage products. Chlorella, known for its detoxifying properties and high chlorophyll content, is gaining traction in health supplements and specialty beverages. Other species, such as Dunaliella and Haematococcus, are also witnessing growth due to their specific bioactive compounds like beta-carotene and astaxanthin, which cater to niche health applications.
By Source
Based on the source, microalgae are classified into freshwater and marine varieties. Freshwater microalgae dominate the market due to their established cultivation processes and broad application in food and beverages. Marine microalgae are emerging as a lucrative segment, offering unique bioactive compounds such as omega-3 fatty acids, which are increasingly incorporated into fortified foods and functional drinks.
By End-Use Application
Microalgae find applications across a range of food and beverage categories, including dietary supplements, non-dairy beverages, snacks, and baked goods. Dietary supplements lead the market, driven by increasing health consciousness and demand for nutrient-dense products. Non-dairy beverages and snacks are also gaining momentum, as consumers seek plant-based and sustainable alternatives. Additionally, microalgae's functional properties are paving the way for its inclusion in innovative applications such as protein powders and energy bars, further diversifying its end-use portfolio.
Segmentation:
By Species Type
- Spirulina
- Chlorella
- Dunaliella
- Haematococcus
By Source
- Freshwater
- Marine
By End-Use Application
- Dietary Supplements
- Non-Dairy Beverages
- Snacks
- Baked Goods
- Protein Powders
- Energy Bars
By Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
The North America region dominates the microalgae food and beverage sector, holding the largest market share of approximately 35% in 2024. This leadership is driven by strong consumer awareness of health and wellness, alongside increasing demand for plant-based and functional food products. The United States and Canada lead in market penetration due to robust investments in research and development, as well as established supply chains. The region's focus on sustainable food practices and government support for alternative protein sources further fuel growth.
Europe:
Europe follows closely, accounting for a market share of around 30%. The region's emphasis on clean-label products, stringent regulations promoting sustainability, and growing consumer inclination toward eco-friendly and nutritious alternatives bolster the adoption of microalgae. Countries such as Germany, France, and the Netherlands are key contributors, with ongoing innovations in food technology and strong consumer interest in health-focused products. The rising popularity of plant-based diets and the region's advanced infrastructure for sustainable farming further enhance market expansion.
Asia-Pacific:
The Asia-Pacific region is the fastest-growing market, with a share of approximately 25%. The region's rapid economic growth, increasing health consciousness, and expanding middle-class population drive demand for nutrient-rich food and beverages. Countries like China, Japan, and India are emerging as major markets due to growing awareness of the health benefits of microalgae and rising investments in aquaculture and bio-innovation. Additionally, favorable government policies supporting sustainable food production contribute to market growth.
Latin America:
Latin America holds a smaller market share of about 6%, but the region is showing promising growth. Brazil and Mexico are key markets, with increasing adoption of microalgae-based products in functional foods and beverages. The region's rich biodiversity and favorable climatic conditions for algae cultivation provide significant potential for expansion.
Middle East & Africa:
The Middle East & Africa accounts for the remaining 4% of the market share, with growth driven by rising awareness of alternative protein sources and efforts to address food security challenges. Countries like South Africa and the UAE are witnessing gradual adoption of microalgae, supported by initiatives to promote sustainable food practices and reduce reliance on traditional agriculture.
Key Player Analysis:
- DIC Corporation
- Koninklijke DSM NV
- Roquette Frères
- Fuji Chemical Industries Co., Ltd.
- Yunnan Green-A-Bio-engineering Co Ltd
- Cyanotech Corporation
- BASF SE
- Parry Nutraceuticals
- Beijing Gingko Group
- KDI Ingredients
- Sinoway Industrial Co., ltd.
- INNOBIO Corporation Limited
- Algaecan Biotech Ltd.
- Algatechnologies Ltd.
- Cardax, Inc.
- Igene Biotechnology, Inc.
- Fenchem Biotek Ltd.
- AstaReal Inc.
- Valensa International
- Kunming Biogenic Co., Ltd.
Competitive Analysis:
The microalgae food and beverage market are characterized by intense competition, with a mix of established players and emerging startups driving innovation. Key market participants such as Corbion, Cyanotech Corporation, DIC Corporation, and Euglena Co., Ltd. dominate through diversified product portfolios, robust R&D capabilities, and global distribution networks. These companies leverage advanced technologies to enhance the nutritional value, scalability, and sensory attributes of microalgae-based products, ensuring competitiveness. Emerging players, including Alver and Algama Foods, are focusing on niche applications and sustainable production methods to differentiate their offerings. Partnerships and collaborations are common strategies, enabling firms to expand their market reach and accelerate product development. For example, Alver's innovative approach to microalgae-based ingredients has attracted significant attention in the food and beverage industry. Market dynamics are further shaped by increasing investments in biotechnological advancements and a growing focus on sustainability. The competitive landscape underscores the need for innovation, cost optimization, and consumer engagement to secure market positioning in this rapidly evolving sector.
Recent Developments:
- In March 2023, Roquette Frères completed the installation of a 110kV modular substation in Kazakhstan to support a 100MW solar plant.
- On November 21, 2024, DIC unveiled the Omnidirectional Multicopter HAGAMOSphere™, which was named a CES Innovation Awards™ 2025 Honoree. This new product is set to be showcased at CES 2025.
- On May 15, 2024, DSM announced the publication of its 2023 Integrated Annual Report, highlighting its achievements and financial performance for the year.
- On November 26, 2024, Roquette successfully completed its inaugural bond offering of EUR 1.2 billion to support its transformative acquisition of IFF Pharma Solutions, expected to close in the first half of 2025.
Market Concentration & Characteristics:
The microalgae food and beverage sector exhibit a moderately fragmented market structure, characterized by the presence of established global players and a growing number of regional and niche manufacturers. Leading companies such as Corbion, Cyanotech Corporation, and DIC Corporation hold significant market shares due to their extensive product portfolios, advanced R&D capabilities, and well-established supply chains. However, the market also features dynamic competition from emerging players and startups that focus on innovation and sustainability. The sector is driven by continuous advancements in biotechnology, enabling cost-effective production and enhanced product quality. The market’s characteristics include a strong emphasis on sustainability, reflecting global environmental concerns, and a growing consumer demand for natural and functional ingredients. Collaboration, partnerships, and strategic acquisitions are common strategies employed by key players to consolidate market positions and expand globally. This competitive yet collaborative environment underscores the sector’s potential for growth and innovation.
Report Coverage:
The research report offers an in-depth analysis based on By Species Type, By Source and By End Use Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing consumer preference for plant-based and functional foods will continue driving the adoption of microalgae-based products.
- Technological advancements in cultivation and processing will enhance cost efficiency and product scalability, enabling broader market penetration.
- Increasing investments in R&D will lead to the development of innovative microalgae applications across diverse food and beverage categories.
- Demand for sustainable and eco-friendly ingredients will reinforce microalgae’s position as a key solution for environmentally conscious consumers.
- Expansion into emerging markets, particularly in Asia-Pacific and Latin America, will unlock significant growth opportunities.
- The incorporation of microalgae in personalized nutrition products will rise as consumer focus on targeted health benefits intensifies.
- Strategic collaborations between industry players and research institutions will accelerate innovation and market expansion.
- Enhanced consumer awareness campaigns will bridge knowledge gaps and address misconceptions about microalgae’s taste and benefits.
- Regulatory harmonization across regions will streamline market entry and foster global adoption of microalgae-based products.
- Increasing application diversity, including use in non-dairy beverages, snacks, and supplements, will solidify microalgae’s mainstream presence in the food and beverage industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Plant-Based Nutrition
Growing consumer awareness of the health and environmental benefits of plant-based diets is driving demand for microalgae-derived food and beverage products, which are rich in proteins, vitamins, and essential fatty acids.
Sustainability and Eco-Friendly Production
Microalgae cultivation requires significantly less water, land, and energy compared to traditional agriculture, aligning with global sustainability goals and appealing to environmentally conscious consumers and corporations.
Rising Interest in Functional and Nutrient-Dense Foods
Consumers are increasingly seeking foods and beverages that offer additional health benefits, such as immune support and cardiovascular health, making microalgae's bioactive compounds highly attractive for functional product development.
Technological Advancements Lowering Costs
Innovations in cultivation and processing, such as improved photobioreactor technology, have reduced production costs and enhanced product quality, making microalgae ingredients more accessible for mainstream food and beverage applications.
Regulatory and Industry Support
Favorable government policies, investments in research, and regulatory initiatives - especially in North America, Europe, and Asia-Pacific - are accelerating the adoption and market penetration of microalgae-based products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the global microalgae food and beverage market?
What are the key drivers of the microalgae food and beverage market?
What are the main applications of microalgae in the food and beverage sector?
Which regions dominate the microalgae food and beverage market?
How are technological advancements impacting the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Freshwater
- 1.2.2 Marine
- 1.3 By Species Type
- 1.3.1 Spirulina
- 1.3.2 Chlorella
- 1.3.3 Dunaliella
- 1.3.4 Haematococcus
- 1.4 By End-Use Application
- 1.4.1 Dietary Supplements
- 1.4.2 Non-Dairy Beverages
- 1.4.3 Snacks
- 1.4.4 Baked Goods
- 1.4.5 Protein Powders
- 1.4.6 Energy Bars
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 673.7 million → 2032: USD 1,423.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Microalgae Food and Beverage Sector Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Microalgae Food and Beverage Sector Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Microalgae Food and Beverage Sector Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Microalgae Food and Beverage Sector Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Microalgae Food and Beverage Sector Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Microalgae Food and Beverage Sector Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Microalgae Food and Beverage Sector Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Microalgae Food and Beverage Sector Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 673.7 million → 2032: USD 1,423.26 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Microalgae Food and Beverage Sector Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Freshwater
- 12.3.7.2 Marine
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Species Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Spirulina
- 12.4.7.2 Chlorella
- 12.4.7.3 Dunaliella
- 12.4.7.4 Haematococcus
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Dietary Supplements
- 12.5.7.2 Non-Dairy Beverages
- 12.5.7.3 Snacks
- 12.5.7.4 Baked Goods
- 12.5.7.5 Protein Powders
- 12.5.7.6 Energy Bars
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Microalgae Food and Beverage Sector End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Microalgae Food and Beverage Sector Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Microalgae Food and Beverage Sector Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Microalgae Food and Beverage Sector Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DIC Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Koninklijke DSM NV
- 18.4 Roquette Frères
- 18.5 Fuji Chemical Industries Co., Ltd.
- 18.6 Cyanotech Corporation
- 18.7 BASF SE
- 18.8 Parry Nutraceuticals
- 18.9 Algatechnologies Ltd.
- 18.10 Valensa International
- 18.11 Yunnan Green-A-Bio-engineering Co Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

