
Europe Microalgae Fertilizer Market Overview:
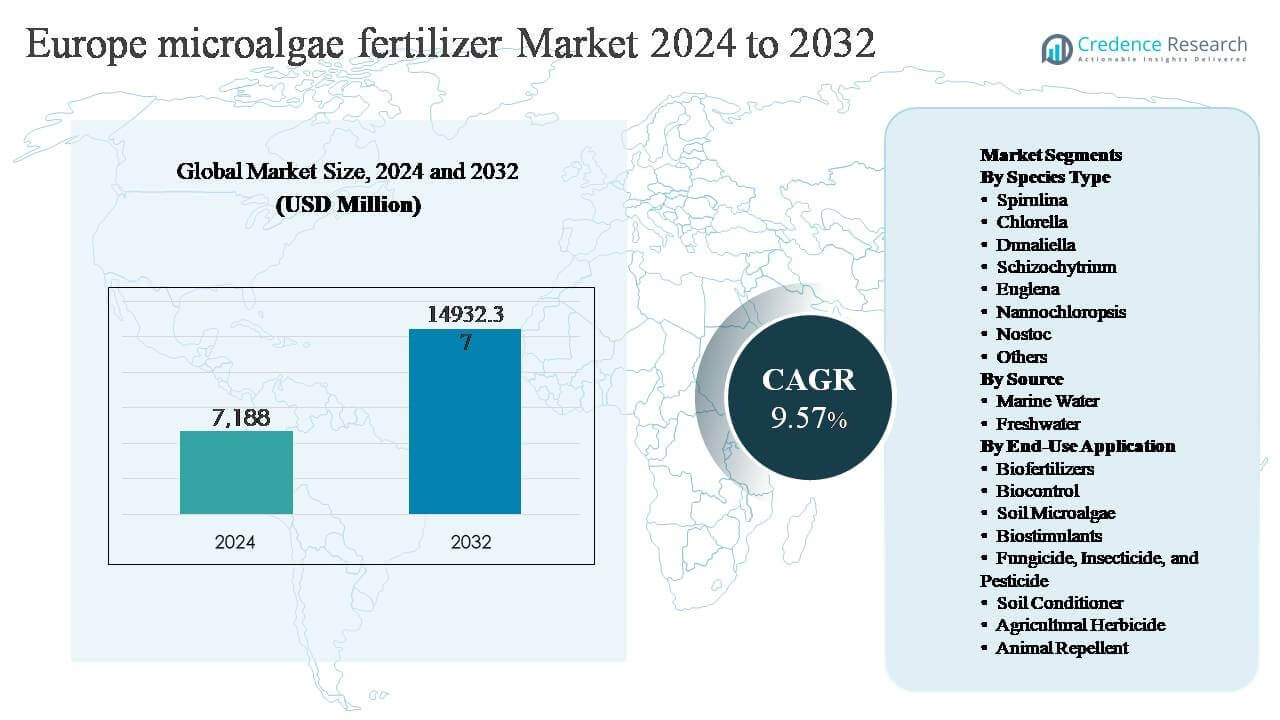
The Europe microalgae fertilizer market was valued at USD 7,188 million in 2024 and is projected to reach USD 14,932.37 million by 2032, expanding at a CAGR of 9.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Microalgae Fertilizer Market Size 2024 | USD 7,188 million |
| Europe Microalgae Fertilizer Market, CAGR | 9.57% |
| Europe Microalgae Fertilizer Market Size 2032 | USD 14,932.37 million |
Europe Microalgae Fertilizer Market Insights
- Market growth is primarily driven by stringent restrictions on chemical fertilizers, rising adoption of organic and regenerative farming, and increasing demand for soil health–enhancing biofertilizers, with biofertilizers accounting for over 40% segment share due to their role in improving nutrient efficiency and microbial activity.
- Key market trends include rapid growth in microalgae-based biostimulants, integration of fertilization with biocontrol functions, and increasing use of marine-water cultivation systems, which hold nearly 60% share owing to higher biomass productivity and scalability advantages.
- The competitive landscape is moderately fragmented, with players focusing on proprietary algae strains, advanced photobioreactor systems, and crop-specific formulations to strengthen positioning and comply with EU biostimulant and fertilizer regulations.
- Regionally, Western Europe leads with around 39% market share, followed by Southern Europe at ~28%, driven by strong organic farming penetration, advanced agri-biotech infrastructure, and favorable climatic conditions for algae cultivation.
Europe Microalgae Fertilizer Market Segmentation Analysis:
By Species Type:
By species type, Spirulina represents the dominant sub-segment in the Europe microalgae fertilizer market, accounting for approximately 34-36% of total demand. Its dominance is driven by high protein concentration, rich amino acid profiles, and natural growth-promoting compounds that enhance crop vigor and soil microbiology. Spirulina’s adaptability to large-scale cultivation and compatibility with organic farming standards further strengthen adoption. Chlorella follows closely due to its rapid biomass productivity and chlorophyll content, while Nostoc gains traction for nitrogen-fixation benefits. Emerging species such as Dunaliella and Nannochloropsis support niche applications focused on stress tolerance and soil conditioning.
- For instance, Industrial Spirulina cultivation systems in Europe produce dried biomass for agricultural inputs where protein levels typically reach 600-700 g per kg of dry matter. This biomass contains significant concentrations of phycocyanin typically ranging from 140 to 200 g per kg (14-20%) in standard industrial output a potent blue pigment and antioxidant linked to enhanced root development, improved seed germination, and the stimulation of beneficial soil microbes.
By Source:
By source, marine water–based microalgae constitute the dominant sub-segment, holding nearly 58-60% market share across Europe. This leadership is supported by higher biomass yields, access to mineral-rich growth media, and scalability advantages for commercial cultivation. Coastal countries benefit from established marine algae infrastructure and lower freshwater dependency, aligning with sustainability goals. Freshwater-sourced microalgae maintain steady growth, particularly in inland regions with controlled photobioreactor systems. Their appeal lies in consistent quality, contamination control, and suitability for high-value formulations, especially in organic and precision agriculture applications requiring standardized nutrient profiles.
- For instance, Necton S.A. in Portugal operates industrial marine microalgae photobioreactor and raceway systems using Atlantic seawater at salinity levels of 32–35 g/L, achieving areal productivities exceeding 18 g of dry biomass per square meter per day for species such as Nannochloropsis and Tetraselmis, which are increasingly incorporated into soil-conditioning and biostimulant fertilizer formulations.
By End-Use Application:
By end-use application, biofertilizers dominate the market with an estimated 41-43% share, driven by rising restrictions on synthetic fertilizers and strong adoption of organic farming across Europe. Microalgae-based biofertilizers enhance nutrient availability, soil microbial diversity, and long-term soil health. Biostimulants represent the fastest-growing sub-segment, supported by demand for improved crop resilience and yield efficiency. Applications in biocontrol and soil conditioning continue expanding as sustainable crop protection gains priority, while niche uses such as animal repellents and agricultural herbicides benefit from growing interest in chemical-free farm inputs.
Key Growth Drivers
Stringent Environmental Regulations and Sustainability Mandates
Europe’s microalgae fertilizer market is strongly driven by tightening environmental regulations that restrict the use of synthetic fertilizers and encourage sustainable nutrient management. EU-wide initiatives such as the Green Deal and the Farm to Fork Strategy promote reductions in chemical inputs, nitrogen runoff, and greenhouse gas emissions, creating favorable conditions for bio-based fertilizers. Microalgae fertilizers align with these mandates by offering biodegradable, low-impact alternatives that enhance nutrient efficiency and soil health. Governments and agricultural bodies across Germany, France, Italy, and Spain actively support organic and regenerative farming practices through subsidies and certification programs. This regulatory push accelerates adoption among both conventional and organic farmers seeking compliance while maintaining productivity, making policy support a core driver of sustained market expansion.
- For instance, AlgaEnergy has deployed its microalgae-based agricultural solutions across multiple EU pilot programs, where field applications demonstrated reductions of 30-40 kg of mineral nitrogen per hectare per season while maintaining crop vigor through improved root biomass and microbial activity.
Rising Adoption of Organic and Regenerative Agriculture
The expansion of organic and regenerative agriculture across Europe significantly boosts demand for microalgae-based fertilizers. Farmers increasingly prioritize soil restoration, biodiversity enhancement, and long-term yield stability, all of which are supported by microalgae formulations rich in amino acids, micronutrients, and bioactive compounds. These fertilizers improve soil structure, stimulate beneficial microbial communities, and increase crop resilience to abiotic stress. High penetration of organic farming in countries such as Austria, Sweden, and Denmark further strengthens demand. Additionally, consumer preference for residue-free and sustainably produced food incentivizes growers to replace synthetic inputs, positioning microalgae fertilizers as a practical solution that balances agronomic performance with environmental stewardship.
- For instance, Research into Spirulina-based biostimulants has demonstrated that these inputs deliver significant levels of free amino acids often exceeding 15 g/kg in concentrated hydrolyzed extracts and critical micronutrients such as iron and manganese.
Technological Advancements in Microalgae Cultivation and Processing
Continuous advancements in microalgae cultivation technologies play a critical role in market growth. Improvements in photobioreactors, open-pond optimization, and harvesting techniques have enhanced biomass productivity while lowering production costs. Innovations in downstream processing enable the development of concentrated, crop-specific formulations with improved shelf life and application efficiency. These technological gains support scalability and commercial viability, allowing suppliers to meet rising agricultural demand. Moreover, integration of waste streams such as CO₂ and nutrient-rich effluents into algae cultivation enhances circular economy alignment. As production efficiency improves, microalgae fertilizers become more cost-competitive, accelerating adoption across diverse crop systems.
Key Trends & Opportunities
Shift Toward Biostimulant-Enriched Fertilizer Formulations
A key trend shaping the Europe microalgae fertilizer market is the growing emphasis on biostimulant-enriched products. Farmers increasingly seek inputs that enhance nutrient uptake, stress tolerance, and crop quality rather than simple nutrient replacement. Microalgae-derived biostimulants containing polysaccharides, phytohormones, and antioxidants support plant metabolism and resilience against drought, salinity, and temperature fluctuations. This trend creates opportunities for manufacturers to develop differentiated, high-value formulations tailored to specific crops and growth stages. Regulatory recognition of biostimulants under EU fertilizer frameworks further supports commercialization, encouraging innovation and premium product positioning.
- For instance, Agronutrition (Lesaffre Group) has integrated microalgae extracts into its biostimulant portfolio, delivering formulations with significant antioxidant capacities that helped maintain leaf chlorophyll concentrations during heat-stress trials in Southern Europe.
Expansion into Integrated Crop Protection and Soil Health Solutions
Another major opportunity lies in the integration of microalgae fertilizers with biocontrol and soil health applications. Microalgae exhibit natural antifungal, antibacterial, and pest-deterrent properties, enabling their use in multifunctional formulations. Farmers increasingly favor inputs that combine fertilization, soil conditioning, and crop protection in a single application to reduce labor and chemical dependency. This trend supports the development of holistic solutions aligned with sustainable farming systems. As awareness grows around soil microbiome management, microalgae-based products gain traction as long-term soil health enhancers rather than short-term yield boosters.
- For instance, Cyanotech Corporation cultivates microalgae in open-pond systems at its 96-acre facility in Kona, Hawaii. It produces high-quality Spirulina biomass with C-phycocyanin concentrations ranging between 94.9 mg and 251 mg per gram (9.5%-25% dry weight) and carbohydrate content (primarily polysaccharides) typically between 15% and 20% of dry weight (equivalent to 150-200 g per kg).
Key Challenges
High Production Costs and Price Sensitivity
Despite technological progress, relatively high production costs remain a key challenge for the Europe microalgae fertilizer market. Cultivation infrastructure, energy requirements, and harvesting processes contribute to higher input costs compared to conventional fertilizers. Price-sensitive farmers, particularly in large-scale commodity crop segments, may hesitate to adopt microalgae products without clear cost-benefit validation. Although long-term soil and yield benefits are evident, upfront pricing remains a barrier. Manufacturers must continue optimizing production efficiency and scaling operations to improve affordability and broaden market penetration.
Limited Farmer Awareness and Standardization Gaps
Another significant challenge is limited awareness and inconsistent understanding of microalgae fertilizer benefits among farmers. Adoption is often constrained by insufficient agronomic knowledge, lack of standardized application guidelines, and variable performance across crops and soil types. Additionally, regulatory complexity and varying national interpretations of biofertilizer classifications can slow market entry. Addressing these gaps requires stronger extension services, field demonstrations, and standardized efficacy validation. Improved education and harmonized regulations will be essential to build confidence and accelerate widespread adoption across Europe.
Regional Analysis
Western Europe:
Western Europe dominates the Europe microalgae fertilizer market, accounting for approximately 38-40% market share. The region’s leadership is driven by strong regulatory enforcement on chemical fertilizer reduction, high penetration of organic farming, and advanced agri-biotechnology infrastructure. Countries such as Germany, France, the Netherlands, and the UK actively adopt microalgae-based biofertilizers and biostimulants to enhance soil health and comply with sustainability mandates. Well-established research ecosystems and commercial-scale algae cultivation facilities further support product innovation and adoption. High farmer awareness and government-backed sustainability programs continue to reinforce Western Europe’s leading position.
Southern Europe:
Southern Europe represents around 27-29% of the market, supported by favorable climatic conditions for microalgae cultivation and extensive use in horticulture, vineyards, and high-value crops. Spain, Italy, and Portugal lead regional demand due to water scarcity challenges and soil degradation issues, which drive adoption of soil-conditioning and biostimulant applications. Marine-water-based microalgae cultivation is particularly prominent in coastal areas, enhancing production efficiency. Strong export-oriented agriculture and increasing organic acreage further accelerate uptake, positioning Southern Europe as the second-largest regional contributor to market growth.
Northern Europe:
Northern Europe accounts for nearly 14-16% market share, driven by advanced sustainability practices and high adoption of regenerative agriculture. Countries such as Denmark, Sweden, Finland, and Norway emphasize low-input farming systems, supporting demand for microalgae-based biofertilizers and biocontrol solutions. Despite climatic limitations for large-scale outdoor cultivation, the region benefits from controlled photobioreactor systems and strong R&D investments. High environmental awareness among farmers and consumers supports consistent adoption, particularly in soil health enhancement and organic cereal production, sustaining steady regional growth.
Central & Eastern Europe:
Central and Eastern Europe collectively hold about 12-14% of the market, with growing adoption across Poland, Hungary, the Czech Republic, and Romania. Expansion is driven by gradual modernization of agricultural practices and increasing alignment with EU sustainability frameworks. Microalgae fertilizers are gaining traction as cost-effective solutions for improving soil fertility and crop resilience in nutrient-depleted farmlands. While adoption remains lower than in Western Europe, rising awareness, improving access to bio-based inputs, and EU-funded agricultural programs are supporting steady market expansion.
Rest of Europe:
The Rest of Europe, including smaller and non-EU countries, contributes approximately 5-7% market share. Adoption in these markets is driven primarily by niche organic farming, greenhouse cultivation, and specialty crop production. Limited large-scale production infrastructure constrains growth; however, increasing imports of microalgae-based fertilizers and growing interest in sustainable agriculture are gradually improving penetration. As regulatory harmonization and farmer education improve, these markets are expected to play a supportive role in the broader European microalgae fertilizer landscape.
Europe Microalgae Fertilizer Market Segmentations:
By Species Type
- Spirulina
- Chlorella
- Dunaliella
- Schizochytrium
- Euglena
- Nannochloropsis
- Nostoc
- Others
By Source
- Marine Water
- Freshwater
By End-Use Application
- Biofertilizers
- Biocontrol
- Soil Microalgae
- Biostimulants
- Fungicide, Insecticide, and Pesticide
- Soil Conditioner
- Agricultural Herbicide
- Animal Repellent
By Geography
- Western Europe
- Southern Europe
- Northern Europe
- Central & Eastern Europe
- Rest of Europe
Competitive Landscape
The competitive landscape of the Europe microalgae fertilizer market is characterized by the presence of specialized algae biotechnology companies, agri-biological input suppliers, and integrated biofertilizer manufacturers competing through innovation, scalability, and regulatory compliance. Market participants focus on proprietary microalgae strains, advanced cultivation systems, and crop-specific formulations to differentiate their offerings. Strategic investments in photobioreactor technology, marine-based cultivation, and downstream processing enable players to improve biomass yield and formulation efficiency. Partnerships with agricultural cooperatives, research institutes, and organic farming networks strengthen market access and product validation. Companies also emphasize compliance with EU fertilizer and biostimulant regulations to enhance credibility and adoption. Competitive intensity is further shaped by continuous product launches targeting soil health, nutrient efficiency, and stress tolerance. As sustainability and input efficiency become central to European agriculture, leading players with strong R&D capabilities, scalable production platforms, and established distribution networks are best positioned to consolidate market share.
Key Player Analysis
- Corbion
- AlgaEnergy
- Algatech
- Cyanotech Corporation
- Fitoplancton Marino
- Algafarm
- AlgaeCytes
- Bioprodukte Sp. z o.o.
- Nutress
- Nutra-Kol
Recent Developments
- In November 2023, AlgaEnergy announced a strategic partnership with a leading agricultural biotechnology company to co-develop innovative microalgae-based fertilizers tailored for European crop systems. This initiative leverages AlgaEnergy’s microalgae cultivation expertise and advanced biostimulant formulation technologies to enhance sustainability outcomes in European agriculture.
- In July 2023, with an annual revenue of over $100 billion, NTT Corporation, a global technology corporation, has partnered with the Regional Fish Institute to develop a three-step plan for producing fish and shellfish in RAS facilities that have been fed on algae cultivated in-house.
Report Coverage
The research report offers an in-depth analysis based on Species type, Source, End-Use application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of microalgae fertilizers will accelerate as EU sustainability and soil health regulations become more stringent.
- Biofertilizers will remain the dominant application as farmers prioritize long-term nutrient efficiency and soil restoration.
- Demand for microalgae-based biostimulants will increase due to rising climate stress and yield optimization needs.
- Marine water–based cultivation will expand further, supported by scalability and resource efficiency advantages.
- Technological improvements in photobioreactors and harvesting will enhance production efficiency and product consistency.
- Integration of microalgae fertilizers with biocontrol and crop protection solutions will gain wider acceptance.
- Large-scale adoption will grow as production costs decline and formulation efficiency improves.
- Strategic partnerships between algae producers and agricultural cooperatives will strengthen market penetration.
- Farmer awareness and acceptance will improve through demonstration trials and agronomic validation programs.
- Innovation in crop-specific and soil-targeted formulations will differentiate products and support sustained market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations and Sustainability Mandates
The European Union's Green Deal and Farm to Fork Strategy, along with national restrictions on chemical fertilizers, are driving rapid adoption of microalgae fertilizers as sustainable, biodegradable alternatives that help reduce nitrogen runoff and greenhouse gas emissions.
Rising Adoption of Organic and Regenerative Agriculture
Europe's expanding organic and regenerative farming sectors prioritize soil health, biodiversity, and residue-free food production, all of which are supported by microalgae fertilizers rich in amino acids, micronutrients, and bioactive compounds.
Technological Advancements in Microalgae Cultivation and Processing
Innovations in photobioreactor systems, marine-water cultivation, and downstream processing have improved biomass yields and reduced production costs, making microalgae fertilizers more commercially viable and scalable for European agriculture.
Shift Toward Biostimulant-Enriched Fertilizer Formulations
Farmers are increasingly seeking biostimulant-enriched fertilizers that enhance nutrient uptake, stress tolerance, and crop quality, driving demand for microalgae-based products with polysaccharides, phytohormones, and antioxidants.
Integration with Crop Protection and Soil Health Solutions
The multifunctional properties of microalgae, including natural antifungal and pest-deterrent effects, are enabling the development of integrated products that combine fertilization, soil conditioning, and biocontrol, aligning with sustainable farming practices and reducing chemical input dependency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe microalgae fertilizer, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe microalgae fertilizer projected to grow between 2024 and 2032?
Which Europe microalgae fertilizer segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe microalgae fertilizer market?
Who are the leading companies in the Europe microalgae fertilizer market?
Which region commanded the largest share of the Europe microalgae fertilizer market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Marine Water
- 1.2.2 Freshwater
- 1.3 By Species Type
- 1.3.1 Spirulina
- 1.3.2 Chlorella
- 1.3.3 Dunaliella
- 1.3.4 Schizochytrium
- 1.3.5 Euglena
- 1.3.6 Nannochloropsis
- 1.3.7 Nostoc
- 1.3.8 Others
- 1.4 By End-Use Application
- 1.4.1 Biofertilizers
- 1.4.2 Biocontrol
- 1.4.3 Soil Microalgae
- 1.4.4 Biostimulants
- 1.4.5 Fungicide, Insecticide, and Pesticide
- 1.4.6 Soil Conditioner
- 1.4.7 Agricultural Herbicide
- 1.4.8 Animal Repellent
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,188 million → 2032: USD 14,932.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Microalgae Fertilizer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Microalgae Fertilizer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Microalgae Fertilizer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Microalgae Fertilizer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Microalgae Fertilizer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Microalgae Fertilizer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Microalgae Fertilizer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Microalgae Fertilizer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,188 million → 2032: USD 14,932.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Microalgae Fertilizer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Marine Water
- 12.3.7.2 Freshwater
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Species Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Spirulina
- 12.4.7.2 Chlorella
- 12.4.7.3 Dunaliella
- 12.4.7.4 Schizochytrium
- 12.4.7.5 Euglena
- 12.4.7.6 Nannochloropsis
- 12.4.7.7 Nostoc
- 12.4.7.8 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Biofertilizers
- 12.5.7.2 Biocontrol
- 12.5.7.3 Soil Microalgae
- 12.5.7.4 Biostimulants
- 12.5.7.5 Fungicide, Insecticide, and Pesticide
- 12.5.7.6 Soil Conditioner
- 12.5.7.7 Agricultural Herbicide
- 12.5.7.8 Animal Repellent
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Microalgae Fertilizer End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Microalgae Fertilizer Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Microalgae Fertilizer Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Microalgae Fertilizer Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Corbion
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 AlgaEnergy
- 18.4 Algatech
- 18.5 Cyanotech Corporation
- 18.6 Fitoplancton Marino
- 18.7 Algafarm
- 18.8 AlgaeCytes
- 18.9 Bioprodukte Sp. z o.o.
- 18.10 Nutress
- 18.11 Nutra-Kol
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

