
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Microalgae-based Products Market Size 2024 | USD 2,516.1 million |
| Microalgae-based Products Market, CAGR | 7.30% |
| Microalgae-based Products Market Size 2032 | USD 3,569.2 million |
Market overview
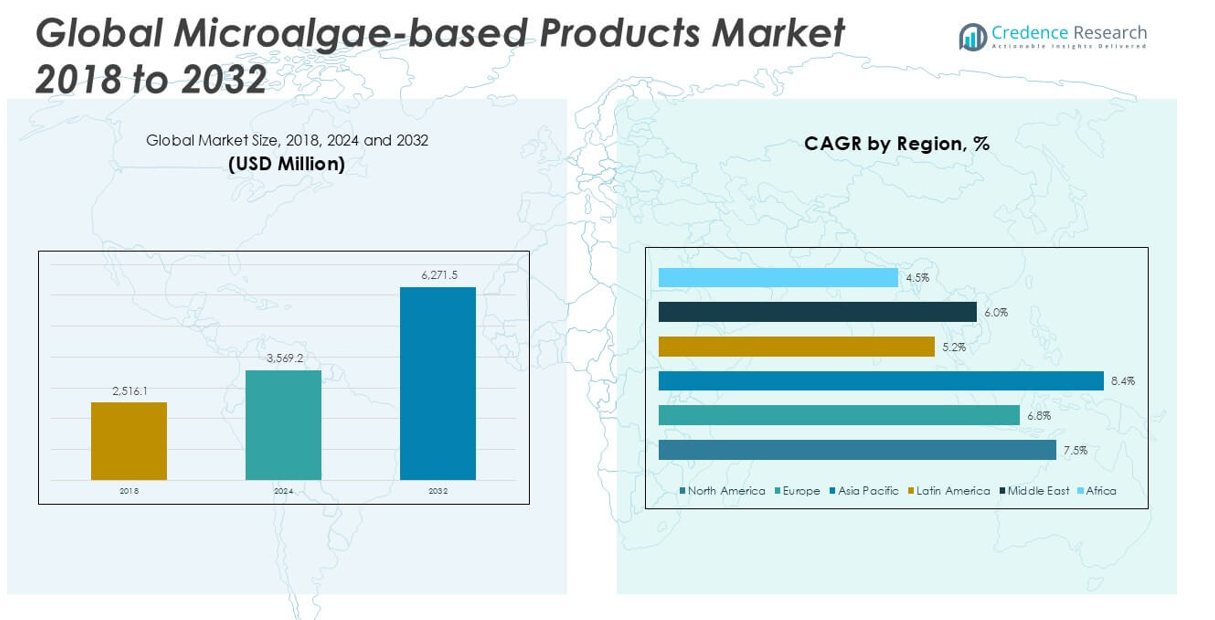
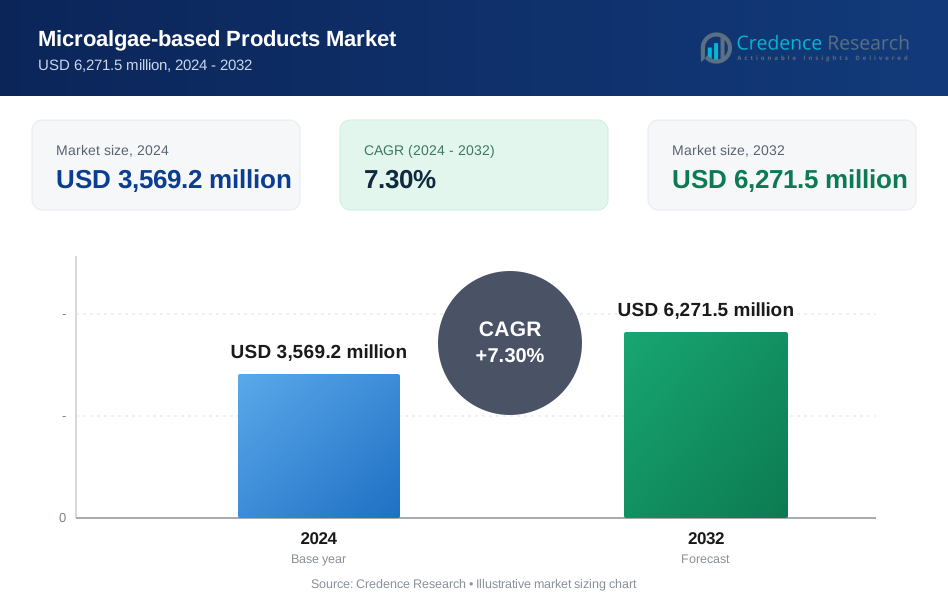
The Microalgae-based Products market size was valued at USD 2,516.1 million in 2018, reached USD 3,569.2 million in 2024, and is anticipated to reach USD 6,271.5 million by 2032, growing at a CAGR of 7.30% during the forecast period.
The Microalgae-based Products market is led by top players such as Cyanotech Corporation, Corbion N.V., E.I.D. Parry (Parry Nutraceuticals), DIC Corporation (Earthrise Nutritionals), DSM-Firmenich, BASF SE, and Cargill, Inc., all of which hold significant market positions through extensive product portfolios, global reach, and continuous innovation. These companies focus on expanding applications across food, nutraceuticals, personal care, and pharmaceuticals to strengthen their market presence. North America is the leading region, commanding approximately 34.2% of the global market share in 2024, driven by high consumer demand for functional foods, dietary supplements, and sustainable products. Europe and Asia Pacific follow, contributing significantly to global market growth through regulatory support and rising health awareness.
Market Insights
- The Microalgae-based Products market was valued at USD 3,569.2 million in 2024 and is projected to reach USD 6,271.5 million by 2032, growing at a CAGR of 7.30% during the forecast period.
- Rising demand for plant-based, functional, and sustainable food products is driving market growth, with Spirulina leading by type and Food & Beverages holding the largest application share.
- Increasing focus on sustainable sourcing, advancements in algae cultivation technologies, and growing applications in personal care and pharmaceuticals are key market trends.
- The market is highly competitive with major players like Cyanotech Corporation, Corbion N.V., DIC Corporation, DSM-Firmenich, and BASF SE, but high production and processing costs remain a key restraint limiting large-scale adoption.
- North America holds the largest regional share at 34.2% in 2024, followed by Europe at 28.7% and Asia Pacific at 23.1%, with Asia Pacific expected to witness the fastest growth at a CAGR of 8.4%
Market Segmentation Analysis:
By Type:
Spirulina dominates the Microalgae-based Products market by type, holding the largest market share due to its high protein content and growing popularity in the food, nutraceutical, and dietary supplement industries. Spirulina’s rich nutritional profile, including essential amino acids, vitamins, and antioxidants, drives its extensive use in health foods and functional beverages. Chlorella follows as a significant sub-segment, supported by its detoxifying properties and immune-boosting benefits, making it a preferred ingredient in dietary supplements. Other important types include Astaxanthin, valued for its strong antioxidant properties in skincare and nutraceuticals, and PUFA fatty acids, which are rapidly gaining traction as a sustainable source of plant-based omega-3s. Dunaliella Salina, Beta-carotene, Lutein, and other microalgae-based types are growing steadily, driven by increasing demand for natural colorants and plant-derived bioactive compounds across personal care and pharmaceutical applications.
- For instance, Cyanotech Corporation produces over 500 metric tons of Spirulina annually at its 90-acre production facility in Hawaii, serving the global health food and supplement markets.
By Application
Food & Beverages lead the Microalgae-based Products market by application, holding the largest share due to rising consumer interest in plant-based and functional foods. Spirulina and Chlorella are widely incorporated into health drinks, protein bars, and natural colorants, driving growth in this segment. Nutraceuticals and dietary supplements form another major application area, supported by the increasing demand for immunity-boosting, clean-label, and plant-based supplements, with Astaxanthin, Spirulina, and Chlorella being key contributors. The personal care segment is growing steadily, driven by the adoption of microalgae-derived antioxidants in skincare and cosmetics. Pharmaceuticals, animal feed, chemicals, and fuel applications are expanding as industries seek sustainable, bio-based alternatives, although challenges like high production costs and scalability limit rapid growth in fuel and chemical segments.
- For example, Algenol Biotech developed algae strains capable of producing up to 9,000 liters of ethanol per acre per year in pilot-scale biofuel operations.
Market Overview
Rising Demand for Plant-Based and Functional Foods
The increasing consumer shift toward plant-based diets and functional foods is a major growth driver for the Microalgae-based Products market. Microalgae such as Spirulina and Chlorella are rich in proteins, vitamins, and antioxidants, making them ideal ingredients for health-conscious consumers. Growing awareness of the nutritional benefits and sustainability of microalgae further boosts their integration into food, beverages, and supplements. This rising preference for natural, clean-label, and nutrient-dense products significantly propels market expansion.
- For instance, Far East Bio-Tec (FEBICO) produces over 1,000 metric tons of microalgae products annually, with more than 60% directed toward plant-based and functional food applications across Asia.
Growing Focus on Sustainable and Eco-Friendly Production
Environmental concerns and the global push for sustainability are accelerating the adoption of microalgae-based products. Microalgae cultivation requires minimal land, captures carbon dioxide, and produces high yields, offering a more sustainable alternative to traditional agriculture and marine-sourced ingredients. Industries, particularly in food, pharmaceuticals, and chemicals, are increasingly opting for algae-based inputs to reduce their environmental footprint. This trend toward green production practices positions microalgae as a key solution in meeting sustainability targets.
- For instance, Cellana, Inc. has developed algae farms that can sequester over 3,500 metric tons of CO₂ annually while producing algae for high-value oils and animal feed.
Expanding Applications in Personal Care and Pharmaceuticals
Microalgae-based products are experiencing strong demand in the personal care and pharmaceutical sectors due to their bioactive properties, including anti-inflammatory and antioxidant effects. Astaxanthin, beta-carotene, and PUFA fatty acids are increasingly used in anti-aging skincare, therapeutic formulations, and preventive healthcare products. The push for natural and sustainable ingredients in cosmetics and drug development is driving manufacturers to invest in algae-based solutions, further supporting the diversification and growth of the market across new application areas.
Key Trends & Opportunities
Advancements in Algae Cultivation Technologies
Technological innovations in algae cultivation, including photobioreactor systems and open-pond methods, are enhancing production efficiency and reducing costs. These advancements enable large-scale, controlled microalgae farming, improving quality and yield consistency. As production becomes more cost-effective, microalgae-based products are expected to penetrate broader markets. This presents significant opportunities for companies to develop innovative applications in nutraceuticals, cosmetics, and even biofuels, supporting long-term market growth.
- For instance, AlgaeEnergy S.A. operates large-scale photobioreactors capable of producing over 400 metric tons of microalgae biomass annually with controlled nutrient and light optimization.
Increasing Investment in Algae-Based Omega-3 Alternatives
The growing demand for sustainable, plant-based omega-3 sources creates new opportunities for microalgae-derived PUFA fatty acids. Traditionally sourced from fish oil, omega-3s are now being extracted from microalgae to meet the rising demand from vegetarian and vegan consumers. This shift not only addresses sustainability concerns but also taps into the growing health supplements market. Companies are actively investing in the development of high-purity, algae-based omega-3 products to capture this expanding consumer base.
- For instance, Corbion N.V. operates facilities with the capacity to produce over 600 metric tons of algae-based omega-3 oil annually, supplying leading dietary supplement brands worldwide
Key Challenges
High Production and Processing Costs
One of the primary challenges facing the Microalgae-based Products market is the high cost of cultivation, harvesting, and processing. Algae production requires controlled environments, energy-intensive processes, and specialized equipment, which contribute to elevated operational expenses. These costs limit the competitiveness of microalgae-derived products compared to conventional alternatives, particularly in price-sensitive markets like animal feed and biofuels, restricting the speed of large-scale adoption.
Scalability and Standardization Issues
Achieving consistent quality and scaling up microalgae production remains a significant hurdle. Variations in environmental conditions, contamination risks, and the complexity of large-scale algae cultivation make it difficult to maintain uniformity across batches. These challenges hinder mass production, complicate supply chains, and may lead to inconsistent product performance, posing reliability concerns for manufacturers, especially in pharmaceutical and food-grade applications.
Limited Consumer Awareness and Acceptance
Despite the growing interest in sustainable ingredients, many consumers remain unfamiliar with microalgae-based products and their benefits. Limited awareness and misconceptions regarding taste, safety, and application versatility can hinder market growth. Consumer education and effective marketing strategies are essential to increase acceptance and drive demand across both mainstream and niche product categories. Without stronger awareness initiatives, the market may struggle to reach its full potential.
Regional Analysis
North America
North America holds the largest share of the Microalgae-based Products market, accounting for approximately 34.2% of the global market in 2024. The market size increased from USD 910.8 million in 2018 to USD 1,220.7 million in 2024, and it is projected to reach USD 1,981.8 million by 2032, growing at a CAGR of 7.5%. The region's dominance is driven by rising consumer demand for functional foods, dietary supplements, and plant-based alternatives, particularly in the United States. Strong investments in nutraceuticals and increasing adoption of microalgae in personal care and pharmaceuticals further support market growth.
Europe
Europe represents a significant market for microalgae-based products, holding a 28.7% market share in 2024. The market expanded from USD 714.6 million in 2018 to USD 1,024.4 million in 2024, and is anticipated to reach USD 1,850.1 million by 2032, at a CAGR of 6.8%. The region benefits from increasing regulatory support for sustainable and natural food ingredients. Growing consumer awareness of the health benefits of microalgae and rising demand in the personal care industry contribute to sustained market expansion across key European countries, particularly Germany, France, and the United Kingdom.
Asia Pacific
Asia Pacific is the fastest-growing regional market, with a 23.1% share in 2024 and a projected CAGR of 8.4%. The market size rose from USD 535.9 million in 2018 to USD 824.5 million in 2024, and is expected to reach USD 1,517.7 million by 2032. Growth is driven by increasing health consciousness, rapid urbanization, and rising demand for dietary supplements and functional foods, particularly in China, Japan, and India. Expanding applications in pharmaceuticals and animal feed, coupled with growing investments in sustainable production, further accelerate market penetration in this region.
Latin America
Latin America holds a modest 4.3% market share in 2024 within the Microalgae-based Products market. The market size grew from USD 113.2 million in 2018 to USD 153.5 million in 2024, and is expected to reach USD 307.3 million by 2032, growing at a CAGR of 5.2%. Growth in this region is supported by increasing interest in natural food additives and the gradual adoption of plant-based proteins. Brazil and Mexico are key markets, where improving consumer awareness and expanding food and beverage sectors contribute to the region's steady growth trajectory.
Middle East
The Middle East accounts for a 6.2% market share in 2024, with the market size rising from USD 156.0 million in 2018 to USD 221.3 million in 2024, and forecasted to reach USD 420.2 million by 2032, at a CAGR of 6.0%. The market is driven by growing health awareness, increasing demand for functional and fortified foods, and rising interest in sustainable agricultural practices. Countries like the UAE and Saudi Arabia are focusing on diversifying their economies, which is positively influencing the adoption of innovative, microalgae-based food and cosmetic products.
Africa
Africa holds the smallest market share at 3.5% in 2024 within the Microalgae-based Products market. The regional market grew from USD 85.5 million in 2018 to USD 124.9 million in 2024, and is projected to reach USD 194.4 million by 2032, expanding at a CAGR of 4.5%. Although still emerging, the African market shows potential due to increasing urbanization and growing awareness of nutritional products. Demand for sustainable, affordable protein sources and clean-label food ingredients is gradually rising across key countries, offering long-term growth opportunities despite current infrastructural and economic constraints.
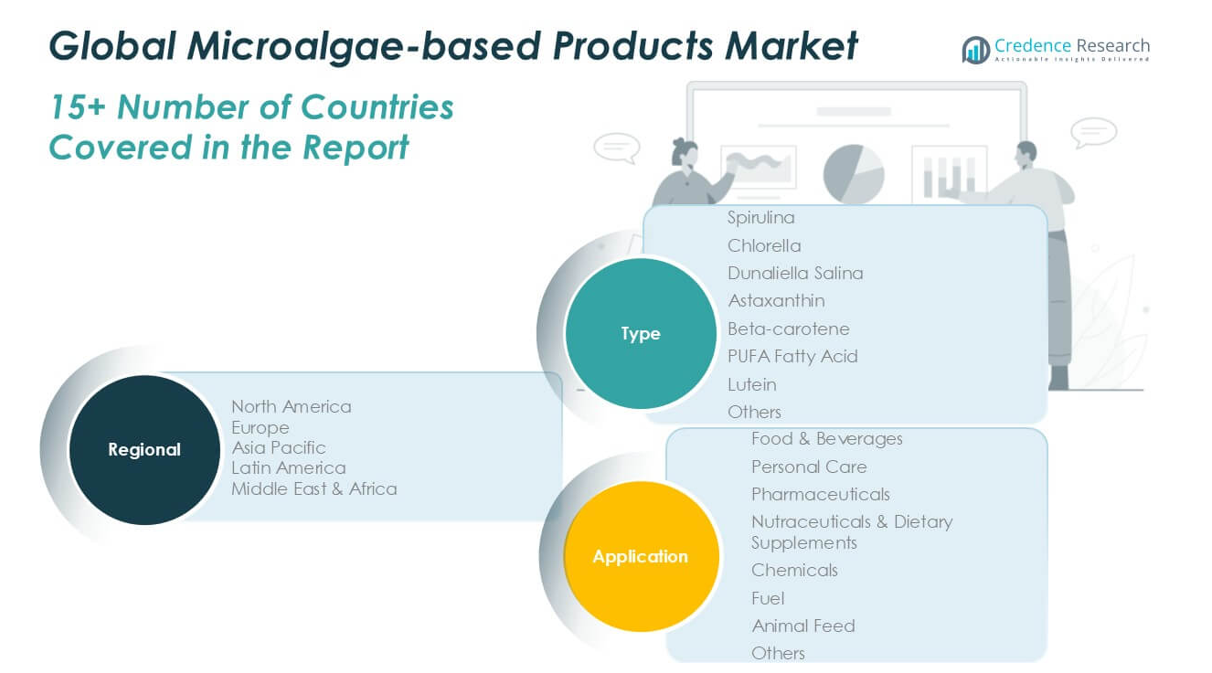
Market Segmentations:
By Type
- Spirulina
- Chlorella
- Dunaliella Salina
- Astaxanthin
- Beta-carotene
- PUFA Fatty Acid
- Lutein
- Others
By Application
- Food & Beverages
- Personal Care
- Pharmaceuticals
- Nutraceuticals & Dietary Supplements
- Chemicals
- Fuel
- Animal Feed
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Microalgae-based Products market is highly competitive, featuring a mix of established players and emerging companies focused on innovation and sustainability. Leading companies such as Cyanotech Corporation, Corbion N.V., E.I.D. Parry, DIC Corporation, DSM-Firmenich, BASF SE, and Cargill, Inc. dominate the market through extensive product portfolios, advanced cultivation technologies, and strong global distribution networks. These players continuously invest in research and development to improve product quality, expand applications, and lower production costs. Strategic partnerships, acquisitions, and geographic expansion are key growth strategies shaping the competitive landscape. Additionally, rising demand for natural, plant-based, and eco-friendly ingredients continues to encourage new entrants and innovation, gradually intensifying competition within the market.
Key Player Analysis
- Cyanotech Corporation
- Corbion N.V.
- E.I.D. Parry (Parry Nutraceuticals)
- Far East Bio-Tec (FEBICO)
- Fuqing King Dnarmsa Spirulina
- DIC Corporation (Earthrise Nutritionals)
- DSM-Firmenich
- BASF SE
- Cargill, Inc.
- AlgaeEnergy S.A.
- Algaetechologies (Solabia Group)
- Cellana, Inc.
- Algenol Biotech
- Bluetec Naturals
Recent Developments
- In April 2025, BASF expanded its portfolio of natural-based ingredients with three new products aimed at enhancing sustainability in personal care, leveraging bio-based and algae-derived feedstocks.
- In January 2024, Corbion launched its "Advance 2025" strategy, which includes a significant increase in investments in algae-based ingredients. This strategy also involves a restructuring of the business into two units: Functional Ingredients & Solutions and Health & Nutrition, with the goal of driving growth in sustainable algae-derived products.
- In September 2023, Corbion N.V. launched AlgaPrime™ DHA P3, a new algae-based omega-3 ingredient. This ingredient is designed to enhance both sustainability and nutritional value in aquaculture and other markets, particularly in the pet food industry. It offers a sustainable alternative to fish oil, supporting healthy diets and reducing pressure on marine resources.
Market Concentration & Characteristics
The Microalgae-based Products Market is moderately concentrated, with a mix of global leaders and regional players competing across diverse applications. It features strong participation from established companies such as Cyanotech Corporation, Corbion N.V., DIC Corporation, DSM-Firmenich, and BASF SE, which control significant portions of the market through advanced technologies and broad distribution networks. It remains highly innovation-driven, with companies focusing on developing new products, improving cultivation efficiency, and expanding into functional foods, personal care, and pharmaceuticals. The market is characterized by increasing consumer demand for natural, plant-based, and sustainable ingredients, pushing manufacturers to invest in research and product diversification. It faces key barriers including high production costs, scalability issues, and limited consumer awareness in some regions. North America holds the largest regional share, supported by a strong demand for dietary supplements and functional foods. The competitive landscape encourages strategic collaborations, mergers, and regional expansion to strengthen market positions and capture emerging opportunities.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for microalgae-based products is expected to grow steadily due to increasing consumer preference for plant-based and sustainable ingredients.
- Functional foods and dietary supplements will continue to drive significant market growth, supported by rising health awareness.
- The personal care and cosmetics industry will adopt more microalgae-derived ingredients due to their antioxidant and anti-aging properties.
- Technological advancements in algae cultivation and processing will improve production efficiency and lower costs.
- Asia Pacific is projected to remain the fastest-growing region, driven by expanding consumer markets and rising demand for natural products.
- Key players are likely to invest more in research and development to diversify product applications and enhance quality.
- Strategic collaborations and partnerships will become common as companies aim to strengthen market presence and global reach.
- Regulatory support for natural additives will encourage further adoption of microalgae-based ingredients across food and pharmaceutical industries.
- The demand for algae-based omega-3 fatty acids will increase, particularly among vegetarian and vegan consumers.
- Market growth may be moderated by challenges such as high production costs, limited scalability, and low consumer awareness in emerging markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Microalgae-based Products Market?
What are the key segments within the Microalgae-based Products Market?
What are some challenges faced by the Microalgae-based Products Market?
Who are the major players in the Microalgae-based Products Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Microalgae-based Products Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Microalgae-based Products Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,569.2 million → 2032: USD 6,271.5 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Microalgae-based Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Microalgae-based Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Microalgae-based Products Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Microalgae-based Products Market Drivers
- 3.3 Microalgae-based Products Market Restraints & Challenges
- 3.4 Microalgae-based Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Microalgae-based Products Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Microalgae-based Products Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Microalgae-based Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Microalgae-based Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Microalgae-based Products Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Microalgae-based Products. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Microalgae-based Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Microalgae-based Products Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Microalgae-based Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Microalgae-based Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Microalgae-based Products
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Microalgae-based Products Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Microalgae-based Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Microalgae-based Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Microalgae-based Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Microalgae-based Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Microalgae-based Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Microalgae-based Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Microalgae-based Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
