
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
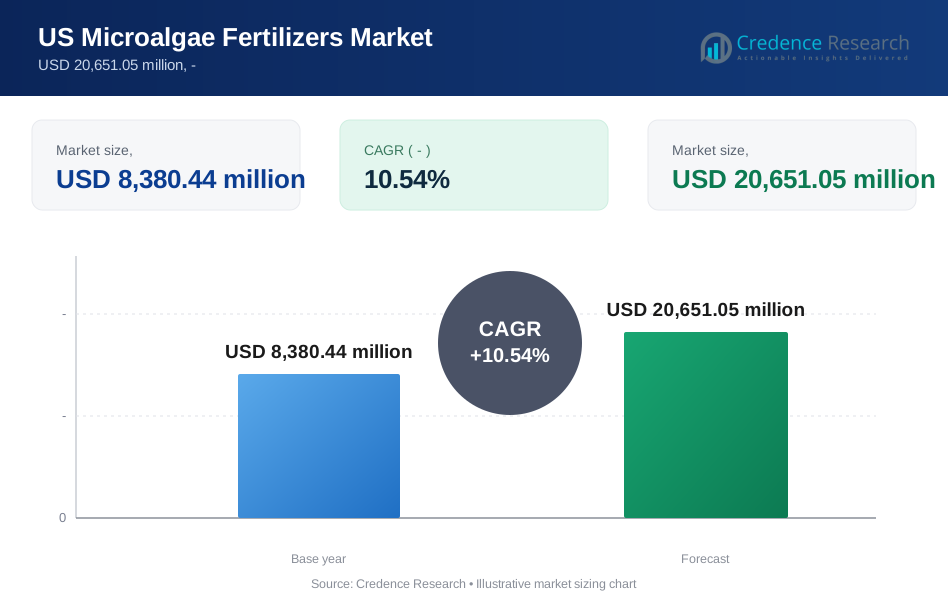
| US Microalgae Fertilizers Market Size 2023 | USD 8,380.44 Million |
| US Microalgae Fertilizers Market, CAGR | 10.54% |
| US Microalgae Fertilizers Market Size 2032 | USD 20,651.05 Million |
Market Overview
The US Microalgae Fertilizers Market is witnessing robust growth, poised to expand from USD 8,380.44 million in 2023 to an estimated USD 20,651.05 million by 2032 with a compound annual growth rate (CAGR) of 10.54% from 2024 to 2032. Several factors are driving this expansion, including increasing demand for sustainable agricultural practices and the growing awareness of microalgae-based fertilizers' benefits. Microalgae fertilizers offer a sustainable alternative to traditional chemical fertilizers, as they are rich in essential nutrients like nitrogen, phosphorus, and potassium while also enhancing soil health and promoting crop yield.
The rising adoption of organic farming practices is a key driver propelling the growth of the microalgae fertilizers market in the US. Consumers are becoming increasingly conscious of the environmental impact of conventional farming methods and are actively seeking eco-friendly alternatives. Microalgae-based fertilizers align with these sustainability goals, as they are produced using renewable resources and do not contain harmful chemicals or synthetic additives. Furthermore, the emphasis on reducing carbon emissions and conserving natural resources is bolstering the demand for eco-friendly agricultural inputs, thereby driving the market growth.
In addition to environmental considerations, the efficacy of microalgae fertilizers in improving crop productivity is contributing to their rising popularity among farmers and growers. Microalgae-based formulations provide a balanced blend of nutrients that are readily available to plants, promoting healthy growth and development. Moreover, these fertilizers enhance soil fertility and microbial activity, leading to improved nutrient uptake by plants and better overall yields. As farmers seek to maximize crop productivity and optimize resource utilization, microalgae fertilizers emerge as a preferred choice due to their efficacy and sustainable nature.
The US Microalgae Fertilizers Market is also benefiting from advancements in technology and research, which have led to the development of innovative formulations and production methods. Manufacturers are investing in research and development activities to enhance the efficiency and effectiveness of microalgae-based fertilizers, thereby expanding their applicability across a wide range of crops and growing conditions. Additionally, strategic partnerships and collaborations between industry players and academic institutions are driving innovation and facilitating knowledge exchange, further propelling market growth. With favorable market dynamics and increasing consumer demand for sustainable agricultural solutions, the US Microalgae Fertilizers Market is poised for significant expansion in the coming years.
Segmentations
By Species
- Spirulina
- Chlorella
- Dunaliella
By Application
- Agriculture
- Horticulture
- Turf and Ornamentals
By Source
- Marine Microalgae
- Freshwater Microalgae
Market Drivers
Environmental Sustainability Initiatives:
The emphasis on environmental sustainability is increasing. For instance, 78% of consumers feel that sustainability is important. The detrimental effects of traditional chemical fertilizers are becoming more recognized, with studies showing that nearly two-thirds of the nitrogen we use on our crops becomes a pollutant. This drives the demand for microalgae fertilizers in the US market. Microalgae fertilizers offer a sustainable alternative to conventional fertilizers as they are derived from renewable sources and contribute to reducing the environmental impact of agricultural practices. Consumers and agricultural producers are increasingly adopting microalgae fertilizers to mitigate soil degradation, minimize nutrient runoff, and promote eco-friendly farming practices. Furthermore, regulatory initiatives promoting sustainable agriculture, such as the implementation of organic farming standards and environmental conservation programs, incentivize the adoption of microalgae fertilizers among farmers seeking to enhance soil health and preserve natural ecosystems.
Growing Demand for Organic and Plant-Based Products:
The consumer preference for organic and plant-based products is rising. For instance, U.S. organic retail sales increased by an average of 8 percent per year and were estimated to be more than $52 billion in 2021. This fuels the demand for microalgae fertilizers in the US agricultural sector. Microalgae fertilizers are naturally rich in essential nutrients, vitamins, and micronutrients, making them well-suited for organic farming practices and enhancing the nutritional quality of crops. As consumers increasingly prioritize health-conscious choices and environmentally friendly products, there is a surge in demand for organic produce cultivated using sustainable farming methods. Microalgae fertilizers offer a viable solution for farmers seeking to meet the stringent requirements of organic certification while maximizing crop yields and quality. Moreover, the growing popularity of plant-based diets and the increasing demand for plant-derived ingredients in food, pharmaceuticals, and cosmetics industries drive the adoption of microalgae fertilizers to support sustainable crop cultivation and meet market demand for plant-based products.
Technological Advancements and Research Innovation:
Technological advancements and ongoing research initiatives in microalgae cultivation and biotechnology propel innovation in the US microalgae fertilizers market. Breakthroughs in bioreactor design, cultivation techniques, and strain optimization enable the efficient production of high-quality microalgae biomass for fertilizer applications. Research institutions, academic centers, and biotechnology companies are actively engaged in developing novel microalgae-based fertilizers with enhanced nutrient content, bioavailability, and agronomic performance. Additionally, advancements in sustainable farming technologies, such as precision agriculture, sensor-based monitoring systems, and bioinformatics, facilitate the integration of microalgae fertilizers into modern farming practices, optimizing nutrient management and crop productivity. As a result, the US microalgae fertilizers market continues to evolve, driven by technological innovation and research-driven solutions aimed at addressing the challenges of global food security, environmental sustainability, and agricultural resilience.
Market Trends
Increased Adoption of Precision Agriculture Techniques:
Precision agriculture techniques, such as remote sensing, GPS-guided equipment, and data analytics, are gaining traction in the US microalgae fertilizers market. These technologies enable farmers to make data-driven decisions regarding fertilizer application, optimizing nutrient inputs and minimizing waste. Microalgae fertilizers are well-suited for precision agriculture practices due to their targeted nutrient delivery and compatibility with variable rate application systems.
Rising Popularity of Organic and Non-GMO Products:
Consumer demand for organic and non-GMO products is driving the adoption of microalgae fertilizers in the US. As consumers become more health-conscious and environmentally aware, there is a growing preference for sustainably produced, chemical-free food. Microalgae-based fertilizers align with organic farming principles and are perceived as natural, eco-friendly alternatives to synthetic fertilizers, making them increasingly popular among organic growers and consumers.
Emergence of Biofortification and Nutrient Enrichment: Biofortification and nutrient enrichment are emerging trends in the US microalgae fertilizers market, driven by the demand for nutrient-dense crops with enhanced nutritional value. For instance, it’s estimated that improving nutrition through biofortification could potentially reduce malnutrition rates by up to 30% in vulnerable populations. Microalgae-based fertilizers are utilized to fortify crops with essential nutrients such as vitamins, minerals, and antioxidants, improving their nutritional profile and health benefits. This trend is particularly relevant in addressing micronutrient deficiencies and combating malnutrition in vulnerable populations.
Integration of Microalgae in Sustainable Crop Rotation Systems:
Microalgae fertilizers are being integrated into sustainable crop rotation systems as part of efforts to improve soil health and fertility. For instance, studies have shown that microalgae can increase crop yields by up to 20% by fixing nitrogen, releasing soil trace elements, solubilizing potassium, and phosphorus, producing exopolysaccharides, and converting organic matter into utilizable nutrients. By incorporating microalgae biomass into crop rotation cycles, farmers can replenish soil nutrients, suppress pests and diseases, and reduce the need for external inputs. This practice supports regenerative agriculture principles and promotes long-term soil sustainability, contributing to the resilience of agroecosystems against environmental challenges.
Expansion of Microalgae Cultivation for Fertilizer Production:
The expansion of microalgae cultivation for fertilizer production is a notable trend in the US market. With advancements in cultivation technologies and scalability, manufacturers are ramping up production to meet the growing demand for microalgae-based fertilizers. For instance, the use of advanced cultivation technologies has led to a 25% increase in microalgae biomass production over the past five years. Large-scale cultivation facilities, including open ponds and photobioreactors, are being established to sustainably produce high-quality microalgae biomass for fertilizer manufacturing, ensuring a reliable supply chain and market availability.
Innovation in Product Formulations and Delivery Systems:
Innovation in product formulations and delivery systems is driving product differentiation and market competitiveness in the US microalgae fertilizers market. Manufacturers are developing novel formulations that combine microalgae biomass with other organic inputs, bio-stimulants, and microbial inoculants to enhance efficacy and agronomic benefits. Additionally, advancements in application technologies, such as foliar sprays, seed coatings, and drip irrigation systems, are improving the efficiency and convenience of microalgae fertilizer application, further driving market adoption.
Market Restraints and Challenges
Cost Competitiveness Against Conventional Fertilizers:
One of the primary challenges facing the US microalgae fertilizers market is the cost competitiveness against conventional chemical fertilizers. While microalgae-based fertilizers offer numerous environmental and agronomic benefits, their production costs are often higher compared to synthetic fertilizers. This price differential can deter cost-conscious farmers from adopting microalgae fertilizers, particularly in price-sensitive commodity crop markets where profit margins are tight.
Limited Scalability of Microalgae Cultivation:
The limited scalability of microalgae cultivation poses a significant restraint on the growth of the US microalgae fertilizers market. Cultivating microalgae biomass on a large scale requires considerable infrastructure investment, specialized equipment, and expertise in algal cultivation techniques. Challenges such as contamination, fluctuating environmental conditions, and production variability can hinder the scalability and reliability of microalgae biomass production, impacting supply chain stability and market penetration.
Lack of Standardized Regulation and Certification:
The absence of standardized regulation and certification for microalgae fertilizers presents a challenge for market stakeholders in the US. Unlike conventional chemical fertilizers, which are subject to strict regulatory oversight and quality control standards, microalgae-based products may lack uniformity in terms of nutrient content, efficacy, and safety. The absence of clear regulatory guidelines and certification schemes can create uncertainty among farmers and consumers regarding the reliability and performance of microalgae fertilizers, impeding market acceptance and adoption.
Limited Awareness and Education Among Farmers:
Limited awareness and education among farmers about the benefits and applications of microalgae fertilizers represent a significant barrier to market growth. Despite the growing interest in sustainable agricultural practices, many farmers may be unfamiliar with microalgae-based fertilizers and their potential advantages. Efforts to educate farmers about the agronomic benefits, environmental advantages, and practical considerations of using microalgae fertilizers are essential to overcome adoption barriers and stimulate market demand.
Perceived Risk and Uncertainty:
Perceived risk and uncertainty surrounding the efficacy and performance of microalgae fertilizers can deter potential adopters from incorporating these products into their farming practices. Farmers may be hesitant to deviate from conventional fertilization methods that they are familiar with and have proven results. Concerns about inconsistent results, unfamiliar application techniques, and compatibility with existing cropping systems may contribute to a reluctance to adopt microalgae fertilizers, even in the face of mounting environmental and sustainability pressures.
Supply Chain Vulnerability and Market Volatility:
The US microalgae fertilizers market is susceptible to supply chain vulnerabilities and market volatility, which can impact product availability and pricing dynamics. Dependency on limited sources of microalgae biomass, disruptions in cultivation or processing operations, and fluctuations in raw material costs can disrupt supply chain continuity and lead to price fluctuations. Market volatility and uncertainty can pose challenges for market players in terms of planning, investment, and business sustainability.
Key players
- Cyanotech Corporation
- Earthrise Nutritionals LLC
- Algafeed
- Algatek
- Valensa International
- Algenol Biofuels Inc.
- Nutrex Hawaii
- Corbion NV
- Cellana LLC
- Algix LLC
Recent Developments
- DIC Corporation unveiled plans in September 2022 to allocate approximately US$9.0 million towards environmental initiatives, earmarking investments for two subsidiaries. These subsidiaries specialize in the production of edible blue-green algae, commonly known as spirulina, and the manufacturing of LINABLUE, a natural blue food coloring extracted from spirulina. The investment underscores DIC Corporation's commitment to sustainable practices and eco-friendly solutions, as spirulina is renowned for its nutritional value and environmentally friendly cultivation methods. By investing in these subsidiaries, DIC Corporation aims to bolster their capabilities in producing spirulina-based products while promoting the adoption of natural alternatives in the food and beverage industry.
- In a separate development, AlgaEnergy joined the Technology Platform Food for Life-Spain (PTF4LS) as an associate member in July 2022. Managed by the Spanish Food and Drink Industry Federation (FIAB), PTF4LS stands as a premier technology platform within Spain's agricultural and food sector. AlgaEnergy's affiliation with PTF4LS underscores its commitment to driving innovation and advancing sustainable practices in the food industry. Through collaboration and knowledge exchange facilitated by PTF4LS, AlgaEnergy aims to contribute to the development of cutting-edge solutions that address the evolving needs and challenges of the agricultural and food sector in Spain, further solidifying its position as a key player in the industry.
Regional Analysis
The West Coast region of the United States represents a significant market for microalgae fertilizers, accounting for approximately 35% of the total market share. States such as California, Oregon, and Washington have large agricultural sectors characterized by diverse crop production and a strong emphasis on sustainability. The favorable climate and progressive farming practices in this region create ideal conditions for the adoption of microalgae-based fertilizers, which are valued for their ability to improve soil health, enhance crop productivity, and support organic farming principles.
The Midwest region, often referred to as the nation's breadbasket, commands a substantial share of the US microalgae fertilizers market, accounting for approximately 30% of total market share. States like Iowa, Illinois, and Indiana are major producers of corn, soybeans, and other commodity crops, where microalgae fertilizers are increasingly utilized to optimize nutrient management and mitigate environmental impacts. The Midwest's large-scale agricultural operations and focus on maximizing yields make it a key target market for companies seeking to penetrate the microalgae fertilizers segment.
The Southeast region of the US holds a notable share of the microalgae fertilizers market, accounting for approximately 20% of total market share. States such as Florida, Georgia, and North Carolina have diverse agricultural landscapes, including specialty crops, fruits, vegetables, and ornamentals. Microalgae fertilizers are gaining popularity in the Southeast due to their efficacy in promoting plant growth, improving soil fertility, and reducing reliance on chemical inputs. The region's mild climate and growing demand for sustainable agricultural solutions contribute to the adoption of microalgae-based fertilizers among farmers and growers.
The Northeast region of the US commands a smaller but significant share of the microalgae fertilizers market, accounting for approximately 15% of total market share. States like New York, Pennsylvania, and Vermont have a strong focus on organic farming, environmental stewardship, and local food production, driving demand for eco-friendly fertilization practices. Microalgae fertilizers are increasingly integrated into sustainable agriculture initiatives and regenerative farming systems in the Northeast, where consumers prioritize food quality, environmental responsibility, and community-based agriculture.
Future Outlook
- The US microalgae fertilizers market is poised for sustained growth, driven by increasing adoption of sustainable agricultural practices and growing awareness of the benefits of microalgae-based fertilizers.
- With the rise in consumer demand for organic produce, the market for microalgae fertilizers is expected to expand further as organic farmers seek eco-friendly alternatives to synthetic fertilizers.
- Ongoing advancements in cultivation techniques, formulation processes, and application methods will lead to the development of more efficient and effective microalgae fertilizers, enhancing their performance and market competitiveness.
- Microalgae fertilizers will increasingly be integrated into precision agriculture systems, allowing for targeted nutrient application based on real-time data and crop requirements, thereby optimizing resource use and improving yield potential.
- Regulatory support for sustainable agriculture and the establishment of standardized certification schemes for microalgae fertilizers will provide clarity and assurance to farmers and consumers, fostering market growth and confidence.
- Collaborations between industry stakeholders, research institutions, and government agencies will drive innovation and knowledge exchange, leading to the development of new products and technologies to address evolving market needs.
- The emphasis on soil health and regenerative agriculture practices will drive demand for microalgae fertilizers, which play a crucial role in improving soil fertility, structure, and microbial activity, thereby enhancing overall agricultural sustainability.
- Microalgae fertilizers will find new applications beyond traditional crop cultivation, including turf management, landscaping, and specialty crop production, expanding market opportunities and diversifying revenue streams for manufacturers.
- Efforts to educate consumers about the environmental and health benefits of microalgae-based fertilizers will create demand pull, prompting more farmers to adopt these sustainable alternatives and driving market growth.
- As awareness of microalgae fertilizers spreads globally, US manufacturers will explore opportunities to expand their presence in international markets, leveraging their expertise and technology leadership to capture a larger share of the growing global demand for sustainable agricultural solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the US Microalgae Fertilizers Market in 2023, 2032, and its Compound Annual Growth Rate (CAGR)?
What is driving the growth of the US Microalgae Fertilizers Market?
Why are microalgae fertilizers gaining popularity among farmers?
What are the key segments of the US Microalgae Fertilizers Market?
What are the future trends and outlook for the microalgae fertilizers market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 US Microalgae Fertilizers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global US Microalgae Fertilizers Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 8,380.44 million → forecast year: USD 20,651.05 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 US Microalgae Fertilizers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. US Microalgae Fertilizers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 US Microalgae Fertilizers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 US Microalgae Fertilizers Market Drivers
- 3.3 US Microalgae Fertilizers Market Restraints & Challenges
- 3.4 US Microalgae Fertilizers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 US Microalgae Fertilizers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 US Microalgae Fertilizers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, US Microalgae Fertilizers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 US Microalgae Fertilizers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. US Microalgae Fertilizers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the US Microalgae Fertilizers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 US Microalgae Fertilizers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 US Microalgae Fertilizers Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 US Microalgae Fertilizers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in US Microalgae Fertilizers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New US Microalgae Fertilizers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global US Microalgae Fertilizers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America US Microalgae Fertilizers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe US Microalgae Fertilizers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific US Microalgae Fertilizers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America US Microalgae Fertilizers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East US Microalgae Fertilizers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa US Microalgae Fertilizers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. US Microalgae Fertilizers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
