
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Middle East and Africa Consumer Appliance Market Size 2023 | USD 24.00 billion |
| Middle East and Africa Consumer Appliance Market, CAGR | 4.31% |
| Middle East and Africa Consumer Appliance Market Size 2032 | USD 35.39 billion |
Market Overview
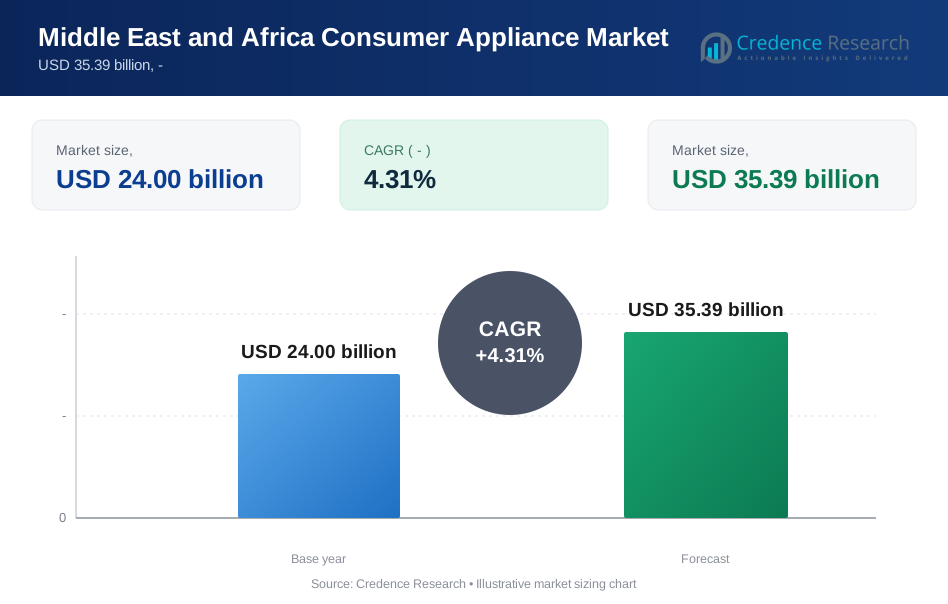
The Middle East and Africa Consumer Appliance Market is projected to grow from USD 24.00 billion in 2023 to an estimated USD 35.39 billion by 2032, with a compound annual growth rate (CAGR) of 4.31% from 2024 to 2032. This growth is driven by increasing urbanization, rising disposable incomes, and a growing preference for energy-efficient appliances.
Key market drivers include the region's rapid urbanization, which is leading to increased demand for modern household appliances, and the rising consumer awareness of energy efficiency and sustainability. Additionally, the penetration of smart technologies in appliances, combined with government initiatives to promote energy-saving products, are notable trends influencing market growth. The market is also seeing an increasing shift towards premium and innovative products as consumers seek enhanced convenience and lifestyle improvements.
Geographically, the United Arab Emirates, Saudi Arabia, and South Africa are significant markets within the region, accounting for substantial shares due to their higher disposable incomes and advanced retail infrastructures. Key players in the Middle East and Africa Consumer Appliance Market include LG Electronics, Samsung Electronics, Whirlpool Corporation, Bosch, and Electrolux, all of whom are investing in product innovation and expanding their presence to capitalize on the growing demand in this region.
Market Drivers
Rapid Urbanization and Population Growth
The Middle East and Africa region is experiencing significant urbanization and population growth, driving demand for consumer appliances. Government surveys indicate a steady increase in urban populations across countries like Nigeria, Egypt, and Saudi Arabia. This urbanization is leading to new residential developments and a rise in nuclear families, fueling the need for household appliances. Industry reports show strong sales growth for products like refrigerators, washing machines, and air conditioners in urban centers. The expanding middle class, particularly in GCC countries, is driving demand for premium branded appliances offering better functionality and efficiency. Surveys by appliance manufacturers reveal growing youth populations are contributing to adoption of smart, connected appliances. Leading companies report rising sales of IoT-enabled devices that can be controlled via smartphones. The demographic shifts towards younger, more urban populations are expected to sustain long-term demand growth. Government housing initiatives in countries like Saudi Arabia are also boosting new household formation and appliance purchases.
Rising Disposable Income and Changing Lifestyles
Increasing disposable incomes across the MEA region are a key driver of the consumer appliance market. Economic data from GCC countries shows steady growth in average household incomes. This is coupled with changing consumer preferences emphasizing convenience and lifestyle enhancement. Surveys by major appliance brands indicate consumers are willing to spend more on advanced features and energy efficiency. The affluent population segment is driving demand for luxury appliances from international brands. Industry reports show strong sales growth for high-end refrigerators, washing machines and other white goods. The trend towards smart homes is gaining traction, especially in tech-savvy markets like the UAE. Leading manufacturers report increasing integration of appliances with home automation systems. Consumer surveys reveal growing interest in remote-controlled smart appliances. E-commerce platforms are seeing rising online sales of consumer electronics and home appliances. Changing work patterns, including more remote work, are also influencing appliance purchases as consumers spend more time at home.
Government Initiatives and Energy Efficiency Regulations
Government initiatives promoting energy efficiency are shaping the MEA consumer appliance market. Countries like the UAE, Saudi Arabia and South Africa have introduced energy efficiency standards and labeling requirements. Regulatory data shows steady tightening of minimum energy performance standards. This has led to increased sales of energy-efficient models, as reported by leading manufacturers. Government rebate programs for energy-efficient appliances have boosted adoption in some markets. Industry surveys indicate rising consumer awareness of energy labels and lifecycle cost savings. Appliance companies are innovating to meet efficiency standards while enhancing performance. New product launches increasingly emphasize energy-saving features. Some governments are also promoting local manufacturing of appliances to boost domestic industries. This is creating opportunities for joint ventures and technology transfers. Overall, the regulatory push for sustainability is driving development of greener appliances across product categories. Consumer surveys show growing preference for eco-friendly options, especially among younger demographics.
Expansion of E-commerce and Retail Infrastructure
The expansion of e-commerce platforms and the modernization of retail infrastructure in the MEA region are also significant drivers of the consumer appliance market. The rise of online shopping has made it easier for consumers to access a wide range of appliances, compare prices, and make informed purchasing decisions from the comfort of their homes. E-commerce platforms such as Amazon, Noon, and Jumia have established a strong presence in the region, offering consumers access to a diverse selection of local and international brands. This shift towards online shopping is particularly pronounced in urban areas, where consumers are increasingly opting for the convenience and variety offered by e-commerce. In addition to e-commerce, the development of modern retail outlets, hypermarkets, and specialty stores is enhancing the accessibility of consumer appliances across the region. Retail giants like Carrefour, Lulu Hypermarket, and Al-Futtaim have expanded their presence in key markets, offering consumers a wide range of appliances under one roof. These retail outlets often provide attractive financing options, discounts, and after-sales services, which are further driving the demand for consumer appliances. The growth of organized retail is also enabling manufacturers to reach a broader customer base, particularly in emerging markets within the region.
Market Trends
Growing Demand for Smart and Connected Appliances
One of the most significant trends shaping the Middle East and Africa Consumer Appliance Market is the increasing demand for smart and connected appliances. As the region witnesses rapid urbanization and the expansion of smart city initiatives, there is a growing consumer preference for appliances that can be integrated into smart home ecosystems. This trend is particularly strong in countries like the United Arab Emirates, Saudi Arabia, and South Africa, where the adoption of Internet of Things (IoT) technology is on the rise. Consumers are increasingly seeking appliances that offer remote control capabilities, energy efficiency, and enhanced convenience through smartphone apps or voice-activated systems. For instance, a survey conducted by a leading home appliance manufacturer in the UAE found that over half of respondents expressed interest in purchasing smart appliances within the next year. Products such as smart refrigerators, washing machines, and air conditioners that can be managed remotely are becoming more popular, driven by the desire for increased convenience and energy savings. This shift is prompting manufacturers to innovate and develop appliances with advanced connectivity features, ensuring compatibility with various smart home platforms.
Increased Focus on Energy Efficiency and Sustainability
Another prominent trend in the Middle East and Africa Consumer Appliance Market is the heightened focus on energy efficiency and sustainability. With governments across the region implementing stricter energy efficiency regulations and promoting sustainability initiatives, both consumers and manufacturers are placing greater emphasis on eco-friendly appliances. For example, the UAE and Saudi Arabia have introduced stringent energy labeling standards, encouraging the adoption of appliances that consume less energy and reduce carbon footprints. This trend is being further driven by the growing consumer awareness of environmental issues and the long-term cost savings associated with energy-efficient appliances. For instance, a government-sponsored study in South Africa revealed that households using energy-efficient appliances reported an average reduction in their electricity bills. As a result, there is a rising demand for products such as energy-efficient air conditioners, refrigerators, and washing machines, which not only meet regulatory requirements but also offer lower operating costs. Manufacturers are responding to this trend by investing in research and development to create appliances that not only comply with energy efficiency standards but also align with consumers' growing environmental consciousness, thereby positioning themselves as leaders in the sustainability space.
Market Restraints and Challenges
Economic Instability and Fluctuating Currency Rates
The Middle East and Africa Consumer Appliance Market faces significant challenges due to economic instability and fluctuating currency rates in the region. Many countries, especially those dependent on oil exports, have experienced economic volatility linked to global oil price fluctuations. This uncertainty often leads consumers to prioritize essential needs over discretionary purchases like appliances. For instance, a substantial portion of households in oil-dependent Gulf countries reported delaying major appliance purchases due to economic concerns. Currency fluctuations further compound the issue, particularly in countries with weaker economies. The devaluation of local currencies against major global currencies like the US dollar or Euro has made imported appliances more expensive. A government economic report from a North African country highlighted how currency devaluation had significantly increased the cost of imported goods, including home appliances, over a recent period. This economic environment creates challenges for both consumers and manufacturers, impacting affordability, demand, and profit margins in the consumer appliance sector.
Inadequate Infrastructure and Supply Chain Disruptions
Inadequate infrastructure and frequent supply chain disruptions pose substantial challenges to the Middle East and Africa Consumer Appliance Market. Many areas, particularly in Sub-Saharan Africa, struggle with poor transportation networks, unreliable electricity supply, and limited access to modern retail channels. A comprehensive study by an international development organization revealed that a significant portion of rural households in several African countries lack reliable access to electricity, hindering the use and adoption of many household appliances. These infrastructural challenges increase costs for manufacturers and retailers, who must invest heavily in logistics to reach consumers in remote or underdeveloped areas. Additionally, the region is prone to supply chain disruptions due to geopolitical tensions and logistical inefficiencies. A survey of major appliance retailers in the Middle East reported frequent stock shortages and delivery delays due to supply chain issues. The reliance on imported components and finished products further exacerbates these challenges. For example, data from a regional trade association showed that most countries in the region heavily depend on imports for consumer electronics and appliances, making the market vulnerable to global supply chain shocks.
Market Segmentation Analysis
By Product Type
The Middle East and Africa Consumer Appliance Market encompasses a diverse range of product segments, each driven by unique consumer needs and regional trends. Kitchen appliances like refrigerators, ovens, and dishwashers are in high demand as consumers focus on modernizing their kitchens. Small appliances such as toasters, blenders, and coffee makers are growing in popularity due to their convenience. Washing machines are seeing increased adoption as technology advances and energy efficiency improves. Air purifiers are gaining traction as awareness of air quality issues rises. Water heaters and purifiers remain essential, driven by climate needs and health consciousness. Cloth dryers are becoming more common in urban areas with limited drying space. Air conditioners are crucial in the region's hot climate, with smart and energy-efficient models leading growth. The "others" category, including vacuum cleaners and personal care items, adds further diversity to the market. For instance, a recent survey by a leading appliance manufacturer found that smart kitchen appliances with connectivity features are increasingly preferred by Middle Eastern consumers, especially in affluent urban areas.
By End Use
The consumer appliance market in the Middle East and Africa is segmented into several key end-use categories, each with distinct characteristics and growth drivers. The domestic segment remains the largest, fueled by rising household incomes and changing lifestyles that prioritize modern conveniences. Professional appliances are seeing increased demand due to the expansion of office spaces and commercial infrastructure across the region. The hotels segment is benefiting from the robust growth of the hospitality industry, particularly in tourist-heavy areas. Salon and grooming parlors are driving demand for specialized appliances as the personal care industry expands. Cafeterias and restaurants require efficient, commercial-grade equipment to meet the needs of a growing food service sector. Offices and institutes contribute to market growth with appliances tailored to professional settings. The "others" category covers various niche applications across different industries. For instance, a government survey in a Gulf country revealed that energy-efficient appliances are increasingly mandated in new commercial and institutional buildings, driving demand in these segments.
Segments
Based on Product Type
- Kitchen Appliances
- Small Appliances
- Washing Machines
- Air Purifiers
- Water Heaters
- Water Purifiers
- Cloth Dryers/Tumblers
- Air Conditioners
- Others
Based on End Use
- Domestic
- Professional
- Hotels
- Salon & Grooming Parlors
- Cafeteria & Restaurants
- Offices & Institutes
- Others
Based on Sales Channel
- Offline
- Organized Retailer
- Unorganized
- Online
- Company Direct Sales
- Independent Vendor/E-Commerce
Based on Region
- Gulf Cooperation Council (GCC) Countries
- North Africa
- Sub-Saharan Africa
Regional Analysis
Middle East (60%):
The Middle East region holds a significant share in the Consumer Appliance Market, accounting for approximately 60% of the total market in the Middle East and Africa. This dominance is driven by countries such as Saudi Arabia, the United Arab Emirates (UAE), and Qatar, which have high disposable incomes and a strong demand for advanced and luxury consumer appliances. For instance, surveys conducted by major appliance manufacturers indicate that urbanization and economic development in these nations have led to increased household spending on modern appliances, including smart home technologies and energy-efficient solutions. The UAE, in particular, is a major hub for high-end and innovative appliances due to its affluent population and emphasis on luxury living.
North Africa (25%):
North Africa, including countries like Egypt, Morocco, and Algeria, represents approximately 25% of the total market share. The region is characterized by a growing middle class and increasing urbanization, which are driving the demand for household appliances. For instance, government data from countries like Egypt and Morocco show that economic reforms and improvements in infrastructure are enhancing market access and affordability. However, industry reports suggest the region faces challenges such as economic instability and fluctuating currency rates, which can impact consumer spending and market growth. Despite these challenges, consumer surveys indicate rising awareness and government efforts to improve living standards contribute to the steady growth of the consumer appliance market in North Africa.
Key players
- Samsung Electronics
- General Electric (GE) Appliances
- Midea Group
- Sharp Corporation
- LG Electronics Inc. (LG)
- Toshiba Corporation
- Panasonic Corporation (Panasonic)
- Godrej Appliances
Competitive Analysis
In the Middle East and Africa Consumer Appliance Market, key players such as Samsung Electronics, LG Electronics, and General Electric (GE) Appliances lead with their advanced technologies and strong brand presence. Samsung and LG dominate with their extensive range of smart appliances and innovative features, appealing to the growing consumer demand for connected and energy-efficient products. General Electric focuses on delivering robust and reliable appliances suited for both residential and professional use. Midea Group and Panasonic offer competitive pricing and energy-efficient solutions, targeting cost-conscious consumers. Sharp Corporation and Toshiba Corporation emphasize product quality and technological advancements to capture market share. Godrej Appliances, with its local manufacturing and cost-effective solutions, caters to regional needs and preferences, differentiating itself through affordability and durability. Overall, the competitive landscape is characterized by technological innovation, brand strength, and varying pricing strategies to address diverse consumer demands across the region.
Recent Developments
- In April 2024, Samsung Electronics unveiled the Galaxy Tab S6 Lite (2024), an upgraded version of their popular tablet. This new model features:
- Dex Mode with Tab One UI for improved multitasking
- Doubled storage capacity (128GB)
- A new Mint color option
- Exynos 1280 processor for enhanced productivity
- Advanced note-taking features including 300% zoom and handwriting conversion
- In May 2024, GE Appliances unveiled its digital 2023 GE Appliances Report, showcasing new packaging guidelines and innovative products.
- In January 2023, GE Appliances launched the GE Profile Smart Mixer with AutoSense, which was named a CES Innovation Award Honoree.
- In January 2024, LG showcased its latest smart life solutions at CES 2024, extending beyond the home to various spaces including mobility.
- In July 2023, As part of Manchester City's Summer 2023 Asia-Pre-Season-Tour, Midea surprised local fans in Tokyo with a food truck featuring soccer stars Erling Haaland, John Stones, and Cole Palmer.
Market Concentration and Characteristics
The Middle East and Africa Consumer Appliance Market exhibits moderate concentration with a mix of dominant global players and regional brands. Major international companies like Samsung Electronics, LG Electronics, and General Electric (GE) Appliances hold significant market shares due to their advanced technologies, broad product ranges, and strong brand recognition. These players leverage their global expertise to cater to the region's demand for high-quality and innovative appliances. Concurrently, regional brands such as Godrej Appliances and local manufacturers play a crucial role by offering cost-effective solutions tailored to local preferences and economic conditions. The market is characterized by competitive pricing, technological advancements, and varying consumer preferences, influenced by factors such as economic stability, urbanization, and infrastructure development across different countries. This diverse landscape requires companies to adapt their strategies to cater to both affluent and emerging market segments effectively.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End Use, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rapid urbanization across the region will continue to drive demand for modern and efficient consumer appliances as more households seek to upgrade their living standards.
- The trend towards smart home integration will gain momentum, with consumers increasingly investing in connected and energy-efficient appliances.
- The expanding middle class in countries like Saudi Arabia, the UAE, and South Africa will fuel demand for a diverse range of household appliances, from basic to premium products.
- With heightened environmental awareness and government regulations, there will be a growing emphasis on energy-efficient and eco-friendly appliances.
- Continuous innovations in appliance technology, including AI and IoT, will enhance functionality and convenience, attracting tech-savvy consumers.
- The rise of e-commerce platforms will provide consumers with easier access to a wide range of appliances, boosting online sales and digital engagement.
- Improved infrastructure and urban planning will facilitate better distribution and availability of consumer appliances, particularly in emerging markets.
- Enhanced local manufacturing capabilities will help reduce costs and improve affordability, addressing the needs of cost-conscious consumers.
- Companies will focus on offering customized solutions to cater to regional preferences and specific consumer needs, fostering brand loyalty and market growth.
- Adapting to evolving regulatory standards on energy efficiency and safety will be crucial for companies to maintain market compliance and competitive edge.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Middle East and Africa Consumer ApplianceMarket?
What are the main drivers of growth in this market?
Which countries are leading in the Middle East and Africa Consumer Appliance Market?
How are changing lifestyles impacting the consumer appliance market?
Who are the key players in the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East and Africa Consumer Appliance Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East and Africa Consumer Appliance Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 24.00 billion → forecast year: USD 35.39 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East and Africa Consumer Appliance Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East and Africa Consumer Appliance Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East and Africa Consumer Appliance Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East and Africa Consumer Appliance Market Drivers
- 3.3 Middle East and Africa Consumer Appliance Market Restraints & Challenges
- 3.4 Middle East and Africa Consumer Appliance Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East and Africa Consumer Appliance Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East and Africa Consumer Appliance Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East and Africa Consumer Appliance category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East and Africa Consumer Appliance Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East and Africa Consumer Appliance Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East and Africa Consumer Appliance market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East and Africa Consumer Appliance Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East and Africa Consumer Appliance Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East and Africa Consumer Appliance Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East and Africa Consumer Appliance (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East and Africa Consumer Appliance Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East and Africa Consumer Appliance Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East and Africa Consumer Appliance Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East and Africa Consumer Appliance Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East and Africa Consumer Appliance Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East and Africa Consumer Appliance Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East and Africa Consumer Appliance Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East and Africa Consumer Appliance Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East and Africa Consumer Appliance Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
