
Market Overview
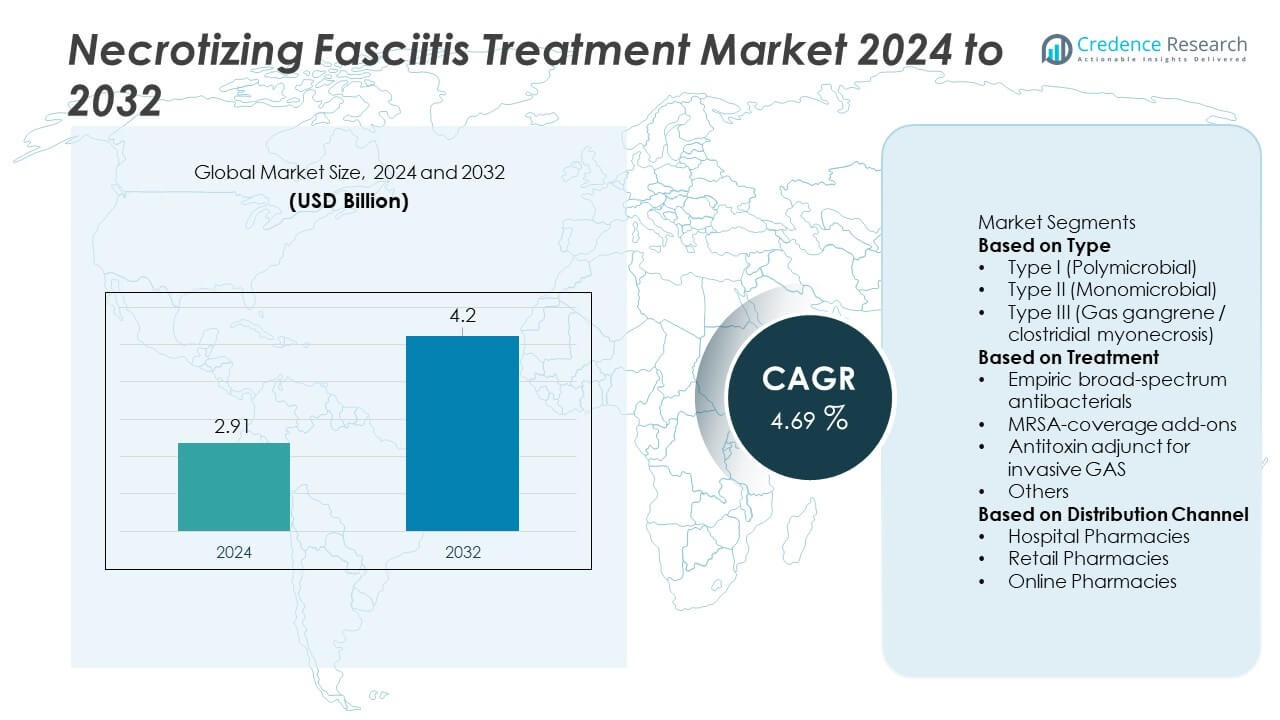
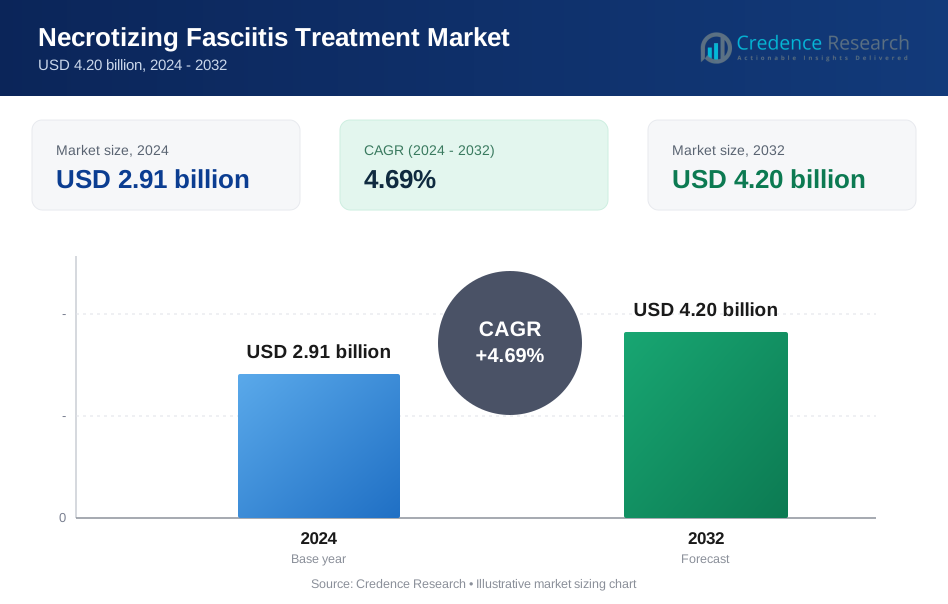
Necrotizing Fasciitis Treatment market size was valued at USD 2.91 billion in 2024 and is projected to reach USD 4.2 billion by 2032, expanding at a CAGR of 4.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Necrotizing Fasciitis Treatment Market Size 2024 | USD 2.91 Billion |
| Necrotizing Fasciitis Treatment Market, CAGR | 4.69% |
| Necrotizing Fasciitis Treatment Market Size 2032 | USD 4.2 Billion |
The Necrotizing Fasciitis Treatment market is driven by key players including Pfizer, Merck & Co. (MSD), Gilead Sciences, Astellas Pharma, Basilea Pharmaceutica, Takeda, CSL Behring, Grifols, Octapharma, and Hikma Pharmaceuticals, all contributing to critical antimicrobial, antitoxin, and supportive-therapy advancements. These companies strengthen hospital treatment capabilities through broad-spectrum antibiotics, MRSA-directed agents, and immune-supportive products used in severe cases. North America leads the market with 39% share, supported by advanced critical-care infrastructure, while Europe holds 31% share due to strong clinical guidelines and early diagnostic adoption. Asia Pacific follows with 22% share, driven by increasing prevalence and expanding hospital capacity.
Market Insights
- The Necrotizing Fasciitis Treatment market reached USD 2.91 billion in 2024 and is projected to reach USD 4.20 billion by 2032, expanding at a CAGR of 4.69% during the forecast period.
- Key drivers include rising cases among diabetic, immunocompromised, and elderly patients, with Type I (Polymicrobial) leading the type segment with 49% share due to its higher clinical burden and need for broad-spectrum therapy.
- Major trends include growing adoption of rapid diagnostics, increased use of antitoxin adjuncts for invasive GAS, and expansion of advanced wound-care technologies that support faster stabilization.
- The competitive landscape is shaped by Pfizer, Merck & Co. (MSD), Gilead Sciences, Astellas Pharma, Basilea Pharmaceutica, Takeda, CSL Behring, Grifols, Octapharma, and Hikma, all enhancing antimicrobial and immune-supportive portfolios.
- Regionally, North America leads with 39% share, Europe holds 31%, and Asia Pacific follows with 22%, while Latin America and the Middle East & Africa account for 5% and 3%, driven by improving hospital capacity and rising chronic disease prevalence.
Market Segmentation Analysis:
By Type
Type I (Polymicrobial) accounted for the dominant 49% share, driven by its high prevalence in diabetic, immunocompromised, and elderly patients. This subtype often requires aggressive intervention due to multiple bacterial pathogens, increasing demand for broad-spectrum and combination-based therapy. Type II (Monomicrobial) cases, mainly linked to Streptococcus pyogenes, also grew due to rising invasive GAS infections across hospital settings. Type III (Gas gangrene) remained less common but required rapid surgical and antimicrobial management. The strong clinical burden of polymicrobial cases continues to shape treatment protocols and expand the need for advanced diagnostic and therapeutic approaches.
- For instance, Smith & Nephew introduced a debridement system (the VERSAJET Hydrosurgery System) that uses a high-velocity, focused jet of saline to tangentially cut and remove devitalized tissue and foreign matter via the Venturi effect, supporting a faster surgical response.
By Treatment
Empiric broad-spectrum antibacterials held the largest 58% share, as clinicians initiate immediate coverage to manage rapidly spreading necrotizing infections. These regimens target mixed aerobic and anaerobic organisms, making them essential for early stabilization. MRSA-coverage add-ons gained adoption due to increasing community and hospital MRSA cases. Antitoxin adjunct therapy for invasive GAS showed growth as guidelines encouraged clindamycin and IVIG use for toxin suppression. Other supportive treatments, including wound care and debridement adjuncts, continued to support overall management. The dominance of empiric therapy reflects urgent care needs and guideline-driven broad antimicrobial use.
- For instance, Grifols has significantly expanded its global immunoglobulin (IVIG) purification and manufacturing capacity, with its flagship Clayton, North Carolina, site alone capable of processing 12 million liters of plasma annually.
By Distribution Channel
Hospital pharmacies dominated the market with a 64% share, driven by the critical nature of necrotizing fasciitis, which requires immediate hospitalization, IV antibiotics, and surgical intervention. These settings manage most acute cases, ensuring rapid drug availability and specialist oversight. Retail pharmacies saw moderate uptake for post-discharge prescriptions and supportive medications. Online pharmacies observed gradual growth as patients accessed follow-up therapies and wound-care supplies after stabilization. The strong share of hospital pharmacies highlights the emergency-driven nature of treatment and the dependence on in-facility drug administration for severe soft-tissue infections.
Key Growth Drivers
Rising Incidence in High-Risk Populations
Cases increase as more patients face diabetes, obesity, and weakened immunity. Hospitals report higher admissions linked to polymicrobial infections in aging populations. Early detection tools improve identification, pushing demand for rapid treatment. Growing awareness among clinicians supports faster use of advanced antibiotics and surgical care. The expanding pool of vulnerable patients strengthens long-term need for optimized therapy plans.
- For instance, bioMérieux advanced hospital readiness with its BIOFIRE BCID2 Panel, capable of detecting 43 targets (including bacteria, yeast, and antimicrobial resistance genes) associated with bloodstream infections in one test cycle of about an hour from a positive blood culture.
Advancements in Antimicrobial and Adjunctive Therapies
Broader antibacterial regimens improve survival by targeting mixed pathogens. New combinations support faster stabilization in severe presentations. Antitoxin therapies reduce tissue damage in invasive GAS cases. Updated guidelines promote aggressive, evidence-based treatment across emergency settings. These improvements increase drug utilization and drive demand for specialized options.
- For instance, the antibiotic daptomycin (Cubicin), which is now owned by Merck, uses a 6 mg/kg once-daily IV dosing strategy to treat S. aureus bloodstream infections, including MRSA bacteremia, and this is supported by guideline-based recommendations.
Strengthening Hospital Infrastructure for Critical Care
More hospitals expand emergency and surgical capacity for complex infections. Improved access to IV therapy and advanced wound care boosts treatment outcomes. Rapid debridement teams reduce complications and improve patient survival. Investments in intensive care units support recovery for severe cases. Better-equipped centers strengthen reliance on hospital-based pharmacy channels.
Key Trends & Opportunities
Growing Adoption of Rapid Diagnostic and Imaging Tools
Hospitals adopt faster diagnostic systems to detect early soft-tissue damage. Point-of-care imaging supports swift decisions during critical stages. Early confirmation encourages immediate initiation of broad-spectrum therapy. Rising demand for speed boosts adoption of molecular panels and AI-supported scans. Better detection creates opportunities for integrated treatment platforms.
- For instance, Siemens Healthineers improved emergency imaging by deploying its SOMATOM go.Up CT system, a 32 to 64-slice detector scanner that can perform a low-dose lung protocol scan in as little as 9 seconds for a 33 cm length.
Expansion of Post-Acute and Supportive Care Solutions
Recovery care supports long-term healing after initial stabilization. Demand increases for wound therapies, infection-control supplies, and rehabilitation services. Retail and online pharmacies supply follow-up medications for continued recovery. Patient education programs support better compliance and improve outcomes. This growing segment unlocks new commercial opportunities across outpatient care.
- For instance, Walgreens utilizes micro-fulfillment centers that, in one automated facility, can process 35,000 prescription orders per day to allow pharmacists more time to provide care and other services for patients.
Key Challenges
Rising Antimicrobial Resistance Across Key Pathogens
Resistance reduces effectiveness of standard regimens in many regions. Clinicians face difficulty choosing optimal therapy under urgent conditions. Increased MRSA and resistant anaerobes complicate empirical coverage. Hospitals require stronger stewardship to preserve drug efficacy. These issues raise treatment complexity and increase healthcare burdens.
Delayed Diagnosis and Limited Awareness in Early Stages
Early symptoms often resemble minor infections, leading to late intervention. Delayed care increases tissue loss and raises mortality. Many regions lack rapid diagnostic tools for timely detection. Limited clinical training adds risk in under-resourced facilities. These gaps create serious challenges for consistent treatment success.
Regional Analysis
North America
North America held the largest 39% share, supported by strong critical-care infrastructure and high awareness among clinicians. The region reports a rising number of cases linked to diabetes, obesity, and invasive GAS infections, increasing demand for rapid diagnostics and broad-spectrum therapies. Hospitals maintain well-established emergency pathways that enable immediate surgical intervention and IV antimicrobial use. Expansion of advanced wound-care centers further strengthens treatment capacity. Favorable reimbursement frameworks and access to specialist teams contribute to improved outcomes. These factors reinforce North America’s leading role in necrotizing fasciitis treatment adoption.
Europe
Europe accounted for 31% share, driven by well-developed hospital networks and strong adherence to early intervention guidelines. Countries across Western Europe adopt standardized protocols that combine rapid debridement, broad-spectrum therapy, and intensive post-operative care. Increasing cases linked to aging populations and chronic comorbidities strengthen treatment demand. Enhanced diagnostic systems such as MRI and rapid blood markers support timely diagnosis. Research initiatives across Germany, France, and the UK promote evidence-based therapy optimization. Europe’s expanding antimicrobial stewardship programs also guide effective treatment choices, sustaining the region’s strong market contribution.
Asia Pacific
Asia Pacific captured 22% share, supported by rising disease prevalence, growing healthcare access, and expanding hospital capacity. Large populations with increasing rates of diabetes and soft-tissue infections drive higher case volumes. Countries such as India, China, and Indonesia report improved emergency responsiveness and expanded surgical care availability. Investments in ICU facilities, infection control, and antimicrobial access strengthen treatment adoption. Governments promote awareness programs that encourage early hospital visits, reducing severe complications. Rapid urbanization and improving diagnostic tools further accelerate demand for comprehensive necrotizing fasciitis management.
Latin America
Latin America represented 5% share, influenced by increasing healthcare modernization and higher recognition of soft-tissue infections. Brazil and Mexico lead adoption due to expanding tertiary hospitals equipped for emergency surgical care. However, delayed diagnosis remains common in remote regions, increasing reliance on aggressive antimicrobial therapy once patients reach advanced facilities. Growth in public-health investments improves access to debridement and wound-care services. Rising chronic disease burden elevates infection risks, strengthening treatment demand. The region continues to expand critical-care services, supporting gradual improvement in clinical outcomes.
Middle East & Africa
The Middle East & Africa region held 3% share, shaped by rising hospital investment and growing attention to severe bacterial infections. Gulf countries enhance emergency and surgical capabilities, enabling faster response to necrotizing infections. African nations rely heavily on public hospitals, where late diagnosis remains a barrier. Increasing training programs for early symptom recognition support improved intervention rates. International partnerships boost access to broad-spectrum antibiotics and wound-care supplies. Despite infrastructure gaps, expanding healthcare facilities and rising chronic disease prevalence drive steady growth in treatment adoption.
Market Segmentations:
By Type
- Type I (Polymicrobial)
- Type II (Monomicrobial)
- Type III (Gas gangrene / clostridial myonecrosis)
By Treatment
- Empiric broad-spectrum antibacterials
- MRSA-coverage add-ons
- Antitoxin adjunct for invasive GAS
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights leading companies such as Pfizer, Merck & Co. (MSD), Gilead Sciences, Astellas Pharma, Basilea Pharmaceutica, Takeda, CSL Behring, Grifols, Octapharma, and Hikma Pharmaceuticals, which contribute significantly to advancements in necrotizing fasciitis treatment. These players focus on broad-spectrum antimicrobials, MRSA-targeted therapies, antitoxin adjuncts, and immune-supportive products essential for managing severe soft-tissue infections. Many companies invest in expanding IV antibiotic portfolios, developing faster-acting formulations, and improving availability of critical care biologics. Strategic collaborations with hospitals and healthcare networks strengthen access to life-saving therapies. Vendors also enhance clinical data generation to support evidence-based treatment protocols. As disease burden grows among high-risk populations, competition intensifies around advanced therapeutics, supportive-care solutions, and comprehensive hospital treatment packages.
Key Player Analysis
- Grifols
- Astellas Pharma
- Octapharma
- Takeda
- CSL Behring
- Pfizer
- Basilea Pharmaceutica
- Hikma Pharmaceuticals
- Merck & Co. (MSD)
- Gilead Sciences
Recent Developments
- In October 2025, Astellas Pharma presented new advances in its oncology portfolio at the European Society for Medical Oncology (ESMO) congress, highlighting data from innovative trials and new indications.
- In June 2024, GSK plc announced the acquisition of Elsie Biotechnologies, a San Diego based private biotechnology company focusing on realizing the full promise of oligonucleotide medicines.
- In January 2024, Merck's Life Science division and Mycenax Biotech signed a non binding Memorandum of Understanding to explore cooperation on new, high capacity bioprocessing solutions for Taiwan and other markets. The MoU aims to integrate Merck's BioContinuum™ Platform into Mycenax's bioprocessing, focusing on automation and digitalization.
Report Coverage
The research report offers an in-depth analysis based on Type, Treatment, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for rapid broad-spectrum therapies will grow as early intervention becomes standard practice.
- Hospitals will expand critical-care units and emergency response pathways to improve treatment speed.
- Adoption of rapid molecular diagnostics will rise to support faster identification of pathogens.
- Use of antitoxin adjuncts for invasive GAS infections will increase as guidelines evolve.
- Wound-care innovations and advanced debridement tools will play a larger role in recovery management.
- MRSA-targeted therapies will see higher demand due to rising resistant infections.
- Clinical training programs will expand to reduce delays in recognizing early symptoms.
- More healthcare systems will invest in multidisciplinary care teams for complex soft-tissue infections.
- Biologic and immune-supportive therapies will gain traction for severe and toxin-mediated cases.
- Emerging markets will strengthen treatment capacity as hospital infrastructure and diagnostic access improve.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence in High-Risk Populations
Increasing prevalence of diabetes, obesity, and immunocompromised conditions is leading to more cases of necrotizing fasciitis, especially among elderly and vulnerable groups. This trend is driving higher demand for rapid diagnosis and aggressive treatment protocols.
Advancements in Antimicrobial and Adjunctive Therapies
Development of broader-spectrum antibiotics, MRSA-targeted agents, and antitoxin adjuncts is improving survival rates and expanding treatment options for severe cases. These innovations are increasing drug utilization and supporting evidence-based clinical guidelines.
Strengthening Hospital Infrastructure for Critical Care
Expansion of emergency and surgical capacity, along with investments in intensive care units and advanced wound-care centers, is enabling faster intervention and better outcomes for necrotizing fasciitis patients. Improved hospital readiness is boosting reliance on in-facility drug administration.
Growing Adoption of Rapid Diagnostic and Imaging Tools
Hospitals are increasingly implementing rapid molecular diagnostics and advanced imaging systems to detect necrotizing fasciitis at earlier stages. Faster identification of pathogens supports immediate initiation of broad-spectrum therapies and reduces complications.
Expansion of Post-Acute and Supportive Care Solutions
As survival rates improve, there is rising demand for wound therapies, infection-control supplies, and rehabilitation services to support long-term recovery. This trend is expanding commercial opportunities in outpatient and follow-up care segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Necrotizing Fasciitis Treatment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Necrotizing Fasciitis Treatment market projected to grow between 2025 and 2032?
Which Necrotizing Fasciitis Treatment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Necrotizing Fasciitis Treatment market?
Who are the leading companies in the Necrotizing Fasciitis Treatment market?
Which region commanded the largest share of the Necrotizing Fasciitis Treatment market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Type I (Polymicrobial)
- 1.2.2 Type II (Monomicrobial)
- 1.2.3 Type III (Gas gangrene / clostridial myonecrosis)
- 1.3 By Treatment
- 1.3.1 Empiric broad-spectrum antibacterials
- 1.3.2 MRSA-coverage add-ons
- 1.3.3 Antitoxin adjunct for invasive GAS
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.91 billion → 2032: USD 4.20 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Necrotizing Fasciitis Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Necrotizing Fasciitis Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Necrotizing Fasciitis Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Necrotizing Fasciitis Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Necrotizing Fasciitis Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Necrotizing Fasciitis Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Necrotizing Fasciitis Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Necrotizing Fasciitis Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.91 billion → 2032: USD 4.20 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Necrotizing Fasciitis Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Type I (Polymicrobial)
- 12.3.7.2 Type II (Monomicrobial)
- 12.3.7.3 Type III (Gas gangrene / clostridial myonecrosis)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Treatment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Empiric broad-spectrum antibacterials
- 12.4.7.2 MRSA-coverage add-ons
- 12.4.7.3 Antitoxin adjunct for invasive GAS
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Necrotizing Fasciitis Treatment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Necrotizing Fasciitis Treatment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Necrotizing Fasciitis Treatment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Pfizer
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Merck & Co. (MSD)
- 17.4 Gilead Sciences
- 17.5 Astellas Pharma
- 17.6 Basilea Pharmaceutica
- 17.7 Takeda
- 17.8 CSL Behring
- 17.9 Grifols
- 17.10 Octapharma
- 17.11 Hikma Pharmaceuticals
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

